manageyourtax.com

Author: Edwin

  • Tax Tips (13) – What is the Tax Residency of Your BVI Company?

    Tax Tips (13) – What is the Tax Residency of Your BVI Company?

    The global crackdown on tax avoidance and money laundering at both individual and corporate levels have brought about a substantial increase in disclosure in the financial world.  Anyone who has the experience of trying to open a bank account for a company would know, as part of the bank’s Know Your Client (KYC) procedure thanks to FATCA and the Common Reporting Standard, that there will be questions on the beneficial owner and tax residency of the company.  If one is lucky enough to have to file the Country-by-Country Report (“CbCR”, see Tax Tips 3), tax residency of every Constituent Entity in the group shall be reported. There could be serious consequences of incorrectly reporting the tax residency.

    Tax residency of a company would be relatively straight-forward if it is incorporated and filed tax returns in a jurisdiction where there is income tax or profits tax.  What if the company is incorporated in a jurisdiction that does not impose income tax (commonly referred to as an “Offshore Company”), such as Tax Havens like the British Virgin Islands (BVI), Bermuda, Western Samoa?  Many people think that Offshore Companies are not subject to tax anywhere…is it really the case?

    Becoming Taxable in Another Jurisdiction

    Business profits of a company (say “Co A” located in Country A) could be subject to tax in another jurisdiction (say Country B) under two situations: (1) Co A has become a tax resident in Country B; or (2) Co A is a tax resident of Country A and has created a Permanent Establishment (“PE”) in Country B.  The difference between the two is that as a tax resident of Country B, Co A may be subject to tax in Country B in full. On the other hand, if a PE is created, only the business profits attributable to the PE is subject to tax in Country B.

    A company can also be taxable in a foreign jurisdiction without tax residency or PE.  That would be the case on capital gains or passive income such as dividend, royalties and interests derived from that foreign jurisdiction.  

    This article focuses on business profits situation one: under what circumstances would a company become a tax resident in a foreign jurisdiction.

    Determination of Tax Residency

    For Hong Kong, the concept of tax residency does not attract too much attention because of the territorial concept of taxation. A foreign company would be taxed in Hong Kong just like a local Hong Kong company when it carries on a trade, profession or business in Hong Kong and derives Hong Kong sourced profits therefrom.

    However, in many residency-based tax jurisdictions, a foreign company would be subject to income tax in full if it is regarded as a tax resident and carries on business in the jurisdiction.  What determines tax residency? Using Australia as an example, a company is a resident of Australia under Subsection 6(1) of the Income tax Assessment Act 1936, if:

    • it is incorporated in Australia, or
    • if it is not incorporated in Australia, it carries on business in Australia and has either:
      • its voting power controlled by shareholders who are resident of Australia (the voting power test of residency), or;
      • its central management and control in Australia (the central management and control test of residency).

    For a company incorporated outside of Australia, the test, essentially, is to lift the corporate veil and see in substance whether the company is really managed and controlled in Australia, just like a company incorporated in Australia.

    Tax residency is also highly relevant in determining if a Double Taxation Agreement/Arrangement (“DTA”) is applicable to the company or not.  Using the DTA entered into between Hong Kong and Mainland China (“HK-CN DTA”) as example, a resident in Hong Kong, for a company, is defined under Article 4(1) of the HK-CN DTA as “a company incorporated in Hong Kong, or if incorporated outside Hong Kong, being normally managed or controlled in Hong Kong”.  Under Article 4(3), when “a person other than an individual is a resident of both Sides, then it shall be deemed to be a resident only of the Side in which its place of effective management is situated”. The place of effective management (“POEM”) is the tie-breaker in determining which Side should the company be regarded as a resident of.  Readers should note that in the OECD Model Tax Convention on Income and on Capital: Condensed Version 2017 (“the 2017 Model Tax Convention”), the tie-breaker clause has been revised such that the two sides shall agree on the matter with due consideration of the place of effective management, place of incorporation and any other relevant factors.  It is however up to the contracting sides to adopt the previous tie-breaker clause, which reads exactly like Article 4(3) of the HK-CN DTA mentioned above.

    Not only is tax residency relevant to Hong Kong under DTAs, the concept is also being introduced under the transfer pricing rules in the Inland Revenue (Amendment) (No.6) Bill 2017 (“the Bill”) which was enacted on 4 July 2018.  “Hong Kong resident person” is defined to mean “a person who is resident for tax purposes in Hong Kong”, and “resident for tax purposes”, for a company, means “a company incorporated in Hong Kong or, if incorporated outside Hong Kong, normally managed or controlled in Hong Kong”.

    The Place of Management and Control

    Among the three terms came across above: the normal place of management and control, the central place of management and control, and the place of effective management (POEM), it appears that the “normal” place of management and control is a comparatively relaxed definition, and thus it may be easier for companies to be considered a tax resident in such case, which may or may not be a good thing.  Legal experts will be able to better differentiate the three terms.

    From a practical standpoint, what corporates would like to avoid, in most situations, is to be regarded as a tax resident unexpectedly.  There will not be a One-Size-Fits-All guidance on what characteristics of management and control would make a company a tax resident of a foreign jurisdiction.  For the purpose of this article, the search is, therefore, for general guidance on The Place of Management and Control (“TPMC”) that corporates can follow to help lower the chance of their Offshore Companies inadvertently become tax residents of residency-based tax jurisdictions.

    Guidance on TPMC

    OECD would be a handy resource to look for an answer.  With the change in the Article 4(3) of the 2017 Model Tax Convention, the Commentary (of the Condensed Version) no longer provides an explanation to POEM.  To understand OECD’s view on the matter, one may go back to the Commentary to the previous version of the Model Convention (Model Tax Convention on Income and on Capital 2014 (Full Version)), which says: “The POEM is the place where key management and commercial decisions that are necessary for the conduct of the entity’s business as a whole are in substance made. All relevant facts and circumstances must be examined to determine the POEM.  An entity may have more than one place of management, but it can have only one POEM at any one time”. This definition is helpful but not in sufficient details for companies to follow and act on.

    A good reference to offshore companies would be the Tax Ruling TR 2018/5 Income Tax: Central Management and Control Test of Residency issued by the Australian Tax Office (ATO) on 21 June 2018 (with an effective date of 15 March 2017).  The three questions related to Central Management and Control are: What is it? Who exercises it? Where is it?

    (1) What does central management and control mean?

    Per TR 2018/5, the key element in the control and direction of a company’s operations is the making of high-level decisions that set the company’s general policies, and determine the direction of its operations and the type of transactions it will enter.  It is different from the day-to-day conduct and management of its activities and operations, which is not ordinarily regarded as an act of central management and control. However, for small companies, their day-to-day conduct and management of a company’s operations might also be an exercise of central management and control.

    What is “decision making”?

    A person, or group of people, make a decision if they actively consider and decide to do, or not do something based on it being in the best interests of the company.  It does not include the mere implementation, or rubber-stamping, of decisions made by others.

    Acts of central management and control

    Exercising central management and control of a company can involve setting investment and operational policy including buying and selling of stock or significant assets, appointing company officers, overseeing and controlling those appointed to carry out the day-to-day business of the company, and matters of finance, including determining how profits are used and the declaration of dividends.

    Matters of company administration such as keeping a company’s share register, accounts, payment of dividend, are not acts of central management and control.

    (2) Who exercises central management and control?

    Identifying who exercises central management and control is a question of fact. It cannot be determined solely by identifying who has the legal power or authority to control and direct a company.  The crucial question is who controls and directs a company’s operations in reality.

    Normally, where a company is run by its directors in accordance with its constitution and the company law rules applicable to that company, which give its directors the power to manage the company, the company’s directors will control and direct its operations.  It follows that ordinarily it is a company’s directors who exercise its central management and control.

    When determining who exercises a company’s central management and control, all the relevant facts and circumstances must be considered. Facts and circumstances to be considered include the role of anyone who assumes the directors’ role in managing and controlling the company’s affairs or has a role in the decision-making processes or governance of the company. Therefore, mere legal power or authority to manage a company is not sufficient to establish an exercise of central management and control. On the other hand, the ATO would also examine who tacitly control and regularly exercise oversight of the affairs of the company. As such, legal authority or power is not necessary for a person to exercise central management and control.  If an outsider actually dictates or controls the decisions made by the directors, the outsider will exercise central management and control of the company.

    The directors’ knowledge of the business is also relevant. A lack of knowledge of the business sufficient to enable them to make decisions, suggests they are not the real decision makers and are more likely rubber-stamping or implementing decisions already made by others.

    (3) Where is central management and control exercised?

    A company will be controlled and directed where those making its high-level decisions do so as a matter of fact and substance. It is not where they are merely recorded and formalised, or where the company’s constitution, bylaws or articles of association require it be controlled and directed if, in reality, it occurs elsewhere.  This will not necessarily be the place where those who control and direct a company live.

    Multiple places of central management and control

    Control and direction of a company may be undertaken by those controlling a company in multiple places. This means a company’s central management and control may be divided between more than one place.  However, a company’s central management and control will only be exercised in a place for the purpose of the central management and control test if it is exercised in that place to a substantial degree, sufficient to conclude the company is really carrying on business there.

    Residence of directors vs residence of a company

    Where a company’s central management and control is exercised is not determined by where the directors, or other persons, who control and manage it, are resident or live.  What matters is where they actually perform the activities to control and direct the company.

    Summary

    TR 2018/5 is a good reference because it is newly issued guidance which presumably has taken into account the latest court cases and BEPS.  According to the ruling, in summary, TPMC is the location where the making of high-level decisions that set the company’s general policies, determine the direction of its operations and the type of transactions it will enter into, are made in substance.   

    The Offshore Company

    Many individuals and corporate groups have set up companies in Offshore Tax Havens such as the BVI for various purposes. Many tax offices around the world see them, understandably, as tax avoidance vehicles because some of these companies book large amount business income from trade, services or intellectual properties.  These individuals or corporate groups are not based in the offshore paradises but in the onshore commercial centres of the world, and often the directors of these offshore companies are the individual themselves or the senior management of the corporate groups.  Even if local residents are appointed as directors, they would be acting as nominee only and tax offices will see-through them. Therefore, if not structured and maintained properly, TPMC of these Offshore Companies would be in the onshore commercial centres where the decisions are made, and the tax and penalties exposures could be significant.  In the past, they could be hidden from sight but in the new transparent world, they will be exposed.

    Offshore Companies are, on the other hand, the ideal type of vehicle for investment holding.  They are inexpensive to maintain, useful in organising the group structure, aligning the financial results with management responsibilities, ring-fence risks, and offer great flexibility when a particular arm of the business is to be disposed of: the transaction can be done quickly without burdensome governmental administrative process.  Although there may not be tax avoidance motive behind such a structure as the income of holding companies, namely dividend and capital gains, are often not taxed in many jurisdictions, corporates with such offshore holding companies should also be mindful of the issue of tax residency to avoid surprises, because these days tax offices are all trying to tax untaxed income.

    Tax Tips

    As the world is getting more transparent, corporates with Offshore Companies in the group structure should revisit the tax residency of such companies based on each company’s facts and circumstances and the applicable tax rules.  One should note that having established TPMC is not necessarily the end of the risk analysis: the requirement of carrying on business is also relevant in many jurisdictions in determining tax residency. With the information in hand, corporates can decide what to do: make the necessary changes, perform tax filings, or prepare documentation for future defence as appropriate.  No corporate can avoid exposures to tax but by knowing the risks and actively managing them would help win half of the battle. Corporates should review their organisational structures at once.

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 12 July 2018: https://manageyourtax.com/HKEJ Forum 13)

    Ref:

    OECD Model Tax Convention: https://read.oecd-ilibrary.org/taxation/model-tax-convention-on-income-and-on-capital-condensed-version-2017_mtc_cond-2017-en#.WmNWKqiWYdU#page32

    OECD 2014 Model Tax Convention: https://read.oecd-ilibrary.org/taxation/model-tax-convention-on-income-and-on-capital-2015-full-version_9789264239081-en#page192

    ATO TR 2018/5: https://www.ato.gov.au/law/view/document?DocID=TXR/TR20185/NAT/ATO/00001&PiT=99991231235958
  • Tax Tips (12) – Practical Transfer Pricing Strategy for Parental Guarantee

    Tax Tips (12) – Practical Transfer Pricing Strategy for Parental Guarantee

    The rise of globalisation has led to substantial increase in cross-border related party transactions (“RPTs”).  For example, by moving a factory to a foreign country, businesses will be scrutinised by at least two tax jurisdictions on RPTs in purchases, sales, intangibles, financing, management fees, shared services etc. by tax offices in at least two jurisdictions.  Businesses are expected to provide documentation to support the transfer pricing of each RPT. With the BEPS project, the amount of pressure on meeting the tax offices’ expectation on transfer pricing has increased to the highest.

    The OECD, being the major driving force behind BEPS, have updated the OECD Transfer Pricing Guidelines for Multinational Enterprises and Tax Administrations in July 2017 (“TP Guidelines”), which is over 600 pages long, to help reduce possible differences between businesses and tax offices in determining the approach and factors to be considered on what should be the arm’s length price of RPTs.

    This Article is based on the Hornbach case (C-382/16), ruled by the Court of Justice of European Union (“CJEU”) on 31 May 2018 to look at a relatively small, but common, RPT, discusses what issues businesses would face and the takeaways from the case that can help businesses strategize for future RPT of this kind.    

    The Hornbach Case

    Background

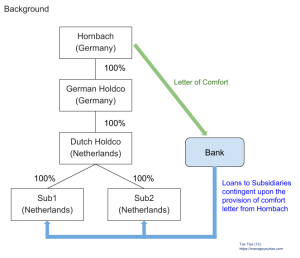
    Hornbach-Baumarkt AG (“Hornbach”) is a public limited company established in Germany which operates do-it-yourself (DIY) and building materials shops in Europe.  In 2003, Hornbach, through a German and a Dutch intermediate holding companies (“German Holdco” and “Dutch Holdco” respectively), held an indirect shareholding of 100% in two operating companies established in the Netherlands, Sub1 and Sub2 (collectively ‘the Subsidiaries”).

    The Subsidiaries had negative equity capital and required, respectively, in order to continue their business operations and to finance the planned construction of a DIY store and garden centre, bank loans of EUR 10,057,000 as regards Sub1 and of EUR 14,800,000 as regards Sub2.


    The financing bank had made the granting of the loans contingent on the provision of comfort letters containing a guarantee statement from Hornbach.  In September 2002, Hornbach provided the comfort letters gratuitously. In the comfort letters, Hornbach undertook vis-à-vis the financing bank to refrain from divesting of or changing its shareholding in the Dutch Holdco and, in addition, undertook to ensure that the Dutch Holdco would likewise refrain from divesting of or changing its shareholding in the Subsidiaries without giving the bank written notice thereof at least three weeks prior to such divestment or change.

    Furthermore, Hornbach irrevocably and unconditionally undertook to fund the Subsidiaries in such a way as to enable them to meet all of their liabilities.  Accordingly, it had to make available those companies, as necessary, the requisite funds to enable them to settle any liabilities towards the funding bank.

    The diagram below illustrates the case background.


    The Dispute

    Taking the view that unrelated third parties, under the same or similar circumstances, would agree on remuneration in exchange for granting the guarantees, the German Tax Office decided that, according to German tax laws, the income of Hornbach had to be increased by an amount corresponding to the presumed amount of the remuneration for the guarantees granted and accordingly amended the corporation tax and the basis of calculation for that company’s business tax for the year 2003.  The Tax Office, therefore, corrected the amount of taxable income of Hornbach as a result of the guarantees granted to Sub1 and Sub2 by EUR 15,253 and EUR 22,447 respectively.

    Hornbach objected to the assessment which was rejected by the German Tax Office.  Hornbach brought an action against those decisions before the German Finance Court.

    In the context of that action, Hornbach argued that the relevant German tax law leads to unequal treatment in cases involving domestic and foreign transactions since, in a case involving purely domestic transactions, no corrections of income would be made in order to reflect the presumed amount of the remuneration for guarantees granted to subsidiaries, which could be regarded as a restriction on freedom of establishment.  In addition, the tax law does not contain any provision concerning the opportunity to present commercial justification in order to explain a non-arm’s-length transaction. In the present case, according to Hornbach, commercial reasons relate to supportive actions to replace the equity capital of the Subsidiaries explain why no remuneration was given for the comfort letters. The Tax Office contended that the taxpayer had the opportunity to present evidence of the reasonableness of the transaction carried out, and the concept of “commercial justification” within the meaning of the relevant tax laws must be interpreted in the light of the principle of free competition which, by its nature, rules out acceptance of economic reasons resulting from the position of the shareholder.

    The German Finance Court was uncertain as to (1) whether the relevant German tax law was compatible with the freedom of establishment, and (2) whether commercial justification may be presented as evidence and, in particular, whether any commercial justification may include economic reasons resulting from the very existence of a relationship of interdependence between the parent company resident in the Member State concerned (Germany) and its subsidiaries which are resident in another Member State (the Netherlands).  

    Consequently, the Finance Court referred the questions to the CJEU for a preliminary ruling.

    The Ruling

    Readers would see that the CJEU was not asked to rule whether the commercial justification presented by Hornbach was sufficient in supporting the alleged “non-arm’s length” transaction.  While CJEU ruled that the German tax law was compatible with the freedom of establishment, and in the case at stake, it is for the German Finance Court to determine whether Hornbach was in a position, without being subject to undue administrative constraints, to put forward elements attesting to a possible commercial justification for the transactions at issue in the main proceedings, without it being precluded that economic reasons resulting from its position as a shareholder of the non-resident company might be taken into account in that regard.  In other words, the relationship between Hornbach and Subsidiaries shall be taken into account in assessing the commercial justification for the non-arm’s length transaction, which was what the German Tax Office refused to do. Therefore, whether Hornbach would eventually win the case is uncertain and it is worth keeping an eye on the development.

    Food for Thoughts

    This case has provided some food for thoughts as to whether a parent company should charge its subsidiary for support, such as the guarantee in this Hornbach case.  Here are some of the key comments from CJEU:

    1. It is clear that Subsidiaries had negative equity capital and the financing bank made the granting of the loans required for the continuation and expansion of business operations contingent on the provision of comfort letters by Hornbach.
    2. In a situation where the expansion of the business operations of a subsidiary requires additional capital due to the fact that it lacks sufficient equity capital, there may be commercial reasons for a parent company to agree to provide capital on non-arm’s-length terms.
    3. Furthermore, it should be noted that, in the present case, no argument relating to the risk of tax avoidance has been advanced.
    4. Accordingly, there may be a commercial justification by virtue of the fact that Hornbach is a shareholder in Subsidiaries, which would justify the conclusion of the transaction at issue in the main proceedings under terms that deviated from arm’s-length terms. Since the continuation and expansion of the business operations of those foreign companies was contingent, due to a lack of sufficient equity capital, upon a provision of capital, the gratuitous granting of comfort letters containing a guarantee statement, even though companies independent from one another would have agreed on remuneration for such guarantees, could be explained by the economic interest of Hornbach itself in the financial success of Subsidiaries, in which it participates through the distribution of profits, as a shareholder, in the financing of those companies.

    These comments would be quite helpful to companies in structuring their transfer pricing strategy and future defense.

    Applications

    It is common for the Ultimate Parent Entity (“UPE”) of a Multinational Enterprise (“MNE”) to provide guarantees to banks for funding to the MNE’s subsidiaries.  Whether the UPE should charge for a guarantee fee or not is often an issue of debate. In the Hornbach case, the German Tax Office obviously considered that Hornbach should have charged a guarantee fee (in this case, the rate appears to be 0.15%p.a. on the loan amount) and therefore adjusted Hornbach’s taxable income upward.  That brings up a few questions for MNEs facing similar situation: (1) when no third party would be in the position to provide the same guarantees, is this really an arm’s length price for the guarantee; (2) can the tax office make adjustment when there is no evidence of tax avoidance; and (3) would the tax office on one side (the Dutch tax office in this case) allow a corresponding deduction for deemed guarantee fee income imposed on the other side (Germany) and how to achieve that?  These are very difficult questions that require tax and legal analysis of the tax laws and tax treaties of the jurisdictions involved at that point in time. MNEs are often less interested in what is the correct technical answers, but more interested in how to resolve the matter in the least expensive manner.

    An arm’s length price is the consideration that unrelated parties would agree upon in the same or similar circumstances (and that is perhaps why the German Tax Office argued that the concept of “commercial justification” within the meaning of the relevant tax laws must be interpreted in the light of the principle of free competition which, by its nature, rules out acceptance of economic reasons resulting from the position of the shareholder).  However, in the Hornbach case and often in real life situations involving parental guarantees, no third parties would be in the position to provide similar guarantees to funding bank because they would not be in the position to guarantee that they would “refrain from divesting of or changing its shareholding” in the Subsidiaries. If there can be no comparables, how does anyone derive an arm’s length price?

    In Chapter 1: The Arm’s Length Principle of the TP Guidelines, Para 1.11. pointed out exactly the issue, “A practical difficulty in applying the arm’s length principle is that associated enterprises may engage in transactions that independent enterprises would not undertake.  Such transactions may not necessarily be motivated by tax avoidance but may occur because in transacting business with each other, members of an MNE group face different commercial circumstances than would independent enterprises. Where independent enterprises seldom undertake transactions of the type entered into by associated enterprises, the arm’s length principle is difficult to apply because there is little or no direct evidence of what conditions would have been established by independent enterprises.  The mere fact that a transaction may not be found between independent parties does not of itself mean that it is not arm’s length.”

    Does the Para 1.11 help?  Not much, because the guidelines is not saying that tax office have to accept whatever the price set by the taxpayers in this situation, even though no arm’s length comparable price can be found and “no adjustment” is probably the right answer.  Therefore, disputes would still arise, as we see in the Hornbach case.

    The Reality

    There are tax and non-tax reasons for MNEs to consider whether to charge a guarantee fee.  In the Hornbach case, Subsidiaries needed funding, which could come from Hornbach in the form of capital or loan via the intermediate holding companies (from internal funds or external borrowing), or from bank borrowing directly by the Subsidiaries as in the present case.  MNEs would need to review the cash flow, cost of capital and follow the internal policies in deciding the choice of funding, especially for larger amounts.

    The reason for not charging a guarantee fee in the Hornbach case was not disclosed.  It could be due to the reason that Subsidiaries may not be able to generate sufficient cash flow to pay the guarantee fee, which could create further funding issue for the group and may therefore incur additional interest expense.

    In some situations, UPE may want to charge a guarantee fee.  For example, the UPE holds a majority stake in the subsidiary and is providing the letter of comfort to the bank funding the subsidiary covering the full amount of the loan, while the minority shareholder (the “MI”) does not need to provide the proportionate guarantee.  The MI would therefore be enjoying a free ride in terms of the subsidiary obtaining the bank loan, often at an interest rate lower than if it was borrowing on a standalone basis, and thus the MI would eventually receive a higher return on investment while the risk is borne by the UPE alone.  In this situation, the UPE would often want to charge a guarantee fee to the subsidiary to eliminate this free ride.

    The UPE may also charge a guarantee fee if overall tax savings of the group could be created, after taking into account the tax deduction benefit of the subsidiary, withholding tax that may be imposed, and the income tax that the UPE may be subject to after considering the tax credit available on the withholding tax paid.  MNEs should fully recognise the BEPS risks for taking such approach.

    Tax Tips

    In tax jurisdictions where there are statutory transfer pricing requirements (which will include Hong Kong soon), in deciding whether to charge a guarantee fee to the subsidiary when parent guarantee is provided, the thought process should cover the following:

    1. Consider from purely commercial perspective whether there is a preference for charging or not charging a guarantee fee.  This preference is the best defense against tax avoidance accusation.
    2. Consider the tax implications of charging and not charging, including local practices, tax treaty applications, case law and compliance costs, and assess the risk of the two alternatives.
    3. Determine the approach based on commercial preference, costs, benefits and risks analysis.
    4. Prepare all necessary supporting documentations (e.g. board minutes, communication with external parties such as banks, loan agreements, guarantee fee agreement and transfer pricing reports) which must include the commercial rationale of the approach taken.

    One of the significance of the Hornbach case is the CJEU comment that the parent-subsidiary relationship could justify terms that deviated from arm’s-length terms.  Indeed, only the parent company would provide guarantees to banks for financing its subsidiaries, especially at the early development stage of the subsidiaries when banks refuse to lend without a parental guarantee.  Such action should be regarded as an investment activity instead of a service. The parent, by providing the guarantee, can earn its return by sharing the future profits of the subsidiary, in just the same way as providing capital to fulfil the funding need.  Unfortunately, many tax offices view guarantee as a service, however it arises. Therefore a risk assessment is needed on the attitude of the tax office involved when the UPE decides not to charge a guarantee fee.

    Notwithstanding, the underlying nature of the guarantee could change to service when the subsidiary is capable of obtaining standalone financing (i.e. banks would be willing to lend to the subsidiary directly without parental guarantees), and the parental guarantee is provided for the purpose of reducing the financing costs of the subsidiary because banks would lend cheaper due to the lower risks.  As the subsidiary would be truly benefiting from the guarantee, it may justify the charging of a guarantee fee from tax perspective.

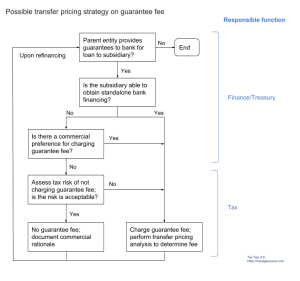
    Along the lines discussed above, MNEs may consider the following transfer pricing strategy on guarantee fees:

    The above strategy would help MNEs make decision on whether to charge a guarantee fee.  One should note that this may not necessarily be agreed by the tax office. If it is decided that a guarantee fee should be charged, finding the so-called arm’s length amount is another challenge, especially when no third party would enter into the same or similar transaction, as in the Hornbach case.   For small amount of adjustments, the cost and administrative burden of searching the right amount is sometimes unproportionately high. If the method of how the German Tax Office derive the guarantee fee of 0.15%p.a. would be disclosed, it would be of good reference to many MNEs.

    The problem with transfer pricing in practice is that there are many assumptions in the whole process, and the tax offices often do not understand the commercial rationale behind and they go after companies just because they smell revenue.  After lodging objections which the tax offices have rejected, in practice companies would not go to the court in view of the cost and benefits, and may instead restructure the transactions to make the issue go away. It is not often that the taxpayer, like Hornbach in this case, would go to the court for the relatively small amount of tax involved, and those who seek fair treatment deserve much appreciation and applause from people who are concerned.  

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 14 June 2018: https://manageyourtax.com/HKEJ Forum 12)

    Ref:

    The Case: http://curia.europa.eu/juris/document/document_print.jsf?doclang=EN&text=&pageIndex=0&part=1&mode=DOC&docid=202410&occ=first&dir=&cid=701953#Footnote*

    OECD TP Guidelines:

    https://read.oecd-ilibrary.org/taxation/oecd-transfer-pricing-guidelines-for-multinational-enterprises-and-tax-administrations-2017_tpg-2017-en#page327

  • Tax Tips (11) – Merger & Acquisition – A Chinese Case Study

    Tax Tips (11) – Merger & Acquisition – A Chinese Case Study

    A Chinese merger & acquisition case with an eye-catching title has recently been reported on WeChat – “Tax Office Analysed Enterprise Group Packaged Transfer – ChangChun State Tax Bureau Solved the Difficult BEPS Question Posed by Packaged Share Transfer Using Tax Haven”.  The Article stated that the source is from the ChangChun State Tax Bureau. The taxpayer was assessed additional Corporate Income Tax (“CIT”) of RMB 2.22million plus interest of RMB 310,000.  Although not many details were provided in the Article, there are a few takeaway points that may be helpful to the readers.

    Summary of the Article

    Case Background

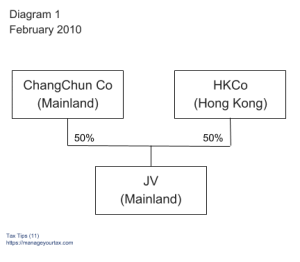
    In February 2010, the Chinese Party, a ChangChun Company, formed a 50/50 Sino-Foreign Equity Joint Venture (“JV”) in ChangChun with a Hong Kong Company (“HKCo”) for the manufacture and sale of electronic products and parts of motor vehicles and other products.  The shareholding structure is as follows:

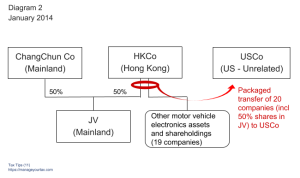
    In January 2014, HKCo signed a Sale and Purchase Agreement (“SPA”) with a US company (“USCo”) to transfer its shares in the JV and other assets and shareholdings in companies related to motor vehicle electronic business to the USCo.   The disposal was packaged deal involving shareholdings in 20 companies. The USCo replaced HKCo as the 50% shareholder of the JV, as below:

    There was only one SPA covering the packaged transfer (including the 20 companies).  As this was a direct transfer of a Mainland entity, ChangChun tax bureau had the taxing right on the gains derived by HKCo on the JV share transfer.  CIT filing was made on the JV share transfer on the basis of No-Gain-No-Loss.

    Applicable Regulations

    The share transfer was subject to Circular GuoShuiHan (2009) 698, which stated that when the foreign investor (actual controlling party) transfers shareholdings in companies located both inside and outside of China, the companies in China shall provide the SPA of the packaged transfer and the SPA for the transfer of each Chinese company to the in-charge tax bureau.  If no separate SPA is available, the companies in China shall provide detailed information about each company being transferred, in order to precisely segregate the consideration of the transfer of each company involved. If it is not possible to precisely segregate the consideration, the in-charge tax bureau may adopt the reasonable method to adjust the transfer price.

    The Investigation

    The ChangChun tax bureau investigated the case and issued the “Notice on Tax Matters” to the JV requesting various information including: shareholding structure chart of the JV pre- and post-transfer, a report on the deal, method in determining the consideration, the SPA, separate SPAs for the individual companies, detailed information of each company included in the transfer, a chart showing the allocation of the consideration to each company transferred, the balance sheets, profit and loss accounts and cash flow statements of the JV for the previous 5 years, the medium-long term budget plan of the JV prepared in the year immediately before the share transfer, and an explanation of the commercial reasons for the packaged share transfer by the foreign investor.

    Through consolidating and analysing the information provided and conducting interviews, the tax investigation team found the following facts: (1) HKCo and USCo were unrelated parties, the deal was conducted at arm’s length, and there were commercial reasons for the packaged share transfer; (2) before the deal, the financial position, operating results and cash flow of the JV were satisfactory, there were no special circumstances that would prevent the JV from continued operation, and the future prospect was positive, such that there was a risk that the No-Gain-No-Loss filing position adopted by the JV would understate the value of the company and thus posed a tax risk; (3) as there were no separate SPAs for the companies being transferred and no detailed information on the other 19 companies were provided, it was not possible to determine the value of the JV through an allocation of the deal transfer price; (4) the packaged transfer had in effect created the situation where gains from the transfer of individual companies would not be realised in the jurisdictions where they were located, and with the gains booked by the HKCo in Hong Kong, resulted in the actual utilisation of the benefits of a tax haven.

    Additional Tax Assessment

    After detailed investigation and rounds of negotiations, as HKCo did not provide separate SPAs or detailed information of the companies transferred, it was agreed that the consideration for the transfer of the JV shall be adjusted based on a reasonable methodology.  The taxpayer and the tax bureau agreed to perform a valuation on the JV. The Market Approach was rejected on the basis that there was no sufficient market data available, and since the JV was at a stage of healthy development, the Cost Approach (Asset-based Approach) was considered inappropriate.  The two sides agreed to adopt the Income Approach. The JV was accordingly valued at RMB 161,169,400, and the gain on 100% share transfer would be RMB44,361,244. The 50% share being transferred would result in a gain of RMB22,180,622元, and the additional CIT of RMB 2.22 million plus interest of RMB310,000 were assessed.

    Our Comments

    In this particular case, the Mainland tax office has all the rights to assess income tax on gains derived from the transfer of the JV alone (although the background facts have not mentioned, it seems likely that the other 19 companies sold were not Mainland entities).  To determine the standalone value of the JV, the Income Approach is generally adopted and is widely applied in China in similar situations. The discount rate and other assumptions would have a significant impact on the tax liability, and the discussion with tax office could drag on.  Depending on the stage of discussion, taxpayers may need to consider the interest costs, if applicable, against the benefits of standing firm on their negotiation position.

    Package sale is very common and there are good reasons for the acquirer to buy the lot.  There could be various contractual relationships with external as well as internal parties established, banking covenants, employees, licences, regulatory concerns etc.  If there are companies that the buyer does not want to acquire, those companies would be carved out. The transaction value must, therefore, reflect the combined value of the Group acquired from the Buyer’s perspective.  There may not even be a deal if the acquirer is only allowed to buy one particular company of the target group.

    The question, therefore, is how to factor-in the group value into the pricing of the entity that is subject to tax on share transfer (the JV in this case).  The JV was not sold on a standalone basis. One could argue that the assessment of income tax on the sale of JV based on a standalone sale model is not reflecting the arm’s situation.  Notwithstanding, as the Seller did not provide information on the 19 companies sold to the Mainland tax office, it is not unreasonable for the tax office to ignore the 19 companies and assess tax on the JV disposal based on the stand-alone valuation of the JV as in this case.  The fact that the Seller filed the tax return on the JV disposal on a No-Gain-No-Loss basis probably reflected that the other 19 companies might not be performing well, and some might even be loss-making.

    The tax on disposal is payable by the Seller.  It is therefore very important for the Seller to correctly assess the tax impact of the transaction before the deal is closed.  Filing the tax return of the JV disposal in this case on the basis of No-Gain-No-Loss would be a somewhat aggressive position to take if the JV is making a profit.  If the Seller genuinely believed that the tax office would accept the filing position, he was probably ill-advised, which cost him RMB 310,000 of interests.

    Tax Tips

    Some helpful tips can be drawn from this case.

    Seller – In a merger & acquisition deal, the Seller is often the party responsible for reporting for tax in jurisdictions where the transaction would be taxable.  The Seller should, therefore, consult with tax advisors to understand the obligations, exposure, and formulate a strategy to manage the tax filing obligations and position.  In the JV case above, other than preparing for the worse case scenario, the advisor should be creative in coming up with arguments of why the deemed disposal price of the JV is less than what the tax office would like to assess.

    For example, these days the tax offices around the world are keen on reviewing the value-chain of the group and split up the taxable profits accordingly.  Would it be possible to perform a similar analysis on the target group and allocate the deal price to each company (or jurisdiction) according to their value contribution, and put the numbers down onto SPA?  Maybe a non-Mainland entity of the group holds intellectual property rights and thus a larger portion of the value should be allocated to it, and thereby reducing the taxable profits of the JV? Thinking-out-of-the-box is just the starting point, establishing convincing arguments and provide solid supporting including contracts and analysis are the keys to success.  Obviously, the taxpayer has to be careful in whether such analysis would create issues for the past, present, and future tax filings in different parts of the world.

    Buyer – The Buyer would also have a vested interest in how much tax the Seller is to pay even after the deal is closed.  Why? The deemed disposal value assessed by the tax office could become the stepped-up cost-base of the company acquired.  In the future disposal of the same company, the Buyer would deduct the stepped-up cost-base of RMB 80,584,700 (50% of RMB161,169,400).  In theory, the more tax the Buyer pays now, the less tax that the Seller would pay in the future.

    In the case of an indirect disposal involving Mainland entities, the Buyer may even have a withholding obligation on the tax that they Seller may need to pay under Public Notice 2015 No.7.  The two sides must agree on action to be taken for completing the tax filing obligations. For indirect transfer case, even though the Buyer has no plan of disposal of the acquired companies in the foreseeable future, he should closely follow up with the Seller and obtain copies of the relevant tax filing records as soon as possible for two purposes: (1) be sure that the tax withholding obligation is no longer applicable; and (2) substantiate the cost-base of the Mainland company acquired.

    Finally, it is interesting to note that the Article mentioned that “the packaged share deal transferred the gains to a tax haven, and avoided the reporting of tax at the location of the group entities”.  According to the Article, Hong Kong is a tax haven, which is something that almost no Hong Kong taxpayer would agree. It reflects that some misunderstanding still exists between Hong Kong and the Mainland.  Such misunderstanding would increase the challenges that Hong Kong taxpayers face when they negotiate with the Mainland tax authorities in a situation similar to this JV case. Also, in this particular case, as it is a Hong Kong company directly disposing of the equity in a Mainland enterprise, it is difficult to understand why there are BEPS concerns as mentioned in the Article.  Given the mindset of the Mainland tax office as demonstrated in the Article, taxpayers should be prepared to fight the uphill battle in any tax negotiation.

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 28 May 2018: https://manageyourtax.com/HKEJ Forum 11)

    Ref: The Article (in Chinese only):

    https://mp.weixin.qq.com/s/clQRKlNO6CyTWW2SmuIygQ

  • Tax Tips (10) – Are you sleeping well at night?

    Tax Tips (10) – Are you sleeping well at night?

    Tax Management

    Rest assured, this article is not about tips on sleeping well…it is about something that could keep the CFO awake at night: is your company’s tax affairs being well-managed?  The problem with poor tax management is that you often realise it too late. It happens because the company has not been targeted by the tax office, management does not realise the danger ahead and does not want to dig up issues, and the Board of Directors has no idea about tax management.

    What leads to this hazardous situation? The common reasons include: people in the past took bad tax advice, did not implement structure and arrangement properly, no documentation exists to support the story, no one was aware of tax law changes so that tax returns were filed incorrectly etc. All these could lead to under accrual of tax liabilities and, more painfully, the heavy interest and penalties. Even worse is reputational damage, as tax offices around the world like the “name and shame” game.

    When you search on the Internet on “tax management”, what you often find are topics that are either basic focusing on tax compliance or about technology which is somewhat disconnected with the real situation in Asia. For example, collecting tax data would be relatively important in countries like the United States, where companies pay State Income Taxes, Sales Tax and various fees at different rates in different States. Country-by-Country Reporting is another area where technology can help, except that companies could run into difficulties when different accounting systems are used in the organisation.

    More and more people talk about “tax strategy” these days, especially when governments, such as the UK, requested large organisations to publish their tax strategies or face a penalty. In practice, tax strategy is really just the organisation’s risk appetite on tax matters. If management of an organisation realises tax is a risk that needs to be managed, the organisation will then need to actively manage its tax affairs. The key is “HOW”.

    This article discusses what is tax management, how to manage tax and who should be the tax manager, based on my own experience.

    What is tax management

    Tax management is to protect the company’s balance sheet and ensure that there are no surprises.

    How to manage tax

    There are five building blocks to successful tax management:

    1. Tax returns are filed correctly and on time
    2. Identify the right tax advisors
    3. Tax implications of new transactions are analysed
    4. Tax matters are discussed regularly with C-suites and internal functions
    5. No harmful documentations exist

    Sounds simple but it is almost an art, and certainly requires experience, deep thoughts and good communications, in making sure that these simple matters are executed right. For the ease of discussion, we call the person responsible the tax manager (who can be the finance manager or a dedicated tax manager).

    Filing tax returns correctly and on time

    There are three things the tax manager needs to do.

    First: Assign Responsibilities. Responsibilities for preparation and review of different kinds of tax filings shall be assigned. Hong Kong would be simple but when we are talking about other jurisdictions, the number of tax returns and documentations required would be of multiple folds. In some jurisdictions such as Indonesia, just for payment to overseas vendors, one would need to collect the applicable Tax Resident Certificates of the vendors, calculate and withhold the correct amount of tax, arrange the necessary treaty benefit claim forms (the infamous DGT-1 Form). Staying with Indonesia, certain payments to local vendors are subject to tax withholding, and on top of that, there is VAT…we have not even touched on the corporate income tax filing and transfer pricing documentation.

    Second: Staff Training. It is worth spending some training costs and time to ensure the staff responsible understand the importance of their job and where to find help. The staff need to be updated on tax law changes, tax audit trend, and maybe the outcome of recent tax cases by attending tax seminars. The tax manager himself has to be trained as well, on the latest tax rules in jurisdictions covered and keep himself up to date with tax development on a macro level.

    Third: Process Design. The tax manager needs to design and put in place a seamless process such that all the different elements of every tax filing: preparation of tax return, data collection, documentation of tax position taken, review, submission, payment and keeping files would work like clockwork.

    It is not necessary for the tax manager to review the actual tax returns, especially those related to jurisdictions outside of the home base) because he does not have the local tax knowledge or even the language skills. If the tax manager is responsible for signing-off the tax returns, it may cause a moral hazard, as the local team may take their job less seriously. The tax manager will also need to decide, by working with the local team, the involvement of external tax advisors in the process. Typically, they create most value in terms of tax training and perhaps review or even prepare the more important tax returns.

    Would technology help? From experience, full automation in tax return preparation is almost not possible except for VAT, when the local rules require that the company’s invoicing system is linked to the tax office’s system. For the other tax returns, there is often a high degree of judgement involved on what is taxable/non-taxable and deductible/non-deductible, and thus the establishment of a real-time dashboard on tax reporting status should not be on top of the priority list of a tax manager. The key to managing tax risk is to do the above three things right, and the tax manager monitors the situation from time to time. Once the basic compliance mechanism is in place, the tax manager may investigate investing in automatic VAT reconciliation.

    Identify the right tax advisors

    This can actually be the hardest part of the job. There are many tax advisors in the big and small firms, as well as sole-proprietor type consultants. How to identify the right ones to advise the company can be a challenge.

    One needs to cast a net to catch the big fish. The tax manager should network with different advisors by attending tax seminars and social events held by the firms and professional organisations such as the local accounting or taxation institute, and make use of the Q&A sessions to ask questions to test their response and reaction. To be able to do that, however, the tax manager has to be reasonably experienced and possess good technical skills.

    In some developing countries, the quality of tax advisors can be appalling. To properly manage the tax issues, the level of experience and technical skills required on the tax manager would actually be higher, so that the tax manager can lead the advisor into providing the advice needed.

    For companies that operate in Mainland China, they need to be aware of the State Administration of Taxation’s Public Notice on the Supervisory Rules on Tax-Related Professional Services (Public Notice 2017 No.13, “PN13”). Under PN13, which became effective on 1 September 2017, only professional service firms with the Mainland-recognised qualifications are allowed to provide professional tax advisory and planning services, and they shall inform the tax authorities on “the relevant information”. Tax advice, memos or reports issued may need to be submitted to the tax authorities.

    Tax implications of new transactions are analysed

    “New transactions” can be any transaction with related or unrelated parties involving new jurisdictions, new business, service, intellectual properties or even M&A transaction.

    To properly manage the tax implications, the first thing to do is to understand the business objective and rationale, timing, preliminary information on contract terms, cash flow, accounting implications, capital and financing structure and degree of confidentiality. With the information, the tax manager can consult external tax advisors for tax implications and possible tax planning ideas. The process could last from weeks to months before the tax advice is finalised, thus having a good idea on timing and deadline is crucial. The tax manager must keep close contact with the functional teams (finance/legal/IT/Business Development/Company Secretarial etc) involved to learn the latest on the transaction and respond accordingly to ensure the tax advice is correct and relevant.

    It is very important for the tax manager to possess the business acumen and project management skills to really manage the process, which includes:

    • Narrow down the options to arrive at an executable transaction structure that supports the business objective
    • The advice has to be technically strong
    • Understand the tax advice and work with other functional teams to ascertain feasibility and timing of execution
    • Ensure the documentation are properly worded, executed (including the location of execution) and maintained
    • If new companies are to be set up, ample time should be allowed and proper board meetings should be held; in some countries, investments in certain industries require government pre-approval (e.g. the Foreign Investment Review Board in Australia)
    • Know where to, and where not to, take short-cuts
    • Keep senior management informed on progress and hurdles, if any, and seek direction where appropriate

    Tax matters are discussed regularly with C-suites and internal functions

    Tax expense is often one of the largest expenditure after salaries/wages and rent. However, as the amount is so-called “below the line” (i.e. below EBIT, which is the common performance measurement metric), and it is considered a somewhat less-controllable expense, management tends to pay less attention to it. With the rapidly changing tax rules and the tax offices’ increasingly hostile attitude towards taxpayers, it is important for the tax manager to bring tax matters to the attention of the C-suites and internal functions, which indeed is part of the expectation management: ensure that there are no surprises.

    Such discussions should include uploads and downloads: the tax manager provides the appropriate tax update on issues, disputes, law changes, project status etc to the management (upload), and obtain information from the team about new business direction and projects (download) so that the manager can raise the tax concerns on-the-spot, where applicable, to the management, which is often the most valuable part of the job. Direct participation in such meetings would help raise awareness of tax, making the tax manager part of the team, which will be beneficial in carrying out future tax projects.

    No harmful documentations exist

    What is meant by “harmful” documentation?

    Anyone who has been involved in tax planning would likely have come across discussions on “how much is the tax saving?”, which, to many, is the most exciting part of the project. People involved, including the external tax advisors, easily get carried away and start to communicate in writing (typically by email, and sometimes by instant messaging nowadays) about the tax saving, which would then be spread across the organisation, and sometimes across countries, at the speed of light. They forgot that tax offices would love to see these as evidence of tax-avoidance and they indeed have the power to ask for all emails or even confiscate the computers of taxpayers in dawn raids. Email has become an important evidence for taxpayers to prove their intention. For example, under the Administrative Measures for General Anti-avoidance Rules issued by the State Administration of Taxation in Mainland China (Order No.32) in 2014, Article 11 stated that in an investigation related to General Anti-avoidance, the taxpayers who wish to defend themselves shall provide correspondences related to internal decision and management such as board minutes, memorandums and emails to the tax office. If taxpayers cannot provide such documents or the correspondences contain harmful wordings, the best thing that the taxpayer could hope for is a reasonable settlement with the tax office.

    Governments are also trying to hold external tax advisors responsible for providing aggressive tax advice. Under Article 14 and 15 of the Order No.32, for example, the Mainland tax office could issue information demand notices to parties involved in tax planning, which include the external tax advisors, and the tax office is empowered to reach out to overseas tax jurisdictions for help to collect the relevant information if the evidence is located offshore. Order No.32 and PN13 mentioned earlier would give the Mainland tax office all the powers to obtain documentations in investigation tax avoidance.

    Who should be the tax manager?

    Most people would answer: “it depends on the size and complexity of the organisation…for smaller organisations, the CFO or finance manager can take up such a role…for larger organisations, a full-time tax manager may be needed”.

    The answer is correct subject to two caveats: (1) the scale of operations of the “smaller organisation” would likely be organisations that have simple business and perhaps operate in not more than three jurisdictions; (2) the person taking up the tax manager role has the time, and the ability, to do all the things discussed above in order to properly manage the tax for the organisation, large or small.

    For the “smaller organisations” that are growing to become medium-sized and are beginning to realise the value of professional tax management, they should start considering hiring a full-time tax manager. As this is going to be a new headcount, the company may find budget constraints thus it may be harder to hire experienced tax managers. If the company hires someone directly from the accounting firms, that person needs to be properly trained, and be guided continuously, in order to perform the role of tax management. Who in the organisation is qualified, and has the time, to be the trainer-supervisor?

    These medium-sized organisations should instead consider hiring experienced tax professionals who have years of experience in commercial organisations on a part-time basis. There are multiple benefits of hiring experienced part-time tax managers: (1) they know how to manage your tax; (2) no training and supervision are needed – they hit-the-ground-running; (3) they know how to work with other functions within the organisation; (4) they know the tax advisors and can identify the right ones for different countries or projects.  Our company, Manage Your Tax Company Limited, provides such part-time tax management services in Hong Kong.  The services are provided under a service contract so that the client would not need to be bothered with issues and costs associated with hiring employees, and can dedicate more time to developing the business. If the organisation’s tax workload does not justify hiring a full-time tax manager, then employing a part-time tax manager would be a win-win for everyone.

    What about tax planning?

    The days that external tax advisors selling tax planning packages out of thin-air have long gone. That doesn’t mean that tax planning is dead. Nowadays, tax planning has to be driven from within the organisation, by the tax manager, and there are two situations where tax savings can be created.

    One is when tax implications of new transactions are analysed, as discussed above. Two is based on the tax manager’s sharp eyes and his/her thorough understanding of the organisational structure, business model and transaction flows, tax planning opportunities could be spotted. The key to successful tax planning is that there has to be a business driven transaction behind it. Experienced tax managers should know that well.

    Conclusion

    Tax management (or tax risk management) is not about talking fancy words such as “strategy”, “technology”, “vision”, “KPI for tax function”, “tax data” etc. What companies need are experienced tax professionals who understand business, can implement processes, technically strong, constantly looking for value-creation, know where are the risks area and deal with them, able to spot opportunities, and can make practical decisions. Knowing that tax is under good management, the CFO can sleep well every night.

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 10 May 2018: https://manageyourtax.com/HKEJ Forum 10)

    Ref:

    Order No.32: http://hd.chinatax.gov.cn/guoshui/action/GetArticleView1.do?id=483630&flag=1

    PN13:

    http://hd.chinatax.gov.cn/guoshui/action/GetArticleView1.do?id=5745825&flag=1

    http://www.chinatax.gov.cn/n810341/n810755/c2608065/content.html


  • Tax Tips (9) – New Beneficial Ownership Rules in China…LOB in Disguise

    Tax Tips (9) – New Beneficial Ownership Rules in China…LOB in Disguise

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 9 April 2018: https://manageyourtax.com/HKEJ Forum 9)

    [Tax Tips (7) and (8) are pre-reads of this article, which cover Treaty Shopping, Model Tax Convention, Multilateral Convention, Limitation-on-Benefits (“LOB”), Principal Purposes Test (“PPT”), Beneficial Ownership, Cir 601, PN30, Cir 165 and PN60.]


    On 3 February 2018, the State Administration of Taxation (“SAT”) of Mainland China issued the “Public Notice Relating to “Beneficial Owner” Under Tax Treaties” (Public Notice 2018 No.9, “PN9”) and its Explanatory Notes (“The Notes”) which is applicable to tax treaty benefit claims on tax obligations arising on or after 1 April 2018.  PN9 superseded Cir 601 and PN30, but is silent on Cir 165.  On the face of it, PN9 reduced the number of Unfavourable Factors compared with Cir 601 (there are now three Unfavourable Factors in relation to dividend income) and expanded the Safe-harbour Rules.  However, is it now easier or harder in obtaining benefit claims under Double Tax Treaties or Arrangements (collectively referred to as “DTA”)?  This Article first elaborates the key provisions of PN9 and the Notes, and then discusses how it will affect Hong Kong enterprises earning dividend income from investments in the Mainland.  The conclusion is: it will be very very hard to obtain treaty benefits in the Mainland.

    1.     Key Provisions of PN9 and the Notes

    1.1   PN9 Article 1 – Definition of Beneficial Owner

    Article 1 of PN9 has retained Article 1 of Cir 601: “The term “Beneficial Owner” refers to a person who has both the ownership and right of control over the income or the assets or rights generating the income”, which is basically in-line with the OECD interpretation under the Model Tax Convention.  The requirement to consider “substance over form”, as stated in Article 2 of Cir 601, cannot be found in PN9.

    1.2   PN9 Article 2 – Unfavourable Factors

    Article 2 of PN9 sets out five factors, which, if matched with the circumstances of the applicant of DTA benefit claim (the “Applicant”), would be unfavourable to the determination of the Applicant’s qualification as the Beneficial Owner (hence they are called the “Unfavourable Factors”).  Three of these factors relate to dividend income:

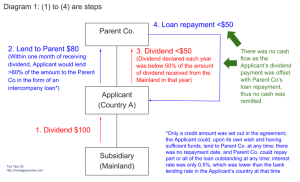
    1.2.1  Unfavourable Factor (1): “The Applicant has the obligation to pay more than 50% of the income within 12 months of receipt to a third-country (region) tax resident; “obligation” shall include contractual obligation as well as constructive obligation based on factual circumstances”.  The Notes provided a case study to demonstrate what is meant by “obligation”.  Please see Diagram 1 below for an illustration of the case:

    The Notes pointed out that the fact pattern above matches with the provision that “the Applicant has the obligation to pay more than 50% of the income within 12 months of receipt to a third-country (region) tax resident”, and thus would be very unfavourable to the Applicant’s claim as the Beneficial Owner.  The Author suspects that the viewpoint expressed by the SAT is, to some extent, a result of the artificial nature of the arrangement for circumventing Unfavourable Factor No.1 of Cir 601, because:

    1. The arrangement of lending and repaying is not considered to be conducted at arm’s length
    2. The amount of dividend distributed by the Applicant is just under 60% of the dividend income, which is just below the threshold set out in Cir 601’s Unfavourable Factor No.1
    3. The Applicant may have been carrying out the same process on a recurring basis for some time

    The Notes did not say whether the Applicant in the case had both the ownership and right of control over the income or the assets or rights generating the income.  If the Applicant had been actively reviewing the investment, had board meetings to decide the possible use of the funds received, and concluded that the best use of the funds was to lend to Parent Co for interest rate higher than leaving the cash idle in the bank, would the SAT’s view be different?  Since the Notes did not elaborate on the SAT’s thinking, in the future when a local tax bureau deal with a case with similar features, it is possible that the tax bureau may not review other facts and deem that the Applicant has the “obligation” simply because the Applicant has remitted more than 50% of its income to a third-country within 12 months, and deny the Beneficial Ownership status as a result.  

    1.2.2  Unfavourable Factor (2): “The Applicant does not carry out substantive business activities.  Substantive business activities shall include activities such as substantive manufacturing, trading, management etc.  The assessment on substantiveness shall be made based on the risks assumed and functions performed by the Applicant. Substantive activities in investment holding management would also be regarded as substantive business activities; Applicants who are engaged in non-substantive investment holding activities and are carrying out other insignificant business activities at the same time would not be considered as carrying out substantive business activities”.  The Notes pointed out that in assessing the substantiveness of the Applicant’s business activities, attention should be paid to matters such as: whether the Applicant owns assets and has employees that match with the scale of its functions, and whether the Applicant bears the risks on the income and the assets or rights that generate the income.  These two points look similar to Cir 601 Unfavourable Factors (3) and (4), but by comparing the two documents carefully one would be able to spot the subtle and important differences which are advantageous to the Applicant. However, as these points are not standalone Unfavourable Factors, Applicants would unlikely be able to win their cases based on them alone.

    PN9 has adopted the viewpoint in Cir 165 that “investment activities should be regarded as business activities”.  According to the Notes, in order to qualify as substantive business activities, the investment holding activities shall involve the actual performance of functions and assumption of risks, and include activities such as pre-investment feasibility studies, assessment and analysis, investment decision making, implementation of investment project and continuous investment management.  A number of case studies were set out in the Notes to explain what kind of investment activities would be regarded as substantive. A simple conclusion can be drawn: if the Applicant is an SPV (Special Purpose Vehicle – an entity set up for a specific project such as acting as holding company of a particular investment) it is unlikely that the investment activities would be considered substantive.   

    In addition, some companies have in the past tried to circumvent Cir 601 Unfavourable Factor (2), “the Applicant does not or barely engages in other operating activities”, by adding functions to the holding company such as procurement or consulting services for other group companies.  The Notes used examples to clarify that if the Applicant is not able to substantiate the commercial reasons for such activities, and the income earned from such other business activities is “only 8%” of the total income (including income earned from Mainland China), the other business activities would be considered insignificant and thus would not constitute substantial business activities.

    Lastly, the Notes did not elaborate whether the Applicants in the various examples had both ownership and right of control over the income or the assets or rights generating the income.

    1.2.3  Unfavourable Factor (3): “The income is not taxable or is exempt from tax, or is taxable but subject to extremely low actual tax rate, in the Contracting State (Region)”.  PN9 retained the Unfavourable Factor (5) of Cir 601, and the Notes did not make any further elaboration on this item.  The factor itself is easy to understand and, unfortunately for Hong Kong taxpayers, is a factor that is almost certain for any Hong Kong companies to meet.  This Unfavourable Factor clearly has no relationship with ownership and right of control over the income or the assets or rights generating the income.

    1.3    PN9 Article 3 – “Replacement Beneficial Owner”

    Article 3 of PN9 provided two situations that would allow Applicants who would not be regarded as Beneficial Owner to be deemed as being qualified:

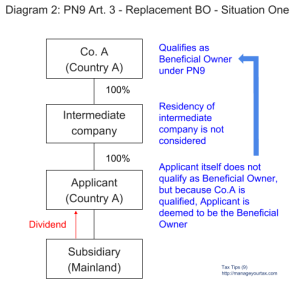
    1.3.1  Situation One: Applicant is directly or indirectly 100% held by another person (Company A, “Co A”) which is a tax resident of the same country as the Applicant, and Co A is qualified as a Beneficial Owner under Article 2 (the Author names it “Replacement Beneficial Owner”).  The tax residencies of the intermediate companies between Co A and the Applicant is not relevant. The Notes provided Structures (4) and (5) to assist taxpayers’ understanding. Diagram 2 below is an attempt by the Author to illustrate the salient points:

    Readers should note that, according to Article 8 of PN9, Co A and the Applicant are both required to provide their respective Tax Resident Certificates.

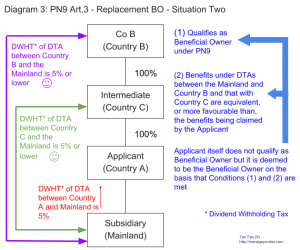
    1.3.2  Situation Two: Applicant is directly or indirectly 100% held by another person (Company B, “Co B”) who meets the Beneficial Owner status (the “Replacement Beneficial Owner”) and Co B, as well as all intermediate companies in between, are tax residents of countries which, under the respective DTAs with the Mainland, would be entitled to benefits which are equivalent to, or more favourable than, benefits to be accorded to the DTA between the Applicant’s State and the Mainland.  The Notes provided Structure (6) as an example to illustrate the concept. Diagram 3 below is an attempt by the Author to illustrate the salient points:

    It is important to note that, according to Article 8 of PN9, Co B, the Intermediate and the Applicant are all required to provide their respective Tax Resident Certificates.

    1.4    PN9 Article 4 – Safe-harbour Rule

    The Safe-harbour Rule is a combination of the relevant provisions in PN30 and Cir 165.  The difference with Article 3 is that provided the Applicant or the holding structure above it meets the prescribed criteria, the Applicant is deemed to be the Beneficial Owner, and no analysis under Article 2 is required.  The following kinds of Applicant would meet the Safe-harbour Rule:

    (1) The Contracting Jurisdiction;

    (2) A company that is a resident of the Contracting Jurisdiction and is listed on the stock exchange of that jurisdiction;

    (3) An individual resident of the Contracting Jurisdiction;

    (4) The Applicant is directly or indirectly 100% held by one or more of the persons listed in (1) to (3) above, and for indirect holding relationship, all intermediate holding companies are tax residents of the Mainland China or the Contracting Jurisdiction.

    According to Article 8 of PN9, those who qualify under (4) above are required to provide the Tax Resident Certificates of all entities in the vertical holding chain.

    The Notes provided sample structures (1), (2) and (3) to help taxpayers understand the concept.

    1.5    PN9 Article 5 – Holding Period

    This Article stated that the shareholding requirements in Article 3 and 4 refer to continuously meeting the shareholding percentage for 12 months prior to payment of dividend.

    1.6    PN9 Article 10 – Anti-avoidance

    This Article stated that even if the Applicant is qualified as the Beneficial Owner, the in-charge tax bureau may apply the relevant anti-avoidance rules if it is discovered that PPT under the DTA or domestic general anti-avoidance rules would be applicable.  

    2.      Commentary

    2.1    Unfavourable Factors

    Article 1 of PN9 stated clearly that a Beneficial Owner is a person who has both the ownership and right of control over the income or the assets or rights generating the income.  According to the Para 12.3 of the Commentary to Article 10 Dividend of the Model Tax Convention, where the recipient of a dividend does have the right to use and enjoy the dividend unconstrained by a contractual or legal obligation to pass on the payment received to another person (thus having “the ownership and right of control over the income or the assets or rights generating the income”), the recipient is the “beneficial owner” of the dividend.  No guideline has been provided at all in the three Unfavourable Factors and the example provided in the Notes as to what constitute the evidence and characteristics of “ownership and right of control of dividend” to help tax bureaus and Applicants determine if the Applicant is the Beneficial Owner.

    In the examples/cases provided in the Notes, the Applicants that are not considered to be the Beneficial Owner all possess the characteristics of the classic SPV.  Take Unfavourable Factor (1) as an example, it is normal commercial operations for an SPV to distribute the dividend income received from its subsidiary in the Mainland to its parent company (assume that it is located in a third jurisdiction) so that the funds can be deployed more efficiently.  If the SPV does not make distribution, cash will be sitting in the SPV’s bank account, which the tax bureau may argue to be an unfavourable fact because the example provided in the Notes on Unfavourable Factor (2) mentioned that “when income is idle in the account with no immediate plan for investment”, it would be viewed negatively in the Beneficial Ownership assessment.  Lastly, if the Applicant is a Hong Kong resident, since Hong Kong does not tax dividend, Unfavourable Factor (3) will be applicable.

    Take a hypothetical case (refer to as “Case X”): A US Company (“US Co”) identified two Hong Kong individuals who are highly experienced in doing business in the Mainland and are experts in Industry X.  US Co invited them to participate in the investment in Industry X in the Mainland. US Co established a Hong Kong holding company (call it “X Holdco”) with $100 capital, and the board of directors of X Holdco consisted of the above-mentioned Hong Kong individuals, two Hong Kong senior executives working in US Co’s other operating business in Hong Kong (“H Co”), and two US technical experts of US Co (so the ratio of Hong Kong and US directors is 4:2).  X Holdco has a bank account in Hong Kong and pays H Co for the use of H Co’s office premises, equipment, employees and administrative support provided. X Holdco worked together with US Co in the pre-investment feasibility studies, assessment and analysis, investment decision etc. X Holdco’s board of director meets two times each year in Hong Kong to review the Mainland project and future development, and the two Hong Kong individuals visit the US once a year to report on the business.  The Mainland investment proved to be highly profitable, and each year dividend is remitted to X Holdco which, after allocating around 20% of it to pay the salaries of the two Hong Kong individuals and expenses to H Co, and with no new viable investment plan in the pipeline, the rest (80%) would be declared as dividend and paid to US Co. In this case, there are genuine reasons for setting up the Hong Kong holding company, which has the ownership and right of control over the dividend income, but the case also meets all three Unfavourable Factors and thus it is likely that X Holdco would not be regarded as Beneficial Owner.  On the other hand, the Group may have a good chance passing PPT because there is an overriding commercial reason for setting up X Holdco in Hong Kong. That, however, may be irrelevant in the eyes of the Mainland tax bureaus because the structure of PN9 is that if Beneficial Ownership is denied, no PPT analysis would be carried out to further assess if treaty benefits should be granted. If this is what will happen in practice, it may be against OECD’s intention.

    It seems that if an Applicant does not qualify for the Safe-harbour Rule, it will have to be one of the two types of companies in order to qualify as the Beneficial Owner: (1) Active Operating Company, or (2) Group Holding Company with employees and holding multiple investments.  The question is: is it the view of the SAT that only these two kinds of companies “have the ownership and right of control on its dividend income”? There are commercial reasons, rather than tax reasons, for avoid using Active Operating Companies to be holding companies, and Group Holding Companies often use SPV to be the investing vehicle.  It seems that PN9 was purposefully designed, through the operations of the Unfavourable Factors, to only allow those who possess similar characteristics to the “Qualified Persons” in the LOB clauses to enjoy DTA benefits. More on “Qualified Persons” below.

    2.2    “Replacement Beneficial Owner” and Safe-Harbour Rule

    It appears that the “Replacement Beneficial Owner” and Safe-Harbour Rule would take care of the issue with SPV mentioned above.  Using Group Holding Company as an example, if the Company meets the conditions set out in Article 3 of PN9 and becomes the Replacement Beneficial Owner, then dividend earned by the SPV would enjoy treaty benefits.  Companies and tax representatives who have dealt with Cir 601 before may have tried to explore with local tax bureaus the possibility of “looking-through” the SPV structure under the principle of “substance over form” to identify if there is an entity above, resident in the same tax jurisdiction, which qualifies as a Beneficial Owner, in order to claim the treaty benefits on the basis that the structure was not “established for the purpose of avoidance or reduction of taxes or the transfer or accumulation of profits”.  However, as Cir 601 did not mention one could “look-through”, and if in the holding chain the equity interest is below 100%, would one apportion the DTA benefits proportionately? In principle, Beneficial Ownership cannot be apportioned: an entity either is or is not a Beneficial Owner. PN30 effectively disallowed it (it specified that one could “look-through” to the listed company with 100% shareholding). In practice, most tax bureaus would review if the Applicant meets the Unfavourable Factors in Cir 601, and review the upper holding structure from a “substance over form” perspective to see if there is evidence of treaty-abuse.  The “Replacement Beneficial Owner” provisions in PN9 has in effect provided the basis of “look-through”.

    “Look-through” is not new in assessing the entitlement to treaty benefits; the Safe-harbour Rule in LOB clause allows tax bureaus to “look-through”.  Using the Simplified LOB clause in Para 8 to 13 of Article 7 of the Multilateral Convention as an example, Para 8 requires that the benefits be granted to the Qualified Person.  In order to be the Qualified Person, a resident of a Contracting Jurisdiction (the Applicant) shall meet one of the following conditions set out in Para 9 (simplified by the Author):

    1. An individual;
    2. The local authority or relevant organisation of the Contracting Jurisdiction;
    3. A company or entity, if the principal class of its shares is regularly traded on one or more recognised stock exchanges;
    4. A non-profit organisation, or an entity set up in the Contracting Jurisdiction to administer retirement benefits for individuals or for investment in funds for such benefits:
    5. Other than an individual, if, on at least half the days of a twelve-month period that includes the time when the benefit would otherwise be accorded, persons who are residents of that Contracting Jurisdiction and that are entitled to benefits of the Covered Tax Agreement under (1) to (4) above hold, directly or indirectly, at least 50% of the shares of the person.

    Readers can easily see that the conditions for Qualified Person are very similar to, and more lenient than, the Safe-harbour Rule in PN9 Article 4.  A person (the Applicant) that is at least 50% held by a listed company on at least half the days of a twelve-month period that includes the time when the benefit would otherwise be accorded would be a Qualified Person.  By comparison, PN9 requires 100% direct or indirect shareholding for a continuous period of 12 months prior to obtaining the dividend, and if there are intermediate holding companies, they shall be resident of either the Mainland or the Contracting Jurisdiction.

    LOB clause also has provisions similar to “Replacement Beneficial Owner”, called the “Equivalent Beneficiary”.  Para 11 of Article 7 of the Multilateral Convention stated:

    A resident of a Contracting Jurisdiction to a Covered Tax Agreement that is not a qualified person shall also be entitled to a benefit that would otherwise be accorded by the Covered Tax Agreement with respect to an item of income if, on at least half of the days of any twelve-month period that includes the time when the benefit would otherwise be accorded, persons that are equivalent beneficiaries own, directly or indirectly, at least 75% of the beneficial interests of the resident.  

    What is “Equivalent Beneficiary”?  Para 13(c) of Article 7 of the Multilateral Convention stated that (simplified by the Author): the term “Equivalent Beneficiary” means any person who would be entitled to benefits with respect to an income accorded by a Contracting Jurisdiction to a Covered Tax Agreement under the domestic law of that Contracting Jurisdiction, the Covered Tax Agreement or any other international instrument which are equivalent to, or more favourable than, benefits to be accorded to that item of income under the Covered Tax Agreement.  The provision of “Equivalent Beneficiary” is very similar to “Replacement Beneficial Owner” but more lenient: an equivalent beneficiary is only required to hold directly or indirectly at least 75% beneficial interests of the resident on at least half of the days of any twelve-month period that includes the time when the benefit would otherwise be accorded. By comparison, according to PN9 Article 3 and 5, a person would be directly regarded as the Beneficial Owner if the Replacement Beneficial Owner holds directly or indirectly 100% shares in that person for a continuous period of 12 months prior to obtaining the dividend.  

    2.3    LOB’s Another Way Out for SPV

    According to the Simplified LOB, if the Applicant is not a Qualified Person, DTA benefits would only be granted if the recipient is engaged in active conduct of business, and the income derived from the other Contracting Jurisdiction emanates from, or is incidental to, that business.  However, the articles provided a way out for SPV to be granted treaty benefit. Para 10(c) of Article 7 of the Multilateral Convention stated that: activities conducted by connected persons with respect to a resident of a Contracting Jurisdiction shall be deemed to be conducted by such resident.  Diagram 4 below is an attempt by the Author to illustrate the salient points:

    PN9 has not provided the way out as illustrated in Diagram 4.  In other words, for a Hong Kong SPV which belongs to a group with Active Operating Companies or a Group Holding Company in Hong Kong, but such companies are not in the vertical holding structure of the SPV, these companies would not qualify as the Replacement Beneficial Owner, and would not be relevant to the SPV’s Beneficial Ownership assessment.

    2.4    Tax Resident Certificate

    Persons qualified under Situation Two of Replacement Beneficial Owner rule and Item 4 of Safe-harbour Rule are required to provide Tax Resident Certificates of all entities in the holding chain.  On the issuance of Tax Resident Certificates, many countries would require information such as nature of income and amount derived from the Contracting State, and the Certificate is issued based on the DTA signed with that Contracting State.  The issue is: the intermediate company receives dividend income from its immediate subsidiary, not from the bottom indirect subsidiary in the Mainland (e.g. the Intermediate company in Diagram 3 derived dividend income from Country A, not from the Mainland), and therefore in practice the Intermediate company may be refused by its in-charge tax authority the Tax Resident Certificate for dividend from the Mainland (in Diagram 3, Country C would only issue Tax Resident Certificate based on its DTA with Country A).

    For Hong Kong, according to the Inland Revenue Department (“IRD”) webpage (https://www.ird.gov.hk/eng/tax/dta_cor.htm), “a Certificate of Resident Status is a document issued by the Hong Kong competent authority to a Hong Kong resident who requires proof of resident status for the purposes of claiming tax benefits under the DTAs”.  The application form IR1313A requests for information regarding tax benefits to be claimed under the DTA with the Mainland.  Assuming the Applicant qualifies under Item 4 of Safe-Harbour Rule, in between the listed company and the Applicant there is an HK intermediate holding company which has no income from the Mainland, would the IRD issue the Certificate of Resident Status to this intermediate holding company?

    When PN9 was first issued, many companies were pleased that they qualify under Situation Two of Replacement Beneficial Owner rule or Item 4 of Safe-harbour Rule, but they could be heading for disappointment if they are not able to obtain the Tax Resident Certificates for the intermediate holding companies.

    2.5    Anti-Avoidance

    Even if the Applicant passed the Beneficial Ownership tests, it may still be required by tax bureaus to provide information to substantiate whether one of the main purposes of the set up was to obtain DTA benefits (PPT) or if domestic General Anti-Avoidance Rules would apply.  Applicants who wish to obtain DTA benefits are indeed subject to multiple hurdles under PN9.

    2.6    Conclusion

    In conclusion, the SAT has effectively slipped in LOB provisions that are more stringent than the Simplified LOB via the assessment of Beneficial Ownership into all DTAs entered into by the Mainland, without the need of matching under the Multilateral Convention, which seems to be against the spirit behind the Model Tax Convention, BEPS and the Multilateral Convention (the Mainland, like many other Tax Jurisdictions, did not opt for LOB).  According to Para 1 of Article 31 (General Rule of Interpretation) of the Vienna Convention on the Law of Treaties, which applies to treaties concluded between states, including DTAs concluded by Mainland China with other States, “A treaty shall be interpreted in good faith in accordance with the ordinary meaning to be given to the terms of the treaty in their context and in the light of its object and purpose”.  The term “Beneficial Owner” should be interpreted accordingly.  Therefore, although the SAT has the right to define the term “Beneficial Owner”, DTA partners would expect that the definition to be aligned with the ordinary meaning of the term and the Commentary of the Model Tax Convention, and they may challenge this much-narrowed definition of Beneficial Ownership.  In practice, the most affected DTA partner will likely be Hong Kong. For Hong Kong enterprises, since the DTA between the Mainland and Hong Kong is not a treaty between states, Hong Kong enterprises would not be able to apply the Vienna Convention directly in negotiation but may add this as a supporting point.  In case of dispute, it remains to be seen if the IRD would initiate discussions with the SAT for Hong Kong taxpayers for a fair and acceptable outcome.

    To avoid disputes, the Author recommends that the SAT replaces the Beneficial Ownership Guidelines with PPT guidelines, and return to the basic for Beneficial Ownership assessment, i.e. determine if the person has both the ownership and right of control over the income or the assets or rights generating the income, so that DTA benefits would be rightly granted to companies that are not conduits, and structures that are not set up with obtaining DTA benefits as one of the main purposes (such as the X Holdco in Case X above).  

    3.     Tax Tips:

    From now on, unless qualified under the Replacement Beneficial Owner or Safe-harbour Rule (and able to obtain the Tax Resident Certificates where applicable), Hong Kong enterprise would find it harder than before in obtaining benefits under the Mainland-Hong Kong DTA.  What can HK enterprises do? If Readers have followed the “tips” in the last issue of Tax Tips to read the new rules (PN9) in detail, and then study this article, one should be able to assess the potential impact on oneself and determine preliminary action proposals. Next is to discuss with tax advisors who are familiar with PN9 to confirm the step plan.  On the face of it, Hong Kong enterprises may change the holding structure to improve the chance of qualifying as the Beneficial Owner.

    However, all restructuring carry tax risks, especially when involving indirect transfer of equity interests in Mainland enterprises, which may be subject to the “Public Notice on Certain Issues on Enterprise Income Tax Relating to Indirect Transfer of Properties by Non-Resident Enterprises” issued by the SAT (Public Notice 2015 No.7).  Taxpayers are advised to consult tax consultants to avoid being exposed to higher tax risks than expected.  Further, if an arrangement or restructuring is carried out mainly for obtaining tax benefits, it may attract tax bureau’s attention and could lead to denial of DTA benefits.  Lastly, even if the restructuring is successfully completed, the Applicant may need to wait for twelve-month before the Beneficial Ownership qualification can be granted.

    From now on businesses should also consider the position to take in the PN60 reporting for DTA benefit claims, and, in the case of merger and acquisition involving Mainland enterprises, assess the potential additional tax liabilities that may be created by PN9.  

    In conclusion, PN9 has a profound impact on Hong Kong enterprises with investments in the Mainland, and its implications should be assessed carefully and immediately so that appropriate responses can be determined and implemented.  


    Author: Edwin Bin

    Ref:

    2018 Notice 9: http://www.chinatax.gov.cn/n810341/n810755/c3279059/content.html

    2018 Notice 9 Explanatory Notes: http://www.chinatax.gov.cn/n810341/n810760/c3278984/content.html

    Multilateral Convention:

    http://www.oecd.org/tax/treaties/multilateral-convention-to-implement-tax-treaty-related-measures-to-prevent-BEPS.pdf

    2015 Notice 7: http://hd.chinatax.gov.cn/guoshui/action/GetArticleView1.do?id=494731&flag=1

    Vienna Convention: http://legal.un.org/ilc/texts/instruments/english/conventions/1_1_1969.pdf

  • Tax Tips (8) – China Redefines “Beneficial Ownership” – Public Notice No.9

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on March 26, 2018: https://manageyourtax.com/HKEJ Forum 8)

    [Tax Tips (7) is a recommended pre-reading to facilitate reader’s understanding of certain terms used in this article.  Readers who are familiar with the history leading up to PN9 may jump directly to Tax Tips (9)]


    Hong Kong enterprises with investments in the Mainland should be familiar with the term “Beneficial Ownership”.  With the introduction of the new Enterprise Income Tax Law in 2008, dividend payment from Mainland enterprises to overseas jurisdictions is subject to 10% Withholding Tax.  The Double Tax Treaties or Arrangements (collectively referred to as “DTA” below) between the Mainland and the overseas jurisdictions have become important: Dividend Withholding Tax is reduced to 5% for payment to a number of countries (e.g. Singapore) or region (e.g. Hong Kong).  

    To many investors who entered the Mainland market early, they would be earning stable and growing dividends from the investments, and an effective means of reducing the Withholding Tax would significantly dampen the negative financial impact. Treaty Shopping, as mentioned in the last Tax Tips, is commonly adopted by enterprises in lowering their tax burden.  In order to combat Treaty Shopping which is an abusive use of the DTA, starting in 2009, the State Administration of Taxation of the Mainland (“SAT”) has issued several regulations to provide guidance in determining whether the income recipient is the Beneficial Owner, and thus entitled to DTA benefits. The latest regulation is the Public Notice No.9 of 2018 (“PN9”), titled “Public Notice Relating to “Beneficial Owner” Under Tax Treaties”, issued on 3 February 2018.   In this article, we first review the regulations superseded by PN9, so that Readers would be better equipped in understanding PN9.  

    Circular 601

    The SAT issued “Notice on the Interpretation and Recognition of Beneficial Ownership under Tax Treaties” (Circular (2009) No.601, “Cir 601”) in October 2009, which is well-known by Hong Kong enterprises, to help local tax bureaus to determine if the foreign recipient is the Beneficial Owner of the relevant income.  Article 1 of Cir 601 stated the key principle: “Beneficial Owner” refers to a person who has both the ownership and right of control over the income or assets or rights generating the income, is generally engaged in substantive business activities, and exclude persons such as nominees and conduit companies.  Cir 601 defined a conduit company as “a company established for the purpose of avoidance or reduction of taxes or the transfer or accumulation of profits”. The definition of Beneficial Owner is basically in-line with the OECD Model Tax Convention but raised the bar somewhat (see the last Tax Tips).

    Paragraph 2 of Cir 601 requires local tax bureaus to take a holistic approach in assessing the Beneficial Ownership qualification taking into account the primary aim of DTA (i.e. avoidance of double-taxation and prevention of tax evasion), consider “substance over form”, understand the facts and circumstances of each case, and analyse with the assistance of the seven “Unfavourable Factors”.  Through a comprehensive analysis of the Unfavourable Factors, if the applicant of treaty benefits claim (the “Applicant”) does not satisfy Article 1 of the Circular (does not have both the ownership and right of control over the income or assets or rights generating the income / is not engaged in substantive business activities / possess the characteristics of a nominee or conduit), the tax bureau should not recognise the Applicant as the Beneficial Owner.  The five Unfavourable Factors relating to dividend are:

    (1) The Applicant is obliged to pay or distribute all or most of (such as more than 60%) the income to a resident of a third country (region) in a stipulated time period (such as twelve months upon receipt of income);

    (2) The Applicant does not or barely engages in other operating activities except for holding the assets or rights that generated the income;

    (3) In case the Applicant is an entity such as a company, the Applicant’s assets, business scale and number of personnel are relatively small and could not reasonably match with the amount of income;

    (4) The Applicant has no or little right of control or disposal of the income or its underlying assets or rights; nor does it assume any or hardly any risks;

    (5) The income is non-taxable or tax-exempt in the other contracting state (region), or even if it is taxable, the tax rate is extremely low.

    As the amount of dividend Withholding Tax is often very large and have a significant impact on tax bureaus in meeting their revenue collection budget, many local tax bureaus tended to reject applications on the basis that the Applicant failed to meet one or two of the Unfavourable Factors under Cir 601.  Since Cir 601 stated that “local bureaus shall consolidate experience and uncover problems, and may report uncertain cases upwards towards the SAT (International Tax Department) for resolution”, many cases became uncertain cases when the Applicants disputed upon being rejected, and the SAT was flooded with cases to be resolved.  On the other hand, as the Applicants did not want to deal with the typically-problematic tax refund procedure, they decided not to remit dividend in order to avoid paying excessive amounts, until the SAT has concluded on their cases. Both the tax authorities and taxpayers faced tremendous pressure while their cases were being studied.  

    Public Notice 30

    The SAT is not an arbitration organisation for resolving disputes.  In order to reduce the number of cases reaching the SAT and encourage local tax bureaus to close cases at local levels, the SAT issued the “Notice on the Recognition of “Beneficial Owner” under Tax Treaties” (Public Notice No.30 of 2012, “PN30”).  PN30 reiterated that tax bureaus should analysis and determine each case based on the Unfavourable Factors set out in Cir 601 on a collective basis, and a decision to grant or reject an application should not be made simply because an Unfavourable Factor exists, or “the purpose of avoidance or reduction of taxes or the transfer or accumulation of profits” cannot be identified.  The Notice provided further specific guidance to help the tax bureaus, which include:

    1. Documents that should be reviewed;
    2. Safe-harbour Rule – If the Applicant is a company listed on the stock exchange of the contracting state, or is 100% held directly or indirectly by that listed company via companies that are residents of the same contracting state, the Beneficial Owner status can be granted directly to the Applicant;
    3. Approval at the Provincial-level tax bureaus – local tax bureau shall seek approval from the in-charge Provincial-level tax bureau for rejection cases, and the Provincial-level tax bureau shall file a report of such determination to the SAT for records.

    As the applicability of the Safe-harbour Rule is somewhat narrow, PN30 has limited effect in relieving the pressure in the system, and the SAT had to be involved in assisting the decision making in many cases.

    Circular 165

    Circular (2013) No.165 (“Cir 165”), titled “Views on the Treatments of Beneficial Ownership Cases involving the Dividend Article of the DTA between the Mainland and Hong Kong raised by HuBei and other Provincial and Municipal State Tax Bureaus”, was issued by the SAT in April 2013 as a collective reply to several cases raised by a number of local tax bureaus to provide SAT’s view on such cases.  Cir 165 has considered the actual situations of many Hong Kong enterprises and has established several viewpoints that are advantages to Hong Kong Applicants, such as:  

    1. If the Applicant has not distributed profits to any non-Hong Kong enterprise, it is not considered to be an Unfavourable Factor;
    2. Investment activities should be regarded as business activities
    3. Beneficial Ownership status should not be denied simply because the investing entity was set up for a single project only;
    4. Registered capital should not be considered equivalent to “Assets”
    5. No case should be decided based only on the number of employees or amount of employee expense
    6. The Applicant’s right of control and disposal of income should not be nullified simply because the shares of the Applicant is controlled by its immediate parent company
    7. The territorial concept of taxation adopted in Hong Kong which does not impose tax on profits sourced outside of Hong Kong should not be considered a key factor in deciding against the granting of the Beneficial Ownership status
    8. Article 3 of PN30 (the Safe-harbour Rule) should not be interpreted as the basis for rejecting the Beneficial Ownership status in the following situations:

    – The Applicant is 100% directly or indirectly held by Hong Kong resident that is not a listed entity;

    – There are overseas incorporated companies in the holding structure between the Applicant and the Hong Kong ultimate parent entity.

    However, as Cir 165 was a response specifically addressed to certain tax bureaus, other tax bureaus may make reference to the views stated therein but such views would not be binding on them.

    From Tax Office Approval to Taxpayer Self-Assessment

    Probably partly due to the pile-up of cases, the SAT issued the “Administration Rules on Non-Resident Taxpayer DTA Benefit Claim” (Public Notice No.60 of 2015, “PN60”).  PN60 is not an amendment of the Beneficial Owner definition but amended the procedure on DTA benefits claim. The key change is that instead of pre-approval by the tax bureaus, Applicant shall provide the supporting information if DTA benefit claim is to be lodged.  Tax bureaus would allow the claim upon receipt of the required information, and cases will be reviewed afterwards.  In other words, taxpayers can enjoy the benefits upfront knowing that they may be required to substantiate their claims when subsequently reviewed by tax bureaus.  The new arrangement has substantially reduced the tension between taxpayers and tax bureaus, and the tax bureaus could select cases for follow-up review by deploying risk assessment tools, which improved the efficiency in countering the abusive use of DTAs.

    The Latest Guidance on Beneficial Ownership – Public Notice No.9

    The newly-issued PN9 and its Explanatory Notes are applicable to DTA benefit claims on liabilities to tax or withholding arising on or after 1 April 2018, and replaced both Cir 601 and PN30.  PN9 is silent on Cir 165.

    Please note that as the discussion on PN9 is over 4,400 words long, it will be covered in the next issue of Tax Tips, to be issued on 9 April 2018.   


    Tax Tips: The Author always encourage friends who are concerned about how new tax rules would affect them to first read the rules themselves, then study the Tax Flash/Alert issued by the large firms in order to do a preliminary assessment of the impact, which can then be verified with tax consultants in order to determine the appropriate course of action for implementation.  Since PN9 comes with a detailed Explanatory Notes (with six examples), Readers who have studied the last Tax Tips and this article should find PN9 not too difficult to understand.

    Author: Edwin Bin


    Ref (all in Chinese)

    2009 Cir 601: http://hd.chinatax.gov.cn/guoshui/action/GetArticleView1.do?id=75287&flag=1

    2012 Notice 30: http://hd.chinatax.gov.cn/guoshui/action/GetArticleView1.do?id=204882&flag=1

    2013 Cir 165: http://hd.chinatax.gov.cn/guoshui/action/GetArticleView1.do?id=217850&flag=1

    2015 Notice 60: http://hd.chinatax.gov.cn/guoshui/action/GetArticleView1.do?id=1521450&flag=1

    2018 Notice 9: http://www.chinatax.gov.cn/n810341/n810755/c3279059/content.html

    2018 Notice 9 Explanatory Notes: http://www.chinatax.gov.cn/n810341/n810760/c3278984/content.html


  • Tax Tips (7) – Say Goodbye to Tax Treaty Benefits?

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on March 12, 2018: https://manageyourtax.com/HKEJ Forum 7 )


    Originally we would be discussing in this Tax Tips the new Public Notice No.9 of 2018 issued by the State Administration of Taxation on 3 February 2018 titled “Public Notice Relating to “Beneficial Owner” Under Tax Treaties” (“PN9”) which will be applicable tax treaty benefit claims on tax obligations arising on or after 1 April 2018.  However, as the various concepts under PN9 are not easy to be understood without background, we explain the relevant concepts in this article, and the discussion on PN9 will be deferred to the next Tax Tips.

    Tax Tips 2 mentioned that in June 2017 representatives of Mainland’s State Administration of Taxation signed the “Multilateral Convention to Implement Tax Treaty Related Measures to Prevent Base Erosion and Profit Shifting” (“Multilateral Convention”) on behalf of Hong Kong, and Mainland China also signed the convention on the same day, to implement BEPS(1)  Action 15 “Developing a Multilateral Instrument to Modify Bilateral Tax Treaties”.  One of the purposes of the Multilateral Convention is to prevent abuse of preferential tax treatments under Double Tax Treaties and Arrangements, below collectively referred to as “DTA”, (BEPS Action 6: Preventing the Granting of Treaty Benefits in Inappropriate Circumstances), and at the same time, it also contains provisions for implementing BEPS Action 2 (Neutralising the Effects of Hybrid Mismatch Arrangements), Action 7 (Preventing the Artificial Avoidance of Permanent Establishment Status) and Action 14 (Making Dispute Resolution Mechanisms More Effective).  In short, many parts of the DTA shall be amended.    

    Hong Kong taxpayers would likely be most concerned about whether the DTA benefits they currently enjoy would be lost: reduced withholding tax rate on dividend, interest and royalties (e.g. when withholding tax on dividend is 10%, and the dividend declared is $100, the payor shall withhold $10 of tax and only remit $90 to the shareholder).  As the purpose of the amendment is to prevent treaty abuse, in theory, if there is no abusive structure, the amendment should not cause any concern (whether the tax office takes the same view is, of course, another matter). In general, a situation in which a person who is not entitled to the benefits of a tax treaty makes use of an arrangement to obtain treaty benefits that are not available directly would be considered to be engaged in “treaty shopping” and have abused the DTA.  The simple diagram below illustrates what is treaty shopping.

    Elaboration: Enterprise in Country A enjoys the reduced WHT rate on dividend by setting up a company in Country B

    Beneficial Owner

    Most DTAs will have the following sentence at the beginning: “The Government of A and the Government of B, desiring to conclude an Agreement for the avoidance of double taxation and the prevention of fiscal evasion with respect to taxes on income, have agreed as follows:”.  The purpose of the DTA is to enhance trade between the two countries by providing clear guidelines on tax treatment (e.g. taxing right) to taxpayers of the one side engage in economic activities on the other side, and reduce the chance of taxpayers having to pay tax on both sides on the same income.  Since both sides would like to encourage economic activities, preferential tax rates would be provided to treaty partners, and focus on taxes that would be paid on a withholding basis: dividend, interest and royalty. The opportunity to reduce tax attracts abusive behaviour.  DTAs are not silent on anti-abuse provision; the OECD Model Tax Convention introduced the concept of Beneficial Owner in 1977, and most DTAs in the world now require that only the Beneficial Owner of the dividend, interest and royalty income can enjoy the preferential withholding tax rates.  Why would there be situations of granting treaty benefits in inappropriate circumstances when the anti-abuse mechanism is in place?

    The problem stems from the definition of Beneficial Owner.  “Beneficial Ownership” is a term from English trust law. In many countries, the term is not defined.  Although the OECD raised the concern as early as 1986 when the organisation issued the Double Taxation Conventions and the Use of Conduit Companies, at that time treaty-abuse was not in the limelight and most countries did not scrutinise into whether the recipients granted the DTA benefits were the Beneficial Owners as long as they could provide the Tax Resident Certificates.  

    For many years, the commentary to the OECD Model Tax Convention has explained what is beneficial ownership.  In the latest condensed version of the OECD Model Tax Convention and Commentary (over 650 pages long), Para 12.3 of the Commentary to Article 10 Dividend stated that “conduit companies cannot normally be regarded as the beneficial owner if, though the formal owner, it has, as a practical matter, very narrow powers which render it, in relation to the income concerned, a mere fiduciary or administrator acting on account of the interested parties”.  And in Para 12.4 of the Commentary to the same article, it is stated that “ where the recipient of a dividend does have the right to use and enjoy the dividend unconstrained by a contractual or legal obligation to pass on the payment received to another person, the recipient is the “beneficial owner” of the dividend”.  This definition of “beneficial owner” has basically remained the same throughout the years.  However, it is a reality that companies can carefully structure their arrangements such that they can treaty-shop and meet the beneficial ownership requirement at the same time.  Certain countries have introduced additional reporting requirements over the past decade or so on treaty benefit claims, by setting criteria for assessing whether the applicant has the right to use and enjoyment of the relevant income, with no obligations to pass it on to others.  Hong Kong companies should be familiar with this because of the Circular (2009) 601 titled Notice on the Interpretation and Recognition of Beneficial Ownership under Tax Treaties issued by the State Administration of Taxation of the Mainland China.

    Multilateral Convention to Combat Treaty Shopping

    Riding on the momentum of the BEPS Project, tax jurisdictions are gearing up efforts in combating treaty shopping.  Action 6 recommend the following approaches in dealing with treaty shopping:

    First, a clear statement that the States that enter into a tax treaty intend to avoid creating opportunities for non-taxation or reduced taxation through tax evasion or avoidance, including treaty shopping arrangements, will be included in tax treaties.

    Second, a specific anti-abuse rule, the limitation-on-benefits (LOB) rule, that limits the availability of treaty benefits to entities that meet certain conditions will be included in the OECD Model Tax Convention.  These conditions, which are based on legal nature, ownership in, and general activities of the entity, seek to ensure that there is a sufficient link between the entity and its State of residence.

    Third, in order to address other forms of treaty abuse, including treaty shopping situations that would not be covered by the LOB rule described above, a more general anti-abuse rule based on the principal purposes of transactions or arrangements (the Principal Purposes Test or “PPT” rule) will be included in the OECD Tax Convention.  Under that rule, if one of the principal purposes of transactions or arrangements is to obtain treaty benefits, these benefits would be denied unless it is established that granting these benefits would be in accordance with the object and purpose of the provisions of the treaty.

    Tax jurisdictions that have signed the Multilateral Convention have all accepted the PPT.  Some, however, have opted for adding the Simplified LOB on top. In simple terms, under the Simplified LOB, unless the person is an individual, listed company, or an entity conducting an active business and the income from the other side either emanates from or is incidental to that business, no treaty benefits would be granted.  The term “active conduct of a business” shall not include the following activities or any combination thereof: i) operating as a holding company; ii) providing overall supervision or administration of a group of companies; iii) providing group financing (including cash pooling); or iv) making or managing investments.  If a resident of a Contracting State derives an item of income arising in the other State from a connected person, benefits would be granted with respect to such item only if the business activity carried on by the resident in the first-mentioned State to which the item is related is substantial in relation to the same or complementary business activity carried on by such connected person in the other Contracting State.  If both sides intend to adopt the LOB (i.e., stronger than Simplified LOB), the two sides shall separately negotiate.

    Hong Kong as a financial center has limited industries and will be hard to satisfy Simplified LOB.  For example, if a Hong Kong investor invests in coal-mining in Country A, and the investor would conduct activities such as holding, supervision, financing and managing the investment but without actual coal-mining activities in Hong Kong, the investor would unlikely be able to claim that it conducts active business in Hong Kong.  If the DTA between Hong Kong and Country A adopts Simplified LOB, the Hong Kong investor would unlikely be able to enjoy the treaty preferences. In other words, even there is no tax avoidance, the Hong Kong investor would be denied treaty benefits.

    Both the Mainland and Hong Kong wisely rejected the Simplified LOB.   Depending on the choice of the parties to the tax treaties under the Multilateral Convention, when the local legal procedures in each country or region are completed, taxpayers in Hong Kong who want to enjoy preferential tax treaties may need to prove that obtaining the concession is not one of the principal purposes of the arrangement or transaction.  What if the Contracting States such as Indonesia and Mexico choose the Simplified LOB? The Multilateral Convention allows countries to choose the applicable provisions and then pair with the Contracting States. Although both Indonesia and Mexico have opted for the Simplified LOB, both countries have chosen Article 7 (6) of the Multilateral Convention, which means the Simplified LOB applies only when both parties to a DTA select the Simplified at the same time.  In other words, it is very likely that the DTAs between Hong Kong and Indonesia and Mexico will adopt PPT.

    What Exactly is PPT?

    Using the DTAs between Hong Kong and Indonesia and Mexico as examples, both DTAs will adopt Article 7(1) of the Multilateral Convention, which reads:

    Notwithstanding any provisions of a Covered Tax Agreement, a benefit under the Covered Tax Agreement shall not be granted in respect of an item of income or capital if it is reasonable to conclude, having regard to all relevant facts and circumstances, that obtaining that benefit was one of the principal purposes of any arrangement or transaction that resulted directly or indirectly in that benefit, unless it is established that granting that benefit in these circumstances would be in accordance with the object and purpose of the relevant provisions of the Covered Tax Agreement.

    In fact, Hong Kong’s DTAs with Indonesia and Mexico already have anti-avoidance clauses.  For example, paragraph 7 of Article 10 – Dividends of the DTA between Hong Kong and Indonesia states “The provisions of this Article shall not apply if it was the main purpose or one of the main purposes of any person concerned with the creation or assignment of the shares or other rights in respect of which the dividend is paid to take advantage of this Article by means of that creation or assignment.”  When both parties to the DTA (for example, Hong Kong and Indonesia) have completed domestic legal procedures, the anti-avoidance clauses of the original DTA would be replaced by Article 7(1) of the Multilateral Convention, which has relatively minor impact.

    The DTA between Hong Kong and the Mainland

    Lastly, as the DTA between Hong Kong and the Mainland is not a Covered Tax Agreement of the Multilateral Convention (as it is not a treaty between two sovereign states), Hong Kong and the Mainland shall negotiate to incorporate the BEPS measures into the DTA.  As both sides have accepted PPT, it can be envisaged that DTA will adopt the PPT provision, replacing Article 4 of the Fourth Protocol of the DTA, which reads:

    In relation to Articles 10, 11, 12 and 13 of the Arrangement, if the creation or disposition of the interests acquired is caused by any person with the main purpose of taking advantages of any of such Articles, the Article shall not apply.

    So is the forthcoming amendment good news or bad news to Hong Kong companies?  On the face of it, under Article 4 of the Fourth Protocol, the benefits would be denied if the main purpose of making certain arrangement is to take advantage of the DTA.  Under PPT, benefits would be denied if one of the main purposes is to take advantage of the DTA.  In theory, as the bar is lower under PPT, it would be harder to obtain treaty benefits in the future.    

    Other than PPT, Hong Kong investors looking to enjoy benefits under the Hong Kong and Mainland DTA would also need to pass the “Beneficial Ownership” test.  This will be discussed in the next issue of Tax Tips.

    (1) See Tax Tips (1) and (2)


    Tax Tips: Hong Kong taxpayers who invest directly overseas and enjoy preferential tax treaties benefits should not be hard pressed to prove that they did not set up the investment framework for the purpose of enjoying benefits available under the DTA between Hong Kong and that overseas location.  However, to prepare for requests in the future to substantiate why the structure is set up, Hong Kong investors should start reviewing the structures and prepare documentation supporting on the commercial rationales and business reasons for the current structure or arrangement. In cases where the Hong Kong investors entered overseas markets through intermediate overseas vehicles, or foreign groups using a Hong Kong subsidiaries as a springboards to invest into the Mainland, and enjoy DTA benefits, it is time to start studying the sustainability of the structures and prepare for questions from the tax offices as to why this intermediate holding company was set up.  It is now time to take action. Finally, this article focuses only on certain articles of the Multilateral Convention. There are other articles in the Convention that may impact and create uncertainties for taxpayers. Taxpayers need to carefully analyze the changes to each applicable DTA, in order to prepare appropriate responses.

    Author: Edwin Bin


    Ref:

    Multilateral Convention:

    http://www.oecd.org/tax/treaties/multilateral-convention-to-implement-tax-treaty-related-measures-to-prevent-BEPS.pdf

    Model Tax Convention on Income and on Capital: Condensed Version 2017:

    http://www.keepeek.com/Digital-Asset-Management/oecd/taxation/model-tax-convention-on-income-and-on-capital-condensed-version-2017_mtc_cond-2017-en#.WmNWKqiWYdU#page29

    HK-Mainland DTA Fourth Protocol:

    https://www.elegislation.gov.hk/hk/cap112CU!en@2015-12-11T00:00:00  


  • Tax Tips (6) – Territorial Concept x Transfer Pricing

    The Inland Revenue (Amendment) (No. 6) Bill 2017 (the “Bill”) that was discussed in Tax Tips (2) and (3) proposed to introduce Part 8AA – Transfer Pricing Rules to the Inland Revenue Ordinance.  Transfer Pricing rules require transactions with associated enterprises be conducted under the Arm’s Length Principle.  Section 50AAD(1) of Part 8AA reads: “This Part applies in determining a person’s liability for property tax, salaries tax and profits tax”.  Putting aside Property Tax and Salaries Tax (the Author does not think that it is appropriate to extend transfer pricing regulations to Salaries Tax), the Author’s interpretation of this Section is that “when a person is liable to Profits Tax, Part 8AA operates to determine the extent of the liability”.  Whether a person is liable to Profits Tax, one shall mainly refer to Section 14(1) of the Inland Revenue Ordinance, which says:

    Subject to the provisions of this Ordinance, profits tax shall be charged for each year of assessment at the standard rate on every person carrying on a trade, profession or business in Hong Kong in respect of his assessable profits arising in or derived from Hong Kong for that year from such trade, profession or business (excluding profits arising from the sale of capital assets) as ascertained in accordance with this Part.

    If the profits of a connected transaction are derived from outside Hong Kong and not subject to Profits Tax under Section 14(1), the Hong Kong taxpayer should be regarded as “not liable to profits tax” and thus Section 50AAD(1) of Part 8AA would not be applicable.  Even if the Hong Kong taxpayer has substantive business and operating activities in Hong Kong, as long as the profits of the connected transactions are derived from outside Hong Kong, the Inland Revenue Department (“IRD”) should not impose Profits Tax on the profits attributable to the risks assumed and functions carried out in Hong Kong. This is the correct treatment because if the substantive business activities carried out by non-associated enterprises would not be subject to Profits Tax, the same activities carried out by associated enterprises should not be treated differently.  This principle has been mentioned in Paragraph 71 of the Departmental Interpretation and Practice Notes No. 46 – Transfer Pricing Guidelines – Methodologies and Related Issues (December 2009) (“DIPN 46”).  In theory, the principle of territorial-based taxation is maintained.

    Connected Transactions in D25/14

    In the last issue of Tax Tips, the Inland Revenue Board of Review (“BOR”) Decision for Case D25/14 (published in February 2016 Volume 30 First Supplement) was discussed.  Although the matter in dispute was not related to transfer pricing, as the case involved both the source of profits and transfer pricing, it can be used to discuss this topic: if Part 8AA Section 50AAD(1) was already the law, how would it apply to the case? [Please refer to Tax Tips (5) for the background of the case]

    Case Appellant Company A (“Co A, a Hong Kong company) had no employee and asset in Hong Kong, all contracts were entered into and performed outside Hong Kong, but the BOR determined that regardless of the whereabouts of the controlling staff and the places where the contract was entered into and performed, the trading between Taiwan Co and Mainland Co would have been impossible in the absence of the Appellant as the “middleman”.  The activity of playing such role was obviously in Hong Kong.  The BOR rejected the Appellant’s argument that “the profits were not arising in or derived from Hong Kong”, and confirmed that the profits of Co A were fully subject to Profits Tax.  Assuming Part 8AA has been implemented, given that Co A’s transaction was definitely a connected transaction and has been ruled by the BOR to be liable to Profits Tax, how would the IRD “determine the extent of such liability?”

    Under normal circumstances, “to determine the extent of such liability”, one basically assumes Co A was not an associated company of Taiwan Co and Mainland Co, and based on Co A’s functions, risks, government policies etc., search for comparable companies in the market, select the appropriate transfer pricing method to determine whether Co A’s profit is lower than those earned by comparable companies under the Arm’s Length Principle.  If it is determined to be lower than the arm’s length profits, the IRD may adjust the assessable profits upward and assess Profits Tax.  Although Co A’s case did not disclose the functions performed and risks assumed by each of the affiliated companies, it can be reasonably assumed that most of the risks were borne by Taiwan Co, such as bad debts, cargo insurance, foreign exchange risks etc.  The three companies each had their own functions, but Co A did not have employee and asset so it could only have performed limited functions.  In addition, as Co A only served as an intermediary for the entire transaction, if the Taiwan Co did not own Co A, but rather traded with the mainland manufacturer through an independent, non-affiliated Hong Kong company (call it “Co X”), it would be likely that a lot of genuine Hong Kong trading companies would be happy to take up the middleman role for a relatively lower return for the limited risks it would bear.  This “middleman” role, which was regarded as extremely important by the IRD and the BOR, would not seem to be very valuable from transfer pricing perspective.

    The Author suspects that the entire planning behind Co A was that Co A was expected to be successful in Hong Kong Profits Tax exemption on the basis that the profits were sourced from outside Hong Kong, thus it is likely that Co A made excessive profits during the years.  According to publicly available information, from 2002 to 2005, Co A’s total sales revenue was HK$237,121,169, with an aggregated pre-tax profit of HK$60,053,849 (after loss offset), resulting in a high net profit margin of 25%!  Would this “very important intermediary role” be entitled to earn such a high profit?  Would the Taiwan Co give more than HK$60 million of profits to the independent, non-affiliated Co X?  As for the Mainland Co, the total profits from 2002 to 2005 was only RMB918,234 (after loss offset)!  It seems that Co A was carefully operated to lower the group’s overall tax burden by making the offshore claim.

    Anti-Avoidance is the Highest Principle?

    The Author also suspects that the IRD was aware of the possible tax avoidance via offshore claim.  As it would be inappropriate to invoke the General Anti-Avoidance provisions under Section 61A of the Inland Revenue Ordinance to tackle this case, the IRD countered such avoidance act by seeking to disallow the Offshore Claim.  As the contracts of sale and purchase of Co A were effected and performed outside Hong Kong, under DIPN 21 as referred to in the last issue of the “Tax Tips” the profits would not be subject to tax in Hong Kong.  In order to win the case, the IRD linked the “extremely important” middleman’s role and functions (which is a concept of transfer pricing) with the source of profits, and succeeded in winning at the cost of overturning DIPN 21.  In the past, the IRD would respect the territorial concept of taxation and would not inquire whether the relevant profits were taxed elsewhere.  However, under the bandwagon of BEPS(1), it seems that anti-avoidance has become the highest principle.  As for the BEPS concept of “allowing companies to pay tax at the location of their real business activities and value creation”, the real idea seems to be that “if no one is claiming tax on profits, I will come forward”.  Therefore, it will become more and more difficult to be granted the offshore treatment in the future (many people would have felt it already in the past few years).  This is particularly worrying as the law and DIPN 21 have remained unamended.

    Finally, would the IRD adjust-down Co A’s assessable profits (assuming the transfer pricing report determines that Co A’s profit is too high) in accordance with the arm’s length principle?  The answer is “No”, not only because the subject matter in question is the source of profit, as a matter of policy, the IRD would simply not proactively adjust-down excessive profits.  Furthermore, unless the tax authorities in the Mainland decided that Co A has constituted a permanent establishment in the Mainland and imposed a 25% corporate income tax on the profits of Co A, there is no double taxation and the IRD can safely pocket the tax revenue. This principle is also illustrated in paragraphs 71 and 72 of DIPN 46.

    (1) See “Tax Tips” (1) and (2)

    Tax Tips: Taxpayers must recognise the general direction and current climate of transfer pricing.  Before making any arrangement, it is important to anticipate that every tax office involved in a transaction wants a share of your profits — tax authorities are increasingly interested in using “Profits Split” to divide the profits of the entire supply chain.  It is conceivable that there will also be disagreements between tax authorities, and taxpayers in Hong Kong may eventually have to ask the IRD to invoke the Mutual Agreement Procedure and Arbitration under the double taxation arrangements to negotiate with the other side (or multiple sides) on who gets to tax which part of your profits.  After lengthy discussions, taxpayers would also have to pay IRD the relevant fees (Section 50AAB introduced in the Bill refers).  It is recommended that taxpayers should immediately review all connected transactions, collect evidence and supporting arguments, determine the most suitable transfer pricing methodologies, and prepare appropriate transfer pricing documentation to meet possible challenges in the future.

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on February 26, 2018: https://manageyourtax.com/HKEJ Forum 6)

    Contact Us

    Author: Edwin Bin

    Ref:

    The Bill: http://www.gld.gov.hk/egazette/pdf/20172152/es32017215229.pdf

    D25/14: http://www.info.gov.hk/bor/tc/docs/D2514.pdf

    DIPN 21: https://www.ird.gov.hk/chi/pdf/c_dipn21.pdf

    DIPN 46: https://www.ird.gov.hk/eng/pdf/e_dipn46.pdf

  • Tax Tips (5) – Does the Territorial Concept of Taxation Still Exist?

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on February 9, 2018: https://manageyourtax.com/HKEJ Forum 5).

    Foreword: Bad answers to IRD enquiries can be catastrophic to other taxpayers…

    As mentioned in the previous issue, one of the criteria for a good tax system is fairness, while others include simple and easy to understand, low compliance costs, high transparency and high certainty.  The author started working on Hong Kong tax more than 20 years ago.  At that time, the Hong Kong tax system did meet the requirements of a good tax system.  But is the tax system in Hong Kong still good today?  The speech by the Financial Secretary, Mr Paul Chan, at the “Summit on New Directions for Taxation” in October last year referred to the government’s tax policy direction in recent years and the future prospects.  In the Tax Tips to follow the author will comment based on the Financial Secretary’s speech.

    The Financial Secretary said: “Hong Kong has always followed the simple low-tax system and the territorial concept of taxation. Today it has one of the lowest tax rates in the world in terms of corporations and individuals, making it the world’s premier business location … However, today we are in the 21st century, great changes are happening in the global political and economic arena.  Tax measures have gradually become a means of competition among various economies, attracting investors and supporting industries through this competitive approach.  We are seeing the shortcomings of Hong Kong’s simple and low tax system… “.  This issue discusses the territorial concept of taxation.

    The Territorial Concept of Taxation

    In theory, as long as Section 14(1) of the Inland Revenue Ordinance (“IRO”) is not changed, the Government can still claim that Hong Kong is maintaining the territorial concept of taxation, the problem is whether in practice this concept is still being respected.  One criticism of the Inland Revenue Department (“IRD”) is that the Department no longer respects the territorial concept of taxation.  Taxpayers today are finding out that the same profits with the same offshore source would no longer be considered offshore source by the IRD.  Let us first revisits what Section 14(1) says:

    Subject to the provisions of this Ordinance, profits tax shall be charged for each year of assessment at the standard rate on every person carrying on a trade, profession or business in Hong Kong in respect of his assessable profits arising in or derived from Hong Kong for that year from such trade, profession or business (excluding profits arising from the sale of capital assets) as ascertained in accordance with this Part. (NB: fonts in bold added by the author)

    The Inland Revenue Board of Review (“BOR”) Decision for Case D25/14 (published in February 2016 Volume 30 First Supplement) is an interesting case worth looking at.  The Appellant was a Hong Kong incorporated company (“A Co”/”HK Co”) that acted as the middleman in the trading between Taiwan and the Mainland to circumvent the direct trading restriction (the “Three Direct Links” – Direct Posts, Direct Vessels, Direct Flights) between Taiwan and the Mainland at that time.  The diagram below sets out the relationships and operations of the companies involved.

    Except for the transshipment of raw materials and finished goods through Hong Kong, the following operations are carried out by either the Taiwan Co or employees of the Mainland Co in these two locations: receiving orders from Taiwan Co for purchasing products / contacting Mainland Co for manufacturing / negotiating with Taiwan Co for raw materials purchases / arrange the delivery of raw materials / test the quality of raw materials / test the quality of finished products / issuance of invoices, billing and settlement.  The Appellant’s directors were only involved in the raw materials purchases for the Mainland Co and the activities were carried out in the Mainland.  On the profits tax return, the Appellant claimed that it operated entirely outside Hong Kong and therefore did not have any profit taxable profits or losses that can be set off against profit tax.  The IRD dismissed the claim issued an assessment of profits tax of HK$12.36 million in total for the years of assessment 2002/03 to 2005/06.  After rounds of correspondences, the Appellant failed to convince the IRD and subsequently appealed to the BOR.

    The core issue of this case is the answer to the following three questions:

    (1) Did the Appellant carry on a trade, profession or business in Hong Kong?

    (2) Did the Appellant’s profits that should be assessed come from the trade, profession or business of the Appellant?

    (3) Was the profit arisen in or derived from Hong Kong?

    These three issues are precisely the conditions under Section 14 (1) of the IRD.  All three conditions must be met for profits to be chargeable to Profits Tax.

    What the Appellant said

    The Appellant did not consider it appropriate to determine that a trade, profession or business has been established in Hong Kong solely because it was a limited company incorporated in Hong Kong.  Instead, one should focus on the nature of the activities carried out in Hong Kong and exclude any ancillary activities.  Since the Appellant considered its activities in Hong Kong to be ancillary in nature, the Appellant contended that no business was conducted in Hong Kong, and thus the above first condition was not met.

    With regard to the second condition, the Appellant did not deny that it made profits out of its business, which was conducted outside of Hong Kong. Therefore, the Appellant considered the second condition to be met, for the offshore business activities.

    As for the above conditions for “profits arising in or derived from Hong Kong”, the Appellant did not think Hong Kong should be the source of profits simply because the taxpayer was operating in Hong Kong. In summary, the Appellant argued that the “actual cause” of the trading profits came from the contracts which were entered into and performed outside Hong Kong.  Therefore, the Appellant considered that its profits were not arising in or derived from Hong Kong, and thus the third condition was not met.

    Views of the IRD Representative and Judgement by the BOR

    With regard to Condition 1: whether the Appellant carried on a trade, profession or business in Hong Kong, the Board considered that the Appellant’s operations in Hong Kong was more than ancillary nature and dismissed the Appellant’s statement.  The Board arguments included: A Co acted as the “middleman” and was a true legal entity with specific functions within a Taiwanese corporate group.  It was not a paper company.  A Co prepared financial statements in Hong Kong and has bank accounts in Hong Kong.  The documents of A Co showed that the company’s business address was in Hong Kong. Another important factor is that the customs documents showed that the raw materials and finished goods landed in Hong Kong for transshipment, and the finished goods were consolidated onto a large vessel in Hong Kong for shipping to Taiwan.  A Co clearly intended to ensure that trading activities must be conducted through Hong Kong.  These activities are direct evidence that A Co had an actual and important business.  Without this “middleman”, it would have been virtually impossible for any trade to be conducted under the environment at that time.  Therefore, although A Co’s business activities were not as substantial as other trading companies, it had certain, and indeed very important, business and specific roles.  The IRD representative also pointed out during the hearing that there was no evidence to show that the central management and control of the taxpayer was outside Hong Kong (the information showed that one of the five directors of A Co was a director and supervisor of the Taiwan Co, one served as both the director of Taiwan Co and Mainland Co, the other three were also directors of Mainland Co, with one of them being also the general manager of Mainland Co.  It seems that none of them was managing the business of A Co in Hong Kong).

    In regard to the most crucial question: Whether the profits were arising in or derived from Hong Kong, the IRD representative said: “The business of a company must be carried out in a place where the important activities are carried out, and that place is not necessarily the same place of decision making.  Business can be conducted in Hong Kong with a limited scale of actual activities”.  The representative of the IRD also claimed that “the place where the documents are produced [the author: the negotiation and conclusion of the contracts?] is not important for determining the source of the Appellant’s profits.  The sources of profits shall be determined based on facts, which is a commercial issue rather than technical issue.  In this appeal case, the reality is that the Appellant earned profits by selling goods from a subsidiary in the Mainland to the parent company in Taiwan.  These sales must be routed through Hong Kong.  In fact, the goods were transshipped through Hong Kong.  The antecedent and ancillary activities were carried out in various locations.  The actual reason for the generation of profits is the transshipment activities”.

    The Board opined that in deciding whether the source of profits came from Hong Kong, the place where a contract was entered into and performed was an important factor, but not a decisive one.  In investigating the activities from which the Appellant derived profits, attention must be given to the fact that the activities might not be the trading activities which one conventionally perceived (i.e. the entering into and performance of the contract, etc.).  As Lord Janucey mentioned in the IRC v HK-TVB International Ltd case, “one looks to see what the taxpayer has done to earn the profit in question and where he has done it”.

    The Board pointed out that the Appellant was inserted as a “middleman” to circumvent the trade restrictions in force between the Mainland and Taiwan.  Although the number of activities was not large, it had a necessary role. In other words, regardless of the whereabouts of the controlling staff and the places where the contract was entered into and performed, the trading between Taiwan Co and Mainland Co would become impossible in the absence of the Appellant.  The activity of playing such role was obviously in Hong Kong.  There was no evidence to show that the profits were derived from outside of Hong Kong.

    Lastly, the Board mentioned that according to authorities, the place where a contract was entered into was an important factor in deciding the source of profits, and the mode of trade and destination of the goods shipped might be a factor of less importance; but in light of the trade restriction which was in force at the material period, the former became peripheral and less important, while the latter was an important factor when considering the source of profits.

    The appeal was dismissed.  The author understands that A Co has not lodged a further appeal.

    What the IRD said before

    Readers would likely be familiar with the “Departmental Interpretation and Practice Notes No. 21 – Locality of Profits” (Revised in July 2012).  The IRD’s views which are reflected in its assessing practice on the locality of profits derived from trading in commodities or goods by a business carried on in Hong Kong are contained in Para 23, as follows:

    (a) Where both the contract of purchase and contract of sale are effected in Hong Kong, the profits are fully taxable.
    (b) Where both the contract of purchase and contract of sale are effected outside Hong Kong, no part of the profits are taxable.
    (c) Where either the contract of purchase or contract of sale is effected in Hong Kong, the initial presumption will be that the profits are fully taxable.
    (d) Where the sale is made to a Hong Kong customer (including the Hong Kong buying office of an overseas customer), the sale contract will usually be taken as having been effected in Hong Kong.
    (e) Where the commodities or goods are purchased from either a Hong Kong supplier or manufacturer, the purchase contract will usually be taken as having been effected in Hong Kong.
    (f) Where the effecting of the purchase and sale contracts does not require travel outside Hong Kong but is carried out in Hong Kong by telephone, fax, etc., the contracts will be considered as having been effected in Hong Kong.
    (g) The purchase and sale contracts are important factors but all the relevant operations that produce the trading profits must be looked at to determine the locality of the profits.

    DIPN 21 Para 24 reads: “Having regard to the points expressed above [author: (a) to (g) above], it will be apparent that, in the Department’s view, the question of apportionment does not arise in relation to trading profits. Trading profits will be either wholly taxable or wholly non-taxable. There is no room to substitute a mixed source for a Hong Kong source even though there might be some overseas activities”.

    After revisiting DIPN 21 and look back to the case, would readers agree to the statements made by the IRD representative and the decision of the BOR?  They both placed high importance on the role of the Hong Kong company but did not say anything about the contracts were entered into and performed outside Hong Kong.  They focused on the essential role that the Hong Kong company played and determined the source of profits based entirely on this factor; yet the source of profits has always been determined based on the conclusion of the sales and purchase contract, but not the level of importance of the Hong Kong company (is there any middleman that has no role and not needed?).  Further, without the sales and purchase contracts, there would not be any profits.  If there is another identical case but without the “Three Direct Links” background (for example, replace Taiwan Co with a UK company), would the IRD and the BOR maintain the same judgment?  If the conclusion would be different (offshore profits), then I would recommend the IRD to revise DIPN 21 so that taxpayers would know under what situations would profit be treated as onshore even when the contracts are effected and performed outside of Hong Kong.  If the conclusion is the same (source of profits is determined based on the taxpayer’s role and degree of importance), the territorial concept of taxation is effectively abolished, and the Government should commence tax reform and amend the IRO as soon as possible.   

    An alternative route is profit apportionment.  DIPN 21 Para 46 mentioned “The Department accepts that, notwithstanding the absence of a specific provision for apportionment of profits in the IRO, there are certain situations in which an apportionment of the chargeable profits is appropriate. The example of manufacturing profits has already been explained above. A further example is service fee income where the services are performed partly in Hong Kong and partly outside. On the other hand, as has been mentioned in paragraph 24 above, the Department does not find an apportionment of trading profits is required”.  If the IRD no longer follows principles set out in Para 23, what is the reason for sticking to the principle of no apportionment of trading profits?

    This case reflects the IRD’s approach to the territorial concept of taxation has changed.   Numerous taxpayers may currently be in dispute with the IRD over the source of profit.  When facing unreasonable assessments, many taxpayers may prefer to settle the case in view of the long appeal time and high costs.  It is likely that this case of Co A will be cited by the IRD in future disputes with taxpayers.  The Financial Secretary, Mr. Paul Chan, said at the end of his speech that “Our tax system is simple and clear, and its implementation is fair and consistent…we absolutely do not want to gradually make our tax system more complex, which would lead to disproportionate increase in tax administrative costs and corporate compliance costs”.  In the face of today’s environment, is Hong Kong’s tax system still territorial based, easy and straightforward, apply equally to all, consistent in implementation, and low in compliance costs?  Can Hong Kong continue to be, in the eyes of the Financial Secretary, the world’s premier business location?  In the environment of BEPS, it seems that it is time to consult the Hong Kong people for a tax reform.

    Tax Tips :

    1. The case of A Co could have been resolved satisfactorily during the enquiry stage, and maintain that the profits were arising in or derived from outside Hong Kong.  There are certain techniques in answering queries from the IRD; other than pointing out the relevant legal provisions and cases, if the IRD’s views are unreasonable, one had to point out directly the issue, such as asking the above question “If there is another identical case but without the “Three Direct Links” background (for example, replace Taiwan Co with a UK company), would the IRD argue the same?”.  Besides the source of profit, the IRD’s approach in determining revenue and capital expenditures can sometimes be unreasonable too.  As taxpayer or tax representative one has to know how to close the issue at an early stage.  
    2. The case also has Mainland tax implications.  Co A would likely have created a permanent establishment in the Mainland (or even in Taiwan), and the Mainland tax authorities could impose corporate income tax at 25% on the profits of Co A (and Co A should claim the profits tax suffered in this appeal case from the IRD under the Hong Kong-Mainland Double Tax Arrangement?).  Further, as Co A has no substance in Hong Kong, the IRD may not issue the Certificate of Residence to Co A, and the Mainland authorities would unlikely consider Co A as the beneficial owner of dividend from Mainland Co, so that Co A would not be able to enjoy the 5% dividend withholding tax rate under the Double Tax Arrangement but would need to pay 10% instead.  Hong Kong taxpayers conducting similar business should learn from the case in how to improve the overall arrangement.  

    Author: Edwin Bin

    Ref:

    FS’ Speech at Tax Summit (Chinese only): http://www.info.gov.hk/gia/general/201710/23/P2017102300746.htm

    D25/14: http://www.info.gov.hk/bor/tc/docs/D2514.pdf

    DIPN 21: https://www.ird.gov.hk/eng/pdf/e_dipn21.pdf


  • Tax Tips (4) – Is the Two-Tier Profits Tax System Really Going to Benefit SMEs?

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on January 30, 2018: https://manageyourtax.com/HKEJ Forum 4).

    The current Government has repeatedly mentioned about “New Fiscal Philosophy,” and the “New Direction for Taxation” plays a key role in realising this new philosophy.  The most eye-catching new tax initiative must be the two-tier profit tax system.  The Government introduced the two-tier system of profits tax in the Inland Revenue (Amendment) (No. 7) Bill 2017 (the “Bill 7”) on the 29th of December 2017 and it is scheduled to be implemented in Fiscal Year 2018/19.  Most people would know that the two-tier profit tax system introduced the lower 8.25% tax rate (half of the normal rate) on the first HK$2 million of assessable profits each year (a tax saving of HK$165,000 if the annual taxable profit of a company reaches HK$2 million), and each Group can only designate one company within the group to enjoy preferential tax rate.  Is this design good or bad?

    First look at what the Government says.  The two-tier system was first proposed by Ms Carrie Lam in her campaign for the Chief Executive of Hong Kong for the purpose of “reducing the tax burden on enterprises (especially the small, medium and start-up enterprises)”.  After Ms Lam’s election victory, the Government started to study the implementation, and put forward in the 2017 Policy Address that “To ensure that the tax benefits will target SMEs, we will introduce restrictions such that each group of enterprises may only nominate one enterprise to benefit from the lower tax rate”.  According to the blog “Thinking about the 2018/19 Budget” released by the Financial Secretary, Mr Paul Chan, on January 7, 2018 (there is no English version), taking the 2015/16 assessment year as an example, there are about 100,000 companies paying Hong Kong Profits Tax, with distribution as follows:

    (Source: “Thinking about the 2018/19 Budget” http://www.fso.gov.hk/chi/blog/blog070118.htm )

    The information can be grouped as follows:

    The number of companies with assessable profits:

    0 – HK$2m: 82,500 (~80%)

    >HK$2m: 21,300 (~20%)

    Speaking at the “Summit on New Directions for Taxation” held in October last year, Financial Secretary Mr. Paul Chan said that if every company is allowed to enjoy the preferential profits tax rate, the Treasury would reduce its tax revenue by about HK$7.1 billion.  The Financial Secretary also mentioned that “as the cost of setting up and maintaining a company in Hong Kong is relatively low, there would be tax revenue loss if groups spin-off companies”.  In addition, “the United Kingdom introduced a similar taxation measure more than a decade ago, the corporation tax on the first £10,000 of profits was 0% with the amount exceeding that to be subject to tax.  In the two years since the introduction of the initiative, new local company formation increased 40% and 20% respectively, and the UK abolished the arrangement after some years”, “therefore, after due consideration, we decided to include some provisions to such that each group is only allowed to nominate one company to benefit from the lower tax rate, which helps to concentrate tax incentives on SMEs on the one hand and at the same time make it impossible for enterprises to spin off new companies for tax concessions”.  According to the statement made by the Secretary for Financial Services and the Treasury Bureau Mr James Lau, JP, on the second reading of “Bills 7” at the Legislative Council on January 10, “Assuming that 20% of the taxpayers are related enterprises, the implementation of the proposal will result in annual government tax revenue reduction of approximately HK$5.8 billion”.  

    The question is, is this estimate made based on the assumption that around 20% of companies have taxable profits exceeding HK$2 million?  That is, the Government assumes that all enterprises with an assessable profit of more than HK$2 million are large group enterprises and the rest (80%) are SMEs or start-ups and can enjoy a low tax rate?

    I have no objection to two-tier profits tax. The level of tax rates should be determined based on various factors including the international environment and consider the local policy direction.  Tax increases, tax reduction or two-tier system can all achieve policy objectives.  The key is to be clear about the objective.  The objective of this reform is obviously to reduce the tax burden on SMEs and start-up companies.  The only question, therefore, is whether the two-tier profits tax system as proposed by “Bill 7” can achieve this objective.

    The “connected enterprise” mentioned by Secretary Lau should be the “connected entity” mentioned in Bill 7.  The definition of “connected entity” in simple terms is an entity that controls another entity or is jointly controlled by another entity or natural person.  The threshold of “control” is more than 50% (for details, see Article 4 of Bill 7 for the new S.14AAB).  Accordingly, if a businessman sets up two companies to run small businesses, one is a fashion retail shop which he holds 90% interest (Friend A holds 10%), and a snackfood trading company for which he holds 60% (Friend B holds 40%), under the Bill 7 the two companies are “connected entities”, so the businessman can only choose one company to enjoy the preferential tax rate, how should he choose without upsetting one of his friends?

    As a matter of fact, many small business operations require more than one company to operate.  This is for business reasons such as licenses, the composition of shareholders, business categories, and risks containment.  Are these small businesses “large enterprises” in the Government’s eyes?  On the other hand, according to my own personal experience, many companies that belong to the same group have assessable profits of well under HK$2 million (in fact, anyone who has handled Hong Kong profits tax compliance for large and small groups would know), thus I would say Secretary Lau’s estimation is too conservative.  Since there is no concession for large and small enterprises, I believe the number of companies that can enjoy the preferential tax treatment under the two-tier profits tax system would be very small.  The annual cost of revenue to the Government should be well below HK$5.8 billion.

    The UK Example

    The provision that only allows one of the “connected entities” to enjoy the lower tax rate should be the anti-avoidance measure (Specific Anti-avoidance Rule) mentioned by the Financial Secretary to prevent companies from abusing the tax preference by splitting up profitable ones.  The Financial Secretary also mentioned the example of the UK.  According to the Institute for Fiscal Studies in the UK, the measure was introduced in 2000 with an applicable tax rate of 10% on the profits of the first £10,000 for the first two years (2000 and 2001) and zero for the next four years (a specific anti-avoidance provision was introduced), and the measure was abolished after 2005.  The purpose of introducing the low tax rate in those days was to encourage entrepreneurship and increase employment opportunities.  However, it also unexpectedly encouraged the conversion of existing self-employed persons into corporate forms, which, in addition to saving corporate tax, also reduced National Insurance contribution.  As for splitting up of companies to enjoy the low rate, although not impossible, I was not able to find materials covering this point.  More importantly, there was no “General Anti-Avoidance Rule” (GAAR) in the UK at that time (GAAR was introduced in the UK in 2013), meaning that the HMRC could not prosecute a company for entering into transactions or arrangement for the sole or dominant purpose of obtaining a tax benefit.  On the contrary, Hong Kong has always had a GAAR (Section 61A of the Inland Revenue Ordinance).

    When the Hong Kong Inland Revenue Department (“IRD”) considers any transaction has been entered into or effected and that transaction has, or would have had, the effect of conferring a tax benefit on a person, and it would be concluded that the person, or one of the persons, who entered into or carried out the transaction, did so for the sole or dominant purpose of enabling the relevant person, either alone or in conjunction with other persons, to obtain a tax benefit, the IRD shall assess the liability to tax of the relevant person as if the transaction or any part thereof had not been entered into or carried out; or in such other manner as the assistant Commissioner considers appropriate to counteract the tax benefit which would otherwise be obtained.  In other words, even if there is no Special Anti-avoidance Rule in Bill 7, when an enterprise, regardless of its size, sets up a company to split its profits in order to enjoy a lower tax rate, the IRD can apply GAAR to counteract the benefits and may impose a fine.  Any enterprise that avoids tax knowingly would certainly calculate the cost-effectiveness of arrangement.  Although it is not ruled out that enterprises may enter into an arrangement for saving just HK$165,000 (which would be the case only if the company has assessable profits of more than HK$4 million), apart from facing GAAR, dividing a business into two business is actually not easy in practice.  For example, a businessman operates a fashion retail shop and signed a five-year lease for the premises.  If he now wants to split into two companies to operate the same shop, he will need to seek consent from the landlord.  If you were the landlord would you agree to it unconditionally?  Then the business owner needs to bill customers separately, employees shall be hired by two companies, and vendors shall contract with two companies?  To save HK$165,000 for doing all these the business owner will likely end up losing money.  Of course, another approach is to maintain the operation of a company and to split the account into another company by means of internal allocation and accounting entries.  But would this pass the sharp eyes of the IRD assessors?

    As to the question “Can the two-tier profits tax system proposed in Bill 7 help reduce the tax burden on SMEs and start-ups?”, my answer to “No”.  This is because of the Special Anti-avoidance Rule contained in which is restrictive to SMEs and start-ups.  This provision is complicated and deviates from the requirements of a good tax system.  One of the criteria for a good tax system is “fairness”.  “Fairness” means that tax treatment should be the same for different taxpayers doing the same thing.  It is fair for everyone to pay a high tax rate for higher profits, but it is unfair if benefits would be denied for being part of a group.  In fact, groups that set up a company to operate a business is no different from an SME, the group also needs to invest capital, hire qualified personnel and take risks, and the difference is that large groups can generally be able to do these more efficiently.  Perhaps “fairness” in the eyes of the government is that all large corporations and small enterprises can only choose one company to enjoy the benefits without discrimination.  Hong Kong does not have a group consolidation profits tax regime, but the lower tier profits tax rate is applied on a group basis, so there seems to be a conflict in administration.

    In fact, there are quite a lot of channels for the Government to use financial means to help alleviate the burden on SMEs or start-ups, some of which may not have any assessable profit at all.  The Government could consider providing low-cost office space or industrial premises consider help reduce their operating costs, and even set up some special support funds for eligible enterprises or small size groups to apply?  When these enterprises become tax paying, the Government will recover the investments through tax revenue.

    Tax Tips: If a business earns HK$2 million profits a year, but it is actually earned through four companies (each HK$500,000), according to the two-tier system, the business can only save HK$41,250 (instead of HK$165,000).  It is time for SMEs to review the assessable profits of its companies and to choose one to enjoy the preferential tax rate in the future.  If commercially viable with the business transformation, businesses have the opportunity to enjoy the HK$165,000 benefits in full. The premise, of course, is to strictly abide by the requirements of the tax regulations.


    Author: Edwin Bin

    Ref:

    Inland Revenue (Amendment) (No. 7) Bill 2017:

    http://www.gld.gov.hk/egazette/pdf/20172152/es32017215230.pdf

    Carrie Lam Election Manifesto:

    https://www.carrielam2017.hk/media/my/2017/01/Manifesto_e_v2.pdf

    2017 Policy Address:

    https://www.policyaddress.gov.hk/2017/eng/policy_ch03.html

    Tax Summit Speech by FS (Chinese only):

    http://www.info.gov.hk/gia/general/201710/23/P2017102300746.htm

    Secretary for FSTB Speech (Chinese only):

    http://www.fstb.gov.hk/tb/tc/docs/sp20180110a_c.pdf

    Institute For Fiscal Studies:

    https://www.ifs.org.uk/budgets/gb2008/08chap11.pdf

    https://www.ifs.org.uk/uploads/publications/bns/bn09.pdf

    UK General Anti-Avoidance Rules:

    https://www.gov.uk/government/uploads/system/uploads/attachment_data/file/602420/HMRC_GAAR_Guidance_Parts_A_B_and_C_-_with_effect_from_30_January_2015.pdf