It was mentioned in the last issue that Hong Kong has become a part of the OECD BEPS “Inclusive Framework” and published the Inland Revenue (Amendment) (No. 6) Bill 2017 (the “Bill”) in the Gazette on 29 December 2017, in order to implement the “Minimum Standards” for the BEPS program in the Fiscal Year 2018/19. The Bill was passed in the Legislative Council on 4 July 2018. This issue examines how the implementation of the BEPS Action 13 “Transfer Pricing Documentation and Country-by-Country Reporting” under the “Minimum Standard” will affect Hong Kong taxpayers.
Large Hong Kong Multinational Corporations
Many large Hong Kong multinational corporations (“MNC”, Hong Kong resident groups headquartered in Hong Kong) have invested overseas. Many MNCs have been busy with complying with the BEPS Actions because they are subject to the overseas tax laws and many countries, especially the European countries, have already amended the tax regulations to incorporate the BEPS Actions. If their annual consolidated group revenues exceeded 750 million euros, the MNCs would likely have prepared the Country-by-Country Reporting (“CbCR”) and would have been filing notifications in different countries beginning the end of 2016, and by the end of 2017 file the CbCR in probably more than one country. In addition, they also need to prepare the Master File for transfer pricing, ready for inspection by tax bureaus worldwide. The Bill sets the threshold for CbCR at HK$6.8 billion. If the Bill is passed on schedule, Hong Kong’s major MNCs will have to decide whether they need to prepare the 2018 CbCRs based on whether their 2017 consolidated revenue exceeded HK$6.8 billion. By 31 December 2019, “Hong Kong Ultimate Parent Entity” shall submit the CbCR to the Hong Kong Inland Revenue Department (“IRD”). To make it more complex, MNCs need to assess whether Hong Kong can automatically exchange their CbCRs to the tax bureaus of their overseas operations. If not, these MNCs may also submit CbCRs individually in different countries, which can be an exhausting exercise.
What is CbCR? Anyone reading through the Bill would not be able to find out the contents of CbCR. This is because the Bill has incorporated the OECD BEPS Action 13 “Transfer Pricing Documentation and Country-by-Country Reporting” and the related guidance into the Bill. In other words, BEPS Action 13 and the related guidance will become part of the Inland Revenue Ordinance. I could find a web page on the IRD website about CbCR and its reporting, which is in English only (https://www.ird.gov.hk/eng/tax/dta_cbc.htm ). Readers who wish to review the Chinese version of Action 13 may visit the website of the Mainland State Administration of Taxation: (http://210.6.198.19/cache/www.chinatax.gov.cn/download/2015g20/13.pdf?ich_args=965775e28ef3a1b869ada2ffea908603_1_0_0_8_c06c0205980d5c095e5e83ebbe754d450928ff6d3a6067cd1e8eb71f883e6b97_9902a380a9710ef560c71907789f9d38_1_0&ich_ip= )。
To facilitate Readers’ understanding, I quickly summarise CbCR as follows. CbCR is a report consisting of three tables. Table 1 requires the reporting MNC to list out, by tax jurisdiction, the aggregate figures of various attributes of all entities of the MNC in that tax jurisdiction. The attributes are: (1) Revenue from Unrelated Party; (2) Revenue from Related Party; (3) Total Revenue; (4) Profits before Tax; (5) Income Tax Paid (cash basis); (6) Income Tax Accrued; (7) Stated Capital; (8) Accumulated Earnings; (9) Number of Employees; and (10) Tangible Asset (other than cash and cash equivalent). For example, an MNC group has 100 entities in Mainland China, then on the CbCR on the row for “Mainland China”, the MNC shall report the aggregated figure of each attribute for the 100 entities, translated into the reporting currency of the CbCR. Table 2 lists out every entity of the MNC group and report their tax residencies and main business activities. Table 3 is for reporting any other information such as exchange rates that helps users of the CbCR to better understand the report.
The CbCR may appear to be straight-forward, but if the MNC is very large, with operations in many jurisdictions and internally use more than one accounting software, it is not an easy task to compile all the figures correctly. Although the OECD has been issuing further guidance (while MNCs are already preparing the reports), there are numerous challenges faced by MNCs in preparing the CbCR. In the last issue of Tax Tips, it was mentioned that the concept of the BEPS program is to establish a modern international tax framework that allows companies to pay tax at the location of their real business activities and value creation. CbCR is designed to let all tax bureau worldwide to have a bird’s-eye view on the MNC group’s revenue, profits, assets, and people, so as to assess if there are tax risks (potential tax avoidance activities). Since the Bill proposed to penalise the MNC (and also the service provider engaged to prepare the CbCR for the MNC) for incorrect CbCR, the IRD should issue further detailed guidance on one hand, and be lenient to MNCs on the other hand, at least for the initial years, taking into account the difficulties in preparing the CbCR error-free.
All Hong Kong Companies
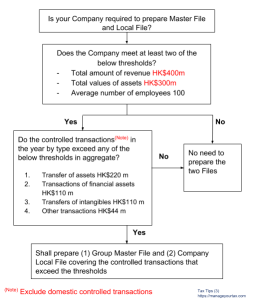
Large Hong Kong MNCs and many Small and Medium-Sized Enterprises (“SMEs”) will likely be required to prepare transfer pricing Master Files and Local Files. According to the Bill, if the company satisfies two of the below three conditions, it will have to prepare Local File for itself and Master File for the Group:
- Total Amount of Revenue: HK$400 million
- Total Value of Assets: HK$300 million
- Average number of employees: 100
Notwithstanding, SMEs would be able to reduce compliance costs if they satisfy conditions set out in the Bill. Based on the type of transaction, provided that the amounts of controlled transactions are under the thresholds, no transfer pricing documentation shall be prepared for that relevant transaction. Insofar as domestic transactions between associated persons that do not give rise to actual tax difference (or domestic transactions involving non-arm’s length loans (e.g. interest-free loans) that are not carried out in the ordinary course of money lending or intra-group financing business), and provided that such transactions do not have a tax avoidance purpose, then the relevant persons will not be obliged to compute the income or loss arising from these transactions on the basis of the arm’s length provision in their tax returns and no corresponding assessment on that basis will be made by IRD. The Bill has therefore exempted domestic transactions from the preparation of transfer pricing documentation. As a related matter, therefore, the volume of domestic controlled transaction would also be disregarded in assessing if the company has breached the nature and volume threshold for preparing the documentation. If the company’s controlled transactions fall below all four thresholds, the company is exempt from preparing the Local File and Group Master File:
- Transfers of properties (whether movable or immovable but excluding financial assets and intangibles) HK$220 million
- Transactions in respect of financial assets HK$110 million
- Transfers of intangibles HK$110 million
- Other transactions HK$44 million
I prepared the below diagram to facilitate Readers’ understanding.
These thresholds seem clear, but as always, the devils are in the details. For example, what is meant by “total amount of revenue”? Is it only the top line revenue in the profit and loss account, or would it also include items such as asset disposal gains, exchange gains, interest income and dividend income? “Total value of assets” is relatively simple, but do not forget that if an enterprise leases assets under an operating lease, according to IFRS 16, to be implemented on January 1, 2019, lessees may need to book the value of the assets and companies are therefore more likely than before in breaching the threshold. As for the type of the company’s annual related party transactions, in the case of related party loans, is the threshold based on the loan amount or interest amount? It seems that some techniques are required in classifying related party transactions in order to decide whether the relevant transfer pricing documentation shall be prepared. To avoid any controversy and inconvenience, the tax authorities should formulate relevant guidelines as soon as possible.
As to the deadlines for preparing the Master File and Local File, the Bill requires such documents to be completed within 9 months after the end of the accounting period. Time is tight. Companies need to understand that preparing the two files are just the beginning, the critical part is what would the IRD do with the files. Also, the Bill is silent on how the provisions work together with the territorial system of taxation in Hong Kong. Future Tax Tips will look into the area.
A couple of side-points: during the BEPS Consultation in 2016 organised by the Financial Services and Treasury Bureau (“FSTB”), the thresholds of Total Amounts of Revenue and Total Values of Assets were proposed to be HK$100 million, without the exemption conditions mentioned above. Myself, various business and tax organisations reflected to the FSTB that the thresholds were too low, and that companies with small amounts of related party transactions should not be required to prepare the documentation. The Bill has reflected the comments made. On the other hand, as many Hong Kong companies have dealings with related parties in Mainland China, the above thresholds of controlled transaction were determined with reference to the thresholds in Mainland China for preparing transfer pricing documentation, so if companies have prepared documentation to satisfy the rules in Mainland China, the documents can be easily adapted to comply with the Hong Kong rules.
Tax Tips:
(1) : CbCR does not only apply to Hong Kong Ultimate Parent Entity. If a foreign group reaches the CbCR threshold, the Hong Kong Constituent Entities are required to comply with the Hong Kong notification rules and perhaps need to file the CbCR with the IRD.
(2) : The exemption of domestic transactions between associated persons that do not give rise to actual tax difference and do not have a tax avoidance purpose from the obligation to compute the income or loss arising from these transactions on the basis of the arm’s length provision in their tax returns and the exemption of such transactions from the preparation of transfer pricing documentation would substantially reduce the administrative burden faced by companies. The Hong Kong Government estimated that around 1,000 enterprises, representing less than 2% of the total number of profits tax-paying enterprises in Hong Kong, would be required to prepare the Master File and Local File. Notwithstanding, all businesses should immediately check whether they would exceed the threshold (including considering the accounting standards changes) and prepare the relevant transfer pricing documents to meet the new requirements. As the definition of the thresholds are not clear, if the company is close to the thresholds, the conservative approach is to assume that the thresholds have been breached. More important is to prepare the supporting documents such as contracts, because in order to analyse the transaction for transfer pricing purposes one has to refer to the contract to determine the nature of the transaction and analyse the functions and risks borne by the parties to the transaction. It may be too late to start preparing in 2019.
Contact Us
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on January 24, 2018: https://manageyourtax.com/HKEJ Forum 3. As the Bill was passed in the Legislative Council on 4 July 2018 with amendments, this Tax Tips is updated to reflect the changes).
Ref:
The Bill: http://www.gld.gov.hk/egazette/pdf/20172152/es32017215229.pdf
Report of the Bills Committee dated 25 June 2018: https://www.legco.gov.hk/yr17-18/english/bc/bc02/reports/bc0220180704cb1-1140-e.pdf
FSTB BEPS Consultation Paper:
http://www.fstb.gov.hk/tb/en/docs/BEPS-ConsultationPaper-e.pdf
FSTB BEPS Consultation Report: http://www.fstb.gov.hk/tb/en/docs/BEPS-ConsultationReport-e.pdf
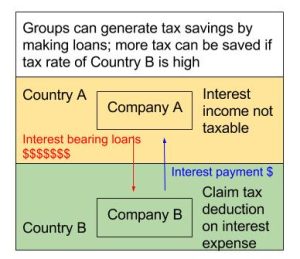 A small sidetrack before we continue. The example of interest-bearing loans in the last issue of Tax Tips [see attached diagram] is, in fact, Case 1.1 of the BEPS Action 2, “Neutralising the Effects of Hybrid Mismatch Arrangements”. In Action 2, OECD proposed that country B should not allow interest deduction. If Country B allows the interest expense deduction, Country A should regard the income as taxable income in order to “ensure coherence of domestic laws and regulations on cross-border transactions”. In short, OECD is asking jurisdictions to amend the tax code. Logically, Country A and Country B themselves must determine their own tax treatment according to their laws and may be tax cases (where applicable). The laws, regulations and tax cases must have been formulated by history, circumstances and people’s empowerment of the respective countries. Large and small enterprises are only acting according to the laws and regulations. Going forward, would all jurisdictions determine their tax treatments based on how the other countries rule?