manageyourtax.com

Tag: #TwoTierProfitsTax

  • Tax Tips (22) – Dealing with International Tax Cooperation

    Tax Tips (22) – Dealing with International Tax Cooperation

    A multilateral tax cooperation mechanism under the Belt and Road Initiative (BRI), the Belt and Road Initiative Tax Administration Mechanism (BRITACOM) which includes tax authorities from 34 countries and regions, was established on 18 April 2019. The reported aim of BRITACOM is to facilitate cross-border trade and investment along BRI routes by expanding tax dispute resolution activities, increasing transparency, streamlining compliance and digitizing filing.  An office will be opened in Beijing to help facilitate these goals.

    Since the BRI consists primarily of Chinese outbound investment in infrastructure projects in the participating countries, BRITACOM will likely function more in facilitating outbound Mainland Chinese entities’ local tax compliance and dispute resolution when engaged in such projects. BRITACOM will be different from the various anti-tax avoidance initiatives of the OECD and other international organisations.

    International Effort in Anti-Tax Avoidance

    The most well-known international effort against tax avoidance is the Base Erosion and Profit Shifting (BEPS) project. The 15 BEPS Actions issued in October 2015 challenge tax avoidance practices by large Multinational Enterprises (“L-MNEs”) by amending the global tax treaties, increasing disclosure and transparency, introducing new documentation in transfer pricing, countering harmful tax practices, lowering threshold of permanent establishment recognition, investigating into new form of taxation for digital services and toughening interest deduction rules. The primary aim of BEPS is to ensure that the international tax rules do not facilitate the shifting of corporate profits away from the real economic activity and value creation are taking place. Many of these Actions have been implemented already, the latest being the Economic Substance Law (with the BVI just issued the Draft Economic Substance Code).

    In addition, the OECD has stepped up efforts in international cooperation on tax matters in recent years. Heads of tax administrations meet regularly at the Forum of Tax Administration (FTA). Cross-border tax avoidance intelligence is shared among tax offices under the Joint International Taskforce on Shared Intelligence and Collaboration (JITSIC). The International Compliance Assurance Programme (ICAP) invites large MNEs to engage voluntarily with tax administrations from 17 jurisdictions (expanded from 8 when the pilot began in January 2018). Tax Inspectors Without Borders sends experience tax officials to train those in developing countries to perform tax audits on MNEs.

    The United Nation, the World Bank, the International Monetary Fund, and the European Unions are also very active in introducing new initiatives in combating tax avoidance.

    Large MNEs have Acted

    Many L-MNEs have already started restructuring back in around 2013/14 in view of the disclosure requirements especially the Country-by-Country Reporting (CbCR). In the past, many L-MNEs housed the intellectual properties (“IP”) in tax haven jurisdictions earning untaxed royalties or have captive insurance companies there to provide insurance coverage to group companies in order to receive untaxed income while the group companies could take a tax deduction. Smart L-MNEs would have restructured early so that no tax office would have the opportunity to ask the sensitive questions. Their most immediate challenge to the L-MNEs would likely be dealing with the economic substance law in the tax haven countries, especially those that have been acting as funding vehicles.

    Smaller MNEs – Act Now

    L-MNEs have internal tax resources to help them manage tax risks in this rapidly changing tax environment. What about the Small and Medium Size MNEs (S-MNEs) that do not have in-house tax people? They obviously have to rely on external tax consultants. The key is to identify the right consultants to do the following two things:

    1. Review the existing structure, operations and arrangements

    The objective of such review is to identify tax risks and opportunities currently embedded in the group structure and operations. The author had seen a group missing out the 50/50 offshore claim in the Hong Kong profits tax filing on a contract manufacturing arrangement. In another case, a Hong Kong-based listed group devoted resources in Hong Kong to help the overseas affiliates in high tax countries to become highly profitable but they do not realise that they should recoup the costs incurred in Hong Kong via transfer pricing in order to align with the commercial reality and reduce the group’s effective tax rate. These can be dug out and properly addressed in order to create legitimate tax saving.

    Some groups have not paid attention to documentation of decision making and thereby creating risks of being regarded as tax resident in jurisdictions unexpectedly. The old model of cost-plus remuneration of agents may now be exposed to permanent establishment risks. Some have ignored the documentation of substance. The impact of the Economic Substance Law introduced by the tax havens such as the British Virgin Islands (BVI) must be properly analysed with a set of action determined to address the issue.

    To be a good manager, issues should be addressed and resolved upfront so that the expectation of shareholders and directors of the group/company is well-managed. The review should be conducted by professionals with solid technical and business experience. There are well-qualified tax advisors in the market to do the work at competitive rates and high efficiency to deliver substantial value to the groups.

    Often the finance managers of the groups/companies prefer to stick their heads into the sand instead of dealing with the problems because they don’t want to take the blame for issues uncovered by the seasoned tax advisors. It is thus important for the directors or even the shareholders to realise what the current tax environment is like and take initiative in carrying out the review. At the end of the day, if the hidden tax exposures are not cleared before they crystalise, the group/company, the directors and shareholders would be badly hurt.

    2. Seek on-going tax support especially on documentation

    Having identified and dealt with past issues, it is important that no such issue will arise again in the future. This can be achieved by retaining the tax advisor to review transactions or documentation as and when required, just a family doctor caring for the health of the family. For example, sometimes the auditors, being unaware of the tax exposure created, may make disclosures in the audited financial statements that are unnecessary and sometimes even harmful to the tax arrangement of the company. For listed companies, they should be very careful in the disclosures in the annual reports.

    Board papers are crucial. It is direct evidence of management and control which is one of the key factors in determining substance and tax residency. Tax advisors play an important role in advising who should be on the board of each company, location of board meetings and review the board papers.

    Also, management should be made aware of tax law changes and new cases that affect their business. Questions they should ask, or proactively addressed by the tax advisor, include:

    • What are the benefits of the new tax incentives introduced in Hong Kong such as the two-tier tax system to the group?
    • Should something be done about intellectual property in view of the new Section 15F of the Inland Revenue Ordinance?
    • What should the group do in view of the Beneficial Ownership rules in Mainland China to ensure that the benefits can be obtained?
    • Is CbCR going to affect the group?
    • The boss travels to Mainland China often, is he exposed to the Chinese Individual Income Tax on worldwide income?
    • Is the loan financing of a foreign subsidiary compliant with transfer pricing or will it be challenged by the tax authorities?
    • In view of the tax cases, can the Hong Kong company still lodge an offshore claim on its trading profits? How to ensure a successful claim?
    • How to structure a new acquisition? Is the Multilateral Convention to Implement Tax Treaty Related Measures to Prevent BEPS (commonly referred to as the Multilateral Instrument) going to affect the group? Would all the new tax rules introduced bring higher tax exposures in a share deal and how to mitigate such risks?

    The list of questions can be much longer.

    Tax Tips

    It is time for the smaller groups to gear up the tax risk monitoring and compliance, and ensure that structures are sustainable in the medium term. The BEPS Project is at the implementation stage and it will not be long before OECD reviews the achievement and point to the next target: the S-MNE groups. The time to act is NOW.


    Contact Us


    Ref:

    BRITACOM: http://www.chinatax.gov.cn/eng/n2367751/c4273658/content.html
  • Tax Tips (4) – Is the Two-Tier Profits Tax System Really Going to Benefit SMEs?

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on January 30, 2018: https://manageyourtax.com/HKEJ Forum 4).

    The current Government has repeatedly mentioned about “New Fiscal Philosophy,” and the “New Direction for Taxation” plays a key role in realising this new philosophy.  The most eye-catching new tax initiative must be the two-tier profit tax system.  The Government introduced the two-tier system of profits tax in the Inland Revenue (Amendment) (No. 7) Bill 2017 (the “Bill 7”) on the 29th of December 2017 and it is scheduled to be implemented in Fiscal Year 2018/19.  Most people would know that the two-tier profit tax system introduced the lower 8.25% tax rate (half of the normal rate) on the first HK$2 million of assessable profits each year (a tax saving of HK$165,000 if the annual taxable profit of a company reaches HK$2 million), and each Group can only designate one company within the group to enjoy preferential tax rate.  Is this design good or bad?

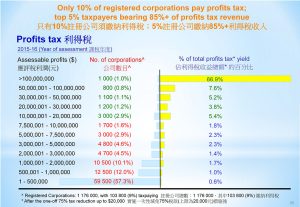
    First look at what the Government says.  The two-tier system was first proposed by Ms Carrie Lam in her campaign for the Chief Executive of Hong Kong for the purpose of “reducing the tax burden on enterprises (especially the small, medium and start-up enterprises)”.  After Ms Lam’s election victory, the Government started to study the implementation, and put forward in the 2017 Policy Address that “To ensure that the tax benefits will target SMEs, we will introduce restrictions such that each group of enterprises may only nominate one enterprise to benefit from the lower tax rate”.  According to the blog “Thinking about the 2018/19 Budget” released by the Financial Secretary, Mr Paul Chan, on January 7, 2018 (there is no English version), taking the 2015/16 assessment year as an example, there are about 100,000 companies paying Hong Kong Profits Tax, with distribution as follows:

    (Source: “Thinking about the 2018/19 Budget” http://www.fso.gov.hk/chi/blog/blog070118.htm )

    The information can be grouped as follows:

    The number of companies with assessable profits:

    0 – HK$2m: 82,500 (~80%)

    >HK$2m: 21,300 (~20%)

    Speaking at the “Summit on New Directions for Taxation” held in October last year, Financial Secretary Mr. Paul Chan said that if every company is allowed to enjoy the preferential profits tax rate, the Treasury would reduce its tax revenue by about HK$7.1 billion.  The Financial Secretary also mentioned that “as the cost of setting up and maintaining a company in Hong Kong is relatively low, there would be tax revenue loss if groups spin-off companies”.  In addition, “the United Kingdom introduced a similar taxation measure more than a decade ago, the corporation tax on the first £10,000 of profits was 0% with the amount exceeding that to be subject to tax.  In the two years since the introduction of the initiative, new local company formation increased 40% and 20% respectively, and the UK abolished the arrangement after some years”, “therefore, after due consideration, we decided to include some provisions to such that each group is only allowed to nominate one company to benefit from the lower tax rate, which helps to concentrate tax incentives on SMEs on the one hand and at the same time make it impossible for enterprises to spin off new companies for tax concessions”.  According to the statement made by the Secretary for Financial Services and the Treasury Bureau Mr James Lau, JP, on the second reading of “Bills 7” at the Legislative Council on January 10, “Assuming that 20% of the taxpayers are related enterprises, the implementation of the proposal will result in annual government tax revenue reduction of approximately HK$5.8 billion”.  

    The question is, is this estimate made based on the assumption that around 20% of companies have taxable profits exceeding HK$2 million?  That is, the Government assumes that all enterprises with an assessable profit of more than HK$2 million are large group enterprises and the rest (80%) are SMEs or start-ups and can enjoy a low tax rate?

    I have no objection to two-tier profits tax. The level of tax rates should be determined based on various factors including the international environment and consider the local policy direction.  Tax increases, tax reduction or two-tier system can all achieve policy objectives.  The key is to be clear about the objective.  The objective of this reform is obviously to reduce the tax burden on SMEs and start-up companies.  The only question, therefore, is whether the two-tier profits tax system as proposed by “Bill 7” can achieve this objective.

    The “connected enterprise” mentioned by Secretary Lau should be the “connected entity” mentioned in Bill 7.  The definition of “connected entity” in simple terms is an entity that controls another entity or is jointly controlled by another entity or natural person.  The threshold of “control” is more than 50% (for details, see Article 4 of Bill 7 for the new S.14AAB).  Accordingly, if a businessman sets up two companies to run small businesses, one is a fashion retail shop which he holds 90% interest (Friend A holds 10%), and a snackfood trading company for which he holds 60% (Friend B holds 40%), under the Bill 7 the two companies are “connected entities”, so the businessman can only choose one company to enjoy the preferential tax rate, how should he choose without upsetting one of his friends?

    As a matter of fact, many small business operations require more than one company to operate.  This is for business reasons such as licenses, the composition of shareholders, business categories, and risks containment.  Are these small businesses “large enterprises” in the Government’s eyes?  On the other hand, according to my own personal experience, many companies that belong to the same group have assessable profits of well under HK$2 million (in fact, anyone who has handled Hong Kong profits tax compliance for large and small groups would know), thus I would say Secretary Lau’s estimation is too conservative.  Since there is no concession for large and small enterprises, I believe the number of companies that can enjoy the preferential tax treatment under the two-tier profits tax system would be very small.  The annual cost of revenue to the Government should be well below HK$5.8 billion.

    The UK Example

    The provision that only allows one of the “connected entities” to enjoy the lower tax rate should be the anti-avoidance measure (Specific Anti-avoidance Rule) mentioned by the Financial Secretary to prevent companies from abusing the tax preference by splitting up profitable ones.  The Financial Secretary also mentioned the example of the UK.  According to the Institute for Fiscal Studies in the UK, the measure was introduced in 2000 with an applicable tax rate of 10% on the profits of the first £10,000 for the first two years (2000 and 2001) and zero for the next four years (a specific anti-avoidance provision was introduced), and the measure was abolished after 2005.  The purpose of introducing the low tax rate in those days was to encourage entrepreneurship and increase employment opportunities.  However, it also unexpectedly encouraged the conversion of existing self-employed persons into corporate forms, which, in addition to saving corporate tax, also reduced National Insurance contribution.  As for splitting up of companies to enjoy the low rate, although not impossible, I was not able to find materials covering this point.  More importantly, there was no “General Anti-Avoidance Rule” (GAAR) in the UK at that time (GAAR was introduced in the UK in 2013), meaning that the HMRC could not prosecute a company for entering into transactions or arrangement for the sole or dominant purpose of obtaining a tax benefit.  On the contrary, Hong Kong has always had a GAAR (Section 61A of the Inland Revenue Ordinance).

    When the Hong Kong Inland Revenue Department (“IRD”) considers any transaction has been entered into or effected and that transaction has, or would have had, the effect of conferring a tax benefit on a person, and it would be concluded that the person, or one of the persons, who entered into or carried out the transaction, did so for the sole or dominant purpose of enabling the relevant person, either alone or in conjunction with other persons, to obtain a tax benefit, the IRD shall assess the liability to tax of the relevant person as if the transaction or any part thereof had not been entered into or carried out; or in such other manner as the assistant Commissioner considers appropriate to counteract the tax benefit which would otherwise be obtained.  In other words, even if there is no Special Anti-avoidance Rule in Bill 7, when an enterprise, regardless of its size, sets up a company to split its profits in order to enjoy a lower tax rate, the IRD can apply GAAR to counteract the benefits and may impose a fine.  Any enterprise that avoids tax knowingly would certainly calculate the cost-effectiveness of arrangement.  Although it is not ruled out that enterprises may enter into an arrangement for saving just HK$165,000 (which would be the case only if the company has assessable profits of more than HK$4 million), apart from facing GAAR, dividing a business into two business is actually not easy in practice.  For example, a businessman operates a fashion retail shop and signed a five-year lease for the premises.  If he now wants to split into two companies to operate the same shop, he will need to seek consent from the landlord.  If you were the landlord would you agree to it unconditionally?  Then the business owner needs to bill customers separately, employees shall be hired by two companies, and vendors shall contract with two companies?  To save HK$165,000 for doing all these the business owner will likely end up losing money.  Of course, another approach is to maintain the operation of a company and to split the account into another company by means of internal allocation and accounting entries.  But would this pass the sharp eyes of the IRD assessors?

    As to the question “Can the two-tier profits tax system proposed in Bill 7 help reduce the tax burden on SMEs and start-ups?”, my answer to “No”.  This is because of the Special Anti-avoidance Rule contained in which is restrictive to SMEs and start-ups.  This provision is complicated and deviates from the requirements of a good tax system.  One of the criteria for a good tax system is “fairness”.  “Fairness” means that tax treatment should be the same for different taxpayers doing the same thing.  It is fair for everyone to pay a high tax rate for higher profits, but it is unfair if benefits would be denied for being part of a group.  In fact, groups that set up a company to operate a business is no different from an SME, the group also needs to invest capital, hire qualified personnel and take risks, and the difference is that large groups can generally be able to do these more efficiently.  Perhaps “fairness” in the eyes of the government is that all large corporations and small enterprises can only choose one company to enjoy the benefits without discrimination.  Hong Kong does not have a group consolidation profits tax regime, but the lower tier profits tax rate is applied on a group basis, so there seems to be a conflict in administration.

    In fact, there are quite a lot of channels for the Government to use financial means to help alleviate the burden on SMEs or start-ups, some of which may not have any assessable profit at all.  The Government could consider providing low-cost office space or industrial premises consider help reduce their operating costs, and even set up some special support funds for eligible enterprises or small size groups to apply?  When these enterprises become tax paying, the Government will recover the investments through tax revenue.

    Tax Tips: If a business earns HK$2 million profits a year, but it is actually earned through four companies (each HK$500,000), according to the two-tier system, the business can only save HK$41,250 (instead of HK$165,000).  It is time for SMEs to review the assessable profits of its companies and to choose one to enjoy the preferential tax rate in the future.  If commercially viable with the business transformation, businesses have the opportunity to enjoy the HK$165,000 benefits in full. The premise, of course, is to strictly abide by the requirements of the tax regulations.


    Author: Edwin Bin

    Ref:

    Inland Revenue (Amendment) (No. 7) Bill 2017:

    http://www.gld.gov.hk/egazette/pdf/20172152/es32017215230.pdf

    Carrie Lam Election Manifesto:

    https://www.carrielam2017.hk/media/my/2017/01/Manifesto_e_v2.pdf

    2017 Policy Address:

    https://www.policyaddress.gov.hk/2017/eng/policy_ch03.html

    Tax Summit Speech by FS (Chinese only):

    http://www.info.gov.hk/gia/general/201710/23/P2017102300746.htm

    Secretary for FSTB Speech (Chinese only):

    http://www.fstb.gov.hk/tb/tc/docs/sp20180110a_c.pdf

    Institute For Fiscal Studies:

    https://www.ifs.org.uk/budgets/gb2008/08chap11.pdf

    https://www.ifs.org.uk/uploads/publications/bns/bn09.pdf

    UK General Anti-Avoidance Rules:

    https://www.gov.uk/government/uploads/system/uploads/attachment_data/file/602420/HMRC_GAAR_Guidance_Parts_A_B_and_C_-_with_effect_from_30_January_2015.pdf