manageyourtax.com

Tag: #OffshoreClaim

  • Tax Tips (22) – Dealing with International Tax Cooperation

    Tax Tips (22) – Dealing with International Tax Cooperation

    A multilateral tax cooperation mechanism under the Belt and Road Initiative (BRI), the Belt and Road Initiative Tax Administration Mechanism (BRITACOM) which includes tax authorities from 34 countries and regions, was established on 18 April 2019. The reported aim of BRITACOM is to facilitate cross-border trade and investment along BRI routes by expanding tax dispute resolution activities, increasing transparency, streamlining compliance and digitizing filing.  An office will be opened in Beijing to help facilitate these goals.

    Since the BRI consists primarily of Chinese outbound investment in infrastructure projects in the participating countries, BRITACOM will likely function more in facilitating outbound Mainland Chinese entities’ local tax compliance and dispute resolution when engaged in such projects. BRITACOM will be different from the various anti-tax avoidance initiatives of the OECD and other international organisations.

    International Effort in Anti-Tax Avoidance

    The most well-known international effort against tax avoidance is the Base Erosion and Profit Shifting (BEPS) project. The 15 BEPS Actions issued in October 2015 challenge tax avoidance practices by large Multinational Enterprises (“L-MNEs”) by amending the global tax treaties, increasing disclosure and transparency, introducing new documentation in transfer pricing, countering harmful tax practices, lowering threshold of permanent establishment recognition, investigating into new form of taxation for digital services and toughening interest deduction rules. The primary aim of BEPS is to ensure that the international tax rules do not facilitate the shifting of corporate profits away from the real economic activity and value creation are taking place. Many of these Actions have been implemented already, the latest being the Economic Substance Law (with the BVI just issued the Draft Economic Substance Code).

    In addition, the OECD has stepped up efforts in international cooperation on tax matters in recent years. Heads of tax administrations meet regularly at the Forum of Tax Administration (FTA). Cross-border tax avoidance intelligence is shared among tax offices under the Joint International Taskforce on Shared Intelligence and Collaboration (JITSIC). The International Compliance Assurance Programme (ICAP) invites large MNEs to engage voluntarily with tax administrations from 17 jurisdictions (expanded from 8 when the pilot began in January 2018). Tax Inspectors Without Borders sends experience tax officials to train those in developing countries to perform tax audits on MNEs.

    The United Nation, the World Bank, the International Monetary Fund, and the European Unions are also very active in introducing new initiatives in combating tax avoidance.

    Large MNEs have Acted

    Many L-MNEs have already started restructuring back in around 2013/14 in view of the disclosure requirements especially the Country-by-Country Reporting (CbCR). In the past, many L-MNEs housed the intellectual properties (“IP”) in tax haven jurisdictions earning untaxed royalties or have captive insurance companies there to provide insurance coverage to group companies in order to receive untaxed income while the group companies could take a tax deduction. Smart L-MNEs would have restructured early so that no tax office would have the opportunity to ask the sensitive questions. Their most immediate challenge to the L-MNEs would likely be dealing with the economic substance law in the tax haven countries, especially those that have been acting as funding vehicles.

    Smaller MNEs – Act Now

    L-MNEs have internal tax resources to help them manage tax risks in this rapidly changing tax environment. What about the Small and Medium Size MNEs (S-MNEs) that do not have in-house tax people? They obviously have to rely on external tax consultants. The key is to identify the right consultants to do the following two things:

    1. Review the existing structure, operations and arrangements

    The objective of such review is to identify tax risks and opportunities currently embedded in the group structure and operations. The author had seen a group missing out the 50/50 offshore claim in the Hong Kong profits tax filing on a contract manufacturing arrangement. In another case, a Hong Kong-based listed group devoted resources in Hong Kong to help the overseas affiliates in high tax countries to become highly profitable but they do not realise that they should recoup the costs incurred in Hong Kong via transfer pricing in order to align with the commercial reality and reduce the group’s effective tax rate. These can be dug out and properly addressed in order to create legitimate tax saving.

    Some groups have not paid attention to documentation of decision making and thereby creating risks of being regarded as tax resident in jurisdictions unexpectedly. The old model of cost-plus remuneration of agents may now be exposed to permanent establishment risks. Some have ignored the documentation of substance. The impact of the Economic Substance Law introduced by the tax havens such as the British Virgin Islands (BVI) must be properly analysed with a set of action determined to address the issue.

    To be a good manager, issues should be addressed and resolved upfront so that the expectation of shareholders and directors of the group/company is well-managed. The review should be conducted by professionals with solid technical and business experience. There are well-qualified tax advisors in the market to do the work at competitive rates and high efficiency to deliver substantial value to the groups.

    Often the finance managers of the groups/companies prefer to stick their heads into the sand instead of dealing with the problems because they don’t want to take the blame for issues uncovered by the seasoned tax advisors. It is thus important for the directors or even the shareholders to realise what the current tax environment is like and take initiative in carrying out the review. At the end of the day, if the hidden tax exposures are not cleared before they crystalise, the group/company, the directors and shareholders would be badly hurt.

    2. Seek on-going tax support especially on documentation

    Having identified and dealt with past issues, it is important that no such issue will arise again in the future. This can be achieved by retaining the tax advisor to review transactions or documentation as and when required, just a family doctor caring for the health of the family. For example, sometimes the auditors, being unaware of the tax exposure created, may make disclosures in the audited financial statements that are unnecessary and sometimes even harmful to the tax arrangement of the company. For listed companies, they should be very careful in the disclosures in the annual reports.

    Board papers are crucial. It is direct evidence of management and control which is one of the key factors in determining substance and tax residency. Tax advisors play an important role in advising who should be on the board of each company, location of board meetings and review the board papers.

    Also, management should be made aware of tax law changes and new cases that affect their business. Questions they should ask, or proactively addressed by the tax advisor, include:

    • What are the benefits of the new tax incentives introduced in Hong Kong such as the two-tier tax system to the group?
    • Should something be done about intellectual property in view of the new Section 15F of the Inland Revenue Ordinance?
    • What should the group do in view of the Beneficial Ownership rules in Mainland China to ensure that the benefits can be obtained?
    • Is CbCR going to affect the group?
    • The boss travels to Mainland China often, is he exposed to the Chinese Individual Income Tax on worldwide income?
    • Is the loan financing of a foreign subsidiary compliant with transfer pricing or will it be challenged by the tax authorities?
    • In view of the tax cases, can the Hong Kong company still lodge an offshore claim on its trading profits? How to ensure a successful claim?
    • How to structure a new acquisition? Is the Multilateral Convention to Implement Tax Treaty Related Measures to Prevent BEPS (commonly referred to as the Multilateral Instrument) going to affect the group? Would all the new tax rules introduced bring higher tax exposures in a share deal and how to mitigate such risks?

    The list of questions can be much longer.

    Tax Tips

    It is time for the smaller groups to gear up the tax risk monitoring and compliance, and ensure that structures are sustainable in the medium term. The BEPS Project is at the implementation stage and it will not be long before OECD reviews the achievement and point to the next target: the S-MNE groups. The time to act is NOW.


    Contact Us


    Ref:

    BRITACOM: http://www.chinatax.gov.cn/eng/n2367751/c4273658/content.html
  • Tax Tips (6) – Territorial Concept x Transfer Pricing

    The Inland Revenue (Amendment) (No. 6) Bill 2017 (the “Bill”) that was discussed in Tax Tips (2) and (3) proposed to introduce Part 8AA – Transfer Pricing Rules to the Inland Revenue Ordinance.  Transfer Pricing rules require transactions with associated enterprises be conducted under the Arm’s Length Principle.  Section 50AAD(1) of Part 8AA reads: “This Part applies in determining a person’s liability for property tax, salaries tax and profits tax”.  Putting aside Property Tax and Salaries Tax (the Author does not think that it is appropriate to extend transfer pricing regulations to Salaries Tax), the Author’s interpretation of this Section is that “when a person is liable to Profits Tax, Part 8AA operates to determine the extent of the liability”.  Whether a person is liable to Profits Tax, one shall mainly refer to Section 14(1) of the Inland Revenue Ordinance, which says:

    Subject to the provisions of this Ordinance, profits tax shall be charged for each year of assessment at the standard rate on every person carrying on a trade, profession or business in Hong Kong in respect of his assessable profits arising in or derived from Hong Kong for that year from such trade, profession or business (excluding profits arising from the sale of capital assets) as ascertained in accordance with this Part.

    If the profits of a connected transaction are derived from outside Hong Kong and not subject to Profits Tax under Section 14(1), the Hong Kong taxpayer should be regarded as “not liable to profits tax” and thus Section 50AAD(1) of Part 8AA would not be applicable.  Even if the Hong Kong taxpayer has substantive business and operating activities in Hong Kong, as long as the profits of the connected transactions are derived from outside Hong Kong, the Inland Revenue Department (“IRD”) should not impose Profits Tax on the profits attributable to the risks assumed and functions carried out in Hong Kong. This is the correct treatment because if the substantive business activities carried out by non-associated enterprises would not be subject to Profits Tax, the same activities carried out by associated enterprises should not be treated differently.  This principle has been mentioned in Paragraph 71 of the Departmental Interpretation and Practice Notes No. 46 – Transfer Pricing Guidelines – Methodologies and Related Issues (December 2009) (“DIPN 46”).  In theory, the principle of territorial-based taxation is maintained.

    Connected Transactions in D25/14

    In the last issue of Tax Tips, the Inland Revenue Board of Review (“BOR”) Decision for Case D25/14 (published in February 2016 Volume 30 First Supplement) was discussed.  Although the matter in dispute was not related to transfer pricing, as the case involved both the source of profits and transfer pricing, it can be used to discuss this topic: if Part 8AA Section 50AAD(1) was already the law, how would it apply to the case? [Please refer to Tax Tips (5) for the background of the case]

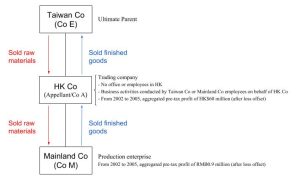
    Case Appellant Company A (“Co A, a Hong Kong company) had no employee and asset in Hong Kong, all contracts were entered into and performed outside Hong Kong, but the BOR determined that regardless of the whereabouts of the controlling staff and the places where the contract was entered into and performed, the trading between Taiwan Co and Mainland Co would have been impossible in the absence of the Appellant as the “middleman”.  The activity of playing such role was obviously in Hong Kong.  The BOR rejected the Appellant’s argument that “the profits were not arising in or derived from Hong Kong”, and confirmed that the profits of Co A were fully subject to Profits Tax.  Assuming Part 8AA has been implemented, given that Co A’s transaction was definitely a connected transaction and has been ruled by the BOR to be liable to Profits Tax, how would the IRD “determine the extent of such liability?”

    Under normal circumstances, “to determine the extent of such liability”, one basically assumes Co A was not an associated company of Taiwan Co and Mainland Co, and based on Co A’s functions, risks, government policies etc., search for comparable companies in the market, select the appropriate transfer pricing method to determine whether Co A’s profit is lower than those earned by comparable companies under the Arm’s Length Principle.  If it is determined to be lower than the arm’s length profits, the IRD may adjust the assessable profits upward and assess Profits Tax.  Although Co A’s case did not disclose the functions performed and risks assumed by each of the affiliated companies, it can be reasonably assumed that most of the risks were borne by Taiwan Co, such as bad debts, cargo insurance, foreign exchange risks etc.  The three companies each had their own functions, but Co A did not have employee and asset so it could only have performed limited functions.  In addition, as Co A only served as an intermediary for the entire transaction, if the Taiwan Co did not own Co A, but rather traded with the mainland manufacturer through an independent, non-affiliated Hong Kong company (call it “Co X”), it would be likely that a lot of genuine Hong Kong trading companies would be happy to take up the middleman role for a relatively lower return for the limited risks it would bear.  This “middleman” role, which was regarded as extremely important by the IRD and the BOR, would not seem to be very valuable from transfer pricing perspective.

    The Author suspects that the entire planning behind Co A was that Co A was expected to be successful in Hong Kong Profits Tax exemption on the basis that the profits were sourced from outside Hong Kong, thus it is likely that Co A made excessive profits during the years.  According to publicly available information, from 2002 to 2005, Co A’s total sales revenue was HK$237,121,169, with an aggregated pre-tax profit of HK$60,053,849 (after loss offset), resulting in a high net profit margin of 25%!  Would this “very important intermediary role” be entitled to earn such a high profit?  Would the Taiwan Co give more than HK$60 million of profits to the independent, non-affiliated Co X?  As for the Mainland Co, the total profits from 2002 to 2005 was only RMB918,234 (after loss offset)!  It seems that Co A was carefully operated to lower the group’s overall tax burden by making the offshore claim.

    Anti-Avoidance is the Highest Principle?

    The Author also suspects that the IRD was aware of the possible tax avoidance via offshore claim.  As it would be inappropriate to invoke the General Anti-Avoidance provisions under Section 61A of the Inland Revenue Ordinance to tackle this case, the IRD countered such avoidance act by seeking to disallow the Offshore Claim.  As the contracts of sale and purchase of Co A were effected and performed outside Hong Kong, under DIPN 21 as referred to in the last issue of the “Tax Tips” the profits would not be subject to tax in Hong Kong.  In order to win the case, the IRD linked the “extremely important” middleman’s role and functions (which is a concept of transfer pricing) with the source of profits, and succeeded in winning at the cost of overturning DIPN 21.  In the past, the IRD would respect the territorial concept of taxation and would not inquire whether the relevant profits were taxed elsewhere.  However, under the bandwagon of BEPS(1), it seems that anti-avoidance has become the highest principle.  As for the BEPS concept of “allowing companies to pay tax at the location of their real business activities and value creation”, the real idea seems to be that “if no one is claiming tax on profits, I will come forward”.  Therefore, it will become more and more difficult to be granted the offshore treatment in the future (many people would have felt it already in the past few years).  This is particularly worrying as the law and DIPN 21 have remained unamended.

    Finally, would the IRD adjust-down Co A’s assessable profits (assuming the transfer pricing report determines that Co A’s profit is too high) in accordance with the arm’s length principle?  The answer is “No”, not only because the subject matter in question is the source of profit, as a matter of policy, the IRD would simply not proactively adjust-down excessive profits.  Furthermore, unless the tax authorities in the Mainland decided that Co A has constituted a permanent establishment in the Mainland and imposed a 25% corporate income tax on the profits of Co A, there is no double taxation and the IRD can safely pocket the tax revenue. This principle is also illustrated in paragraphs 71 and 72 of DIPN 46.

    (1) See “Tax Tips” (1) and (2)

    Tax Tips: Taxpayers must recognise the general direction and current climate of transfer pricing.  Before making any arrangement, it is important to anticipate that every tax office involved in a transaction wants a share of your profits — tax authorities are increasingly interested in using “Profits Split” to divide the profits of the entire supply chain.  It is conceivable that there will also be disagreements between tax authorities, and taxpayers in Hong Kong may eventually have to ask the IRD to invoke the Mutual Agreement Procedure and Arbitration under the double taxation arrangements to negotiate with the other side (or multiple sides) on who gets to tax which part of your profits.  After lengthy discussions, taxpayers would also have to pay IRD the relevant fees (Section 50AAB introduced in the Bill refers).  It is recommended that taxpayers should immediately review all connected transactions, collect evidence and supporting arguments, determine the most suitable transfer pricing methodologies, and prepare appropriate transfer pricing documentation to meet possible challenges in the future.

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on February 26, 2018: https://manageyourtax.com/HKEJ Forum 6)

    Contact Us

    Author: Edwin Bin

    Ref:

    The Bill: http://www.gld.gov.hk/egazette/pdf/20172152/es32017215229.pdf

    D25/14: http://www.info.gov.hk/bor/tc/docs/D2514.pdf

    DIPN 21: https://www.ird.gov.hk/chi/pdf/c_dipn21.pdf

    DIPN 46: https://www.ird.gov.hk/eng/pdf/e_dipn46.pdf