A multilateral tax cooperation mechanism under the Belt and Road Initiative (BRI), the Belt and Road Initiative Tax Administration Mechanism (BRITACOM) which includes tax authorities from 34 countries and regions, was established on 18 April 2019. The reported aim of BRITACOM is to facilitate cross-border trade and investment along BRI routes by expanding tax dispute resolution activities, increasing transparency, streamlining compliance and digitizing filing. An office will be opened in Beijing to help facilitate these goals.
Since the BRI consists primarily of Chinese outbound investment in infrastructure projects in the participating countries, BRITACOM will likely function more in facilitating outbound Mainland Chinese entities’ local tax compliance and dispute resolution when engaged in such projects. BRITACOM will be different from the various anti-tax avoidance initiatives of the OECD and other international organisations.
International Effort in Anti-Tax Avoidance
The most well-known international effort against tax avoidance is the Base Erosion and Profit Shifting (BEPS) project. The 15 BEPS Actions issued in October 2015 challenge tax avoidance practices by large Multinational Enterprises (“L-MNEs”) by amending the global tax treaties, increasing disclosure and transparency, introducing new documentation in transfer pricing, countering harmful tax practices, lowering threshold of permanent establishment recognition, investigating into new form of taxation for digital services and toughening interest deduction rules. The primary aim of BEPS is to ensure that the international tax rules do not facilitate the shifting of corporate profits away from the real economic activity and value creation are taking place. Many of these Actions have been implemented already, the latest being the Economic Substance Law (with the BVI just issued the Draft Economic Substance Code).
In addition, the OECD has stepped up efforts in international cooperation on tax matters in recent years. Heads of tax administrations meet regularly at the Forum of Tax Administration (FTA). Cross-border tax avoidance intelligence is shared among tax offices under the Joint International Taskforce on Shared Intelligence and Collaboration (JITSIC). The International Compliance Assurance Programme (ICAP) invites large MNEs to engage voluntarily with tax administrations from 17 jurisdictions (expanded from 8 when the pilot began in January 2018). Tax Inspectors Without Borders sends experience tax officials to train those in developing countries to perform tax audits on MNEs.
The United Nation, the World Bank, the International Monetary Fund, and the European Unions are also very active in introducing new initiatives in combating tax avoidance.
Large MNEs have Acted
Many L-MNEs have already started restructuring back in around 2013/14 in view of the disclosure requirements especially the Country-by-Country Reporting (CbCR). In the past, many L-MNEs housed the intellectual properties (“IP”) in tax haven jurisdictions earning untaxed royalties or have captive insurance companies there to provide insurance coverage to group companies in order to receive untaxed income while the group companies could take a tax deduction. Smart L-MNEs would have restructured early so that no tax office would have the opportunity to ask the sensitive questions. Their most immediate challenge to the L-MNEs would likely be dealing with the economic substance law in the tax haven countries, especially those that have been acting as funding vehicles.
Smaller MNEs – Act Now
L-MNEs have internal tax resources to help them manage tax risks in this rapidly changing tax environment. What about the Small and Medium Size MNEs (S-MNEs) that do not have in-house tax people? They obviously have to rely on external tax consultants. The key is to identify the right consultants to do the following two things:
1. Review the existing structure, operations and arrangements
The objective of such review is to identify tax risks and opportunities currently embedded in the group structure and operations. The author had seen a group missing out the 50/50 offshore claim in the Hong Kong profits tax filing on a contract manufacturing arrangement. In another case, a Hong Kong-based listed group devoted resources in Hong Kong to help the overseas affiliates in high tax countries to become highly profitable but they do not realise that they should recoup the costs incurred in Hong Kong via transfer pricing in order to align with the commercial reality and reduce the group’s effective tax rate. These can be dug out and properly addressed in order to create legitimate tax saving.
Some groups have not paid attention to documentation of decision making and thereby creating risks of being regarded as tax resident in jurisdictions unexpectedly. The old model of cost-plus remuneration of agents may now be exposed to permanent establishment risks. Some have ignored the documentation of substance. The impact of the Economic Substance Law introduced by the tax havens such as the British Virgin Islands (BVI) must be properly analysed with a set of action determined to address the issue.
To be a good manager, issues should be addressed and resolved upfront so that the expectation of shareholders and directors of the group/company is well-managed. The review should be conducted by professionals with solid technical and business experience. There are well-qualified tax advisors in the market to do the work at competitive rates and high efficiency to deliver substantial value to the groups.
Often the finance managers of the groups/companies prefer to stick their heads into the sand instead of dealing with the problems because they don’t want to take the blame for issues uncovered by the seasoned tax advisors. It is thus important for the directors or even the shareholders to realise what the current tax environment is like and take initiative in carrying out the review. At the end of the day, if the hidden tax exposures are not cleared before they crystalise, the group/company, the directors and shareholders would be badly hurt.
2. Seek on-going tax support especially on documentation
Having identified and dealt with past issues, it is important that no such issue will arise again in the future. This can be achieved by retaining the tax advisor to review transactions or documentation as and when required, just a family doctor caring for the health of the family. For example, sometimes the auditors, being unaware of the tax exposure created, may make disclosures in the audited financial statements that are unnecessary and sometimes even harmful to the tax arrangement of the company. For listed companies, they should be very careful in the disclosures in the annual reports.
Board papers are crucial. It is direct evidence of management and control which is one of the key factors in determining substance and tax residency. Tax advisors play an important role in advising who should be on the board of each company, location of board meetings and review the board papers.
Also, management should be made aware of tax law changes and new cases that affect their business. Questions they should ask, or proactively addressed by the tax advisor, include:
What are the benefits of the new tax incentives introduced in Hong Kong such as the two-tier tax system to the group?
Should something be done about intellectual property in view of the new Section 15F of the Inland Revenue Ordinance?
What should the group do in view of the Beneficial Ownership rules in Mainland China to ensure that the benefits can be obtained?
It is time for the smaller groups to gear up the tax risk monitoring and compliance, and ensure that structures are sustainable in the medium term. The BEPS Project is at the implementation stage and it will not be long before OECD reviews the achievement and point to the next target: the S-MNE groups. The time to act is NOW.
If you work in a Hong Kong subsidiary of a large Multinational Enterprise (MNE) Group and you think Country-by-Country Reporting (CbCR) has nothing to do with you, think again.
Your employer could be facing a penalty of HK$50,000 (US$6,400) on each Hong Kong entity for failing to file CbCR notification with the Hong Kong Inland Revenue Department (“IRD”), the first deadline falls on 31 March 2019 (the IRD announced on 21 March 2019 that the notification deadline for qualifying entities is extended by 45 days to 15 May 2019). Failing to file the CbCR will also attract the same level of penalties. In addition, you may be under a statutory obligation to keep the underlying records of the CbCR, which includes detailed information of the global operations of the Group, for 6 years or you may once again get hit with the HK$50,000 penalty. What is more, the Hong Kong CbCR Rules could impact your Group’s relationship with business partners and potential investors.
The CbCR rules are contained in Part 9A Division 3 of the Inland Revenue Ordinance (“IRO”) introduced under Inland Revenue (Amendment) (No 6) Ordinance 2018, which also included the other transfer pricing documentation requirements, namely the master file and local file. This Tax Tips focuses on the CbCR, which many in the community are not aware of the statutory requirements, the additional hurdles introduced for compliance, the practical issues of preparing the CbCR, and the importance of project management. The Hong Kong CbCR rules are, unfortunately, very tough.
Worried? Read on.
The Basics about CbCR
The CbCR was introduced under the Final Report on Action 13 of the OECD Base Erosion and Profit Shifting (“BEPS”) Project (“Action 13”) as a tool for high-level transfer pricing risk assessment. It may be used by tax administrations in evaluating other BEPS related risks and where appropriate for economic and statistical analysis.
Action 13 – Who needs to prepare CbCR and where to file
Normally it should be relatively easy to determine if an entity is required to file a tax return or not. Not the case for CbCR. The general rule under Action 13 is that if an MNE Group’s annual consolidated group revenue in the immediately preceding fiscal year (for example, for the year ended 31 December 2017) exceeds EUR750 million, then Ultimate Parent Entity (“UPE”) of the group will need to prepare CbCR for the following year (the year ended 31 December 2018 in the example), and file it with the UPE’s tax office which is due within 12 months after the year-end date (31 December 2019 in the example).
The CbCR submitted will then be automatically exchanged with other jurisdictions (based on an international agreement – the Multilateral Competent Authority Agreement on the Exchange of CbC Reports (the “CbC MCAA”)) that the MNE Group operates in (as indicated on the CbCR) so that there is no need for the UPE to file the report multiple times in different tax jurisdictions. However, there are a variety of situations for CbCR exchanges. The United States, for example, did not sign the document but instead arrange bilateral exchange agreements with other jurisdictions. Some jurisdictions, such as the Cayman Islands and Bermuda, are only doing one-way exchange: sending the CbCR collected to other jurisdictions but is not accepting CbCR (likely because there is no tax there).
The CbCR
The CbCR consists of three tables. Table One requires aggregate tax jurisdiction-wide information relating to the global allocation of the income, the taxes paid, and certain indicators of the location of economic activity among tax jurisdictions in which the MNE Group operates. Below is Table One.
Table 1
Table Two requires a listing of all the Constituent Entities (“CE”) of the MNE Group for which financial information is reported, including the tax jurisdiction of incorporation, where different from tax jurisdiction of residence, as well as the nature of the main business activities carried out by that CE.
Table 2
MNE Groups may use Table Three to provide additional information or explanation that is considered necessary or that would facilitate the understanding of the compulsory information provided in Table One and Two.
Table 3
Simple in Design, Difficult to Comply
After Action 13 was published in 2015, tax jurisdictions around the world have to pass the filing requirements into the local laws before CbCR can be collected. Naturally, some tax jurisdictions (mostly OECD countries) managed to swiftly implement the rules (the first year of filing would be for the year 2016, meaning the financial year that began within the calendar year 2016) but many were late. Hong Kong passed the law in July 2018 and the first year of filing is for the year 2018.
What would happen if the jurisdiction where the UPE is located has not introduced the CbCR laws but in some jurisdictions that the MNE Group operates the CbCR laws have been implemented?
This is where the “fun” is.
Local Filing, Parent Surrogate Filing, Surrogate Parent Filing
The MNE Group has to find out at each location that it operates, what is the status of CbCR implementation, and whether there is a “Local Filing” requirement. Local Filing, in simple terms, refers to the filing requirement imposed on the CE located in the tax jurisdiction to file the Group CbCR when the tax office is not able to obtain the CbCR from the UPE’s tax jurisdiction. In some jurisdictions, Local Filing is needed only upon request (for example, during a tax investigation).
If the UPE is required to file CbCR, it will need to check all the locations where the group operates whether the tax jurisdiction of the local CE is able to obtain the CbCR via an exchange mechanism with the UPE’s tax jurisdiction. If not, the local CE needs to perform Local Filing. In which case, the UPE needs to provide the CbCR to the local CE for filing. Multiple Local Filings may be needed.
If the UPE is not required to file CbCR, the Group is more likely to face multiple filings in different jurisdictions. To help reduce the compliance burden, Action 13 introduced two solutions: Parent Surrogate Filing and Surrogate Parent Filing (there is no typo here, these are two different terms), but it is up to each tax jurisdiction to determine if they allow such filing.
Parent Surrogate Filing refers to a voluntary CbCR filing by the UPE at the UPE’s tax jurisdiction before statutory filing is introduced into law. The tax office will exchange the CbCR obtained with other jurisdictions via automatic exchange or bilateral agreement. Hong Kong is a jurisdiction that accepted Parent Surrogate Filing for years 2016 and 2017 but it is unlikely that this offer has ever been taken up as the exchange network was very limited (thus incapable to avoid multiple Local Filing in other jurisdictions).
Surrogate Parent Filing allows the UPE to appoint a CE in another jurisdiction to be the parent entity for CbCR purposes and file the group’s CbCR with that other jurisdiction as if the CE is the UPE of the Group. This is a more popular solution for avoiding multiple Local Filing because the group can choose a CE in a jurisdiction with the widest automatic-exchange network (for example, the United Kingdom) as the Surrogate Parent Entity (“SPE”). Many Hong Kong groups selected this filing method for the years 2016 and 2017.
The OECD has been keeping track of the CbCR implementation status of different jurisdictions as well as their acceptance of Parent Surrogate and Surrogate Parent Filing. Below is the status as at 10 January 2019 extracted from the OECD website:
Anyone who had the experience of managing the CbCR filing for a reportable MNE Group for years 2016 and 2017 would know how much headache it is to ensure compliance.
Are You Ready for Preparing the CbCR Correctly?
Test your knowledge by answering the following true or false statements:
TRUE or FALSE:
CEs refer to entities that the UPE owns 50% or more.
Representative Offices or Branches with separate accounts are themselves CEs.
“Revenue” includes capital gains.
Related parties transactions can be eliminated for reporting.
Income tax paid does not include foreign taxes.
A CE that left the group during the year (e.g. disposed of) can be excluded from the CbCR for that year.
The number of employees includes independent contractors.
The Tax Identification Numbers (taxpayer file number) and addresses of CEs are not required for CbCR filing.
Answers are at the end of this article.
The OECD Action 13, the Guidance on the Implementation of CbCR (the “CbCR Guidelines”, issued by the OECD and last updated in September 2018) and the CbCR: Handbook on Effective Implementation (the “CbCR Handbook” issued by the OECD in 2017) provide some guidance on the definition of various terms and how to deal with different situations. However, it is far from comprehensive. Groups need to decide in situations specific to them the position to take in the CbCR and ensure that all CEs take the same position. It is thus important that the MNE Group studies the OECD documents and guidance issued by tax offices and prepare a set of CbCR Instructions for internal use to align the basis of preparation.
For larger groups, especially those with different business lines and frequent M&A activities, a set of Frequently Asked Questions would be helpful as the first point of contact when the people in different jurisdictions involved in the data input face questions, as some of them may raise the same questions. Where applicable, part of the CbCR Instructions and FAQ can be disclosed in Table 3 of the CbCR. For example, the Instructions and FAQ may cover items such as:
How to report newly set-up CEs that have not closed their books as at the year-end date of the UPE
Source of data
Which entities are “related entities” for CbCR purposes
How to account for withholding taxes paid if the tax is calculated on a gross-up basis
How to report the tax paid in the case of a tax grouping
How to check the “main business activity(ies)” boxes for the different businesses of the group
Who is to determine if a CE is dormant
Approach to prepare the CbCR – Top-Down or Bottom-Up?
Obviously, if the group prepares the CbCR centrally at one location (say at the headquarters) based on financial data on CEs around the world that it possesses, it can achieve the best level of consistency. This Top-Down approach can avoid worldwide training for data input. However, the central location will inevitably need to obtain information from local CEs, and they may provide incorrect information if they do not understand CbCR. In addition, when the CbCR submitted is exchanged to the jurisdictions of the local CEs, the local CEs may be approached by the local tax office for explanations on the data. In such a situation, the headquarters will need to answer the questions from afar. The situation will become unmanageable if many tax offices ask questions at the same time.
Automation or manual input?
Another question that all MNE Groups would go through is: how to avoid the manual data collection process? There is no right or wrong answer to that and it is more a cost-benefit analysis. There are two important factors to consider: (i) whether the same accounting system is adopted across the group and (ii) whether the adjustments required (for example, identifying the related party transactions with CEs) can be dealt with by the system. Further, if the Group makes acquisitions, which often happen in the corporate world, substantial efforts may be required to change the legacy accounting system of the newly acquired entities. In real life, several different accounting systems may be deployed within an MNE Group.
How to manage the CbCR preparation
If an MNE Group is required to prepare CbCR and the bottom-up, manual input approach is adopted, the steps would include the following:
Assign a Project Manager – a person who is knowledgeable about CbCR or has access to technical resources;
Manage notifications across the group;
Compile the list of CE for the reporting year and determine the tax jurisdiction of each entity including the tax haven entities;
Assign a staff person from the finance or accounts department to each CE as the first level data input;
Assign a “CbCR Champion” to each group of entities which can be based on jurisdiction and/or business lines. The CbCR Champions would need to ensure consistency in the data compilation and address questions, and review data input by staff. More difficult questions can be forwarded to the Project Manager for resolution;
Prepare a detailed Instructions and FAQ and everyone involved in the process should study them before commencing work;
Training for all involved in the process, timeline and the position taken on different aspects;
Prepare an Excel format data input worksheet for data input;
Staff perform data input and submit to CbCR champion for review with supporting documents (financial statements etc);
Final review by the Project Manager and combine all input to prepare tables;
Sign off by senior management;
Convert the file into XML format (as requested by the tax office);
Submission.
The above is not rocket science. However, each step requires careful planning and execution in order to meet the filing deadline. Needless to say, the more CEs spreading across different jurisdictions, the more difficult it will be to manage the process and the risk of error will increase. Training and project management will become most important.
In addition, although MNE Groups are given 12 months to prepare the CbCR, when they can actually commence data input depends on how long it takes post-year-end to finalise the local financial statements. The longer it takes to finalise the accounts, the less time there is to prepare for the CbCR. Realistically, the time available would likely be less than 9 months.
The Hong Kong Rules are Making Life Even Harder
The Hong Kong rules on CbCR fully incorporated the Action 13, CbCR Guidelines and CbCR Handbook. As long as MNE Groups follow these documents and adequately disclose some of the position taken, there should be relatively little concern of incorrect filing. However, on the administration side, MNE Groups with CEs in Hong Kong must pay special attention to the Hong Kong rules.
Notification – Section 58H
Section 58H under Division 3, Part 9A of the IRO sets out the requirement for notification: each Hong Kong CE of a reportable group must file a notification informing the IRD, effectively, which entity in Hong Kong will file the CbC Return* or, if the CbC Report* is to be filed in another jurisdiction, various information about such filing. One Hong Kong entity of the MNE Group can represent other group entities to file the notification. Notification deadline is within 3 months after the end of the year-end of the MNE Group.
* This article used the term “CbCR” in a broad sense to describe both the CbC Report (the three tables) that is filed with the tax office and the act of preparing the CbC Report. The Hong Kong rules distinguish between the “CbC Return” and the “CbC Report”. The CbC Report is the report containing the three tables discussed above. Under Section 58K(1), the CbC Return is the CbC Report and “any other information specified by the Board of Inland Revenue”.
In many jurisdictions (for example, the UK, Malaysia and South Korea), notification can be done by writing a letter or filling in a prescribed form. In Hong Kong, one needs to file notification via the CbC Reporting Portal (“Portal”). The Portal is developed by the IRD to facilitate the Hong Kong entities to:
submit notifications of obligations to file CbC Returns;
submit notifications of change of address;
file CbC Returns; and
receive or send messages in relation to CbC reporting.
IRD CbC Portal
Just like any online system, a registration procedure is required to access the Portal. A Hong Kong Entity should register a CbC Reporting Account under the Portal. The person authorized to register a CbC Reporting Account for the entity has to possess an e-Cert (Organisational) with AEOI Functions (“e-Cert”) for authentication purposes. The person has to apply for the e-Cert at the Hong Kong Post.
Manage Your Tax’s e-Cert (Organisation) with AEOI function
Filing – Section 58E and 58F
The deadline for the filing of a CbC Return is within 12 months after the end of the accounting period, which obviously shall be filed via the Portal. Similar to most jurisdictions, a CbC Report must be made in the form of an XML document for submission to the IRD. The reason for this is that XML documents can be validated and provide a common medium for exchange between the jurisdictions that have introduced CbCR requirements. In this regard, the IRD has developed a data schema in XML which is based on the CbC XML Schema v1.0.1 issued by the OECD. The data schema specifies the data structure and format for filing CbC Report to the IRD. The current version of the data schema and related user guide is available on the IRD website for download.
It is important to note that other than the information required in Table 1, 2 and 3 of the CbC Report, the XML Schema User Guide issued by the Hong Kong IRD mandatorily requires that the Tax Identification Number (“TIN”) of each CE, where issued by the tax administration of the tax jurisdiction of the CE, be provided. If the CE does not have a TIN, the value “NOTIN” shall be entered. In addition, the XML Schema User Guide “strongly recommended” that the address of each CE shall be provided. Finally, if the CE is a Permanent Establishment, the name of the CE should be followed by “(P.E.)”.
To the unwary, these additional information and formatting requirements may create an issue if only discovered upon XML conversion, potentially causing late filing.
Automatic Exchange of the CbCR
After filing the CbCR with the IRD as the UPE or SPE, can the MNE Group rely on the IRD to send the CbCR out to other tax jurisdictions such that the filing obligations there would be satisfied? It depends. Although Hong Kong has signed the CbC MCAA, the automatic exchange with applies for accounting period starting on or after 1 January 2019. Therefore, for a Hong Kong UPE or SPE who is filing a CbCR with the IRD for the accounting period for the year ended 31 December 2018, the IRD would only exchange it with the following 11 jurisdictions (as at 31 January 2019) based on bilateral exchange arrangement in place:
France
Guernsey
Ireland
Japan
Jersey
Korea
Malta
Netherlands
New Zealand
South Africa
United Kingdom
If the Hong Kong UPE has CEs in a jurisdiction not listed above which requires Local Filing (e.g. Germany), the Germany CEs may need to file the CbCR locally. If the Hong Kong UPE is also considered a resident in another jurisdiction and that jurisdiction has an exchange agreement with Germany, then it may file in a second CbCR with that jurisdiction to cover the German filing and elsewhere.
Record keeping – Section 58L
Section 58L requires that a Reporting Entity must (a) keep sufficient records to enable the accuracy and completeness of the CbC Return filed under this Division (i.e. Division 3, Part 9A of the IRO) to be readily ascertained; and (b) retain the records for a period of 6 years beginning on the date on which the return is filed. The burden on the Reporting Entity is indeed substantial and thus it is important to know which entity is the Reporting Entity.
Under Section 58J, a Reporting Entity includes (a) a Hong Kong UPE required to file a CbC Return (Section 58E(1)), (b) a Hong Kong entity that is required to file a CbC Return by Section 58F (i.e. either under Local Filing or the entity is appointed the SPE), and (c) a Hong Kong entity that is required to provide a notice by Section 58H.
If a Hong Kong UPE or SPE is required to file the CbC Return it is fair to expect that entity to possess information that satisfies Section 58L. It is debatable whether it is fair to demand the same level of record keeping for an entity that performs Local Filing. It is, however, unreasonable and unnecessary to impose statutory obligations for the entity that files only a notification under Section 58H to maintain sufficient records for 6 years to enable the accuracy and completeness of the Group’s CbC Return be ascertained.
To illustrate, assume a Korean conglomerate engaged in shipbuilding, mobile phone manufacturing, financial services and health care is filing the CbCR in Korea, and only the mobile phone division has subsidiaries in Hong Kong and are required to file CbCR notification to the IRD. The Hong Kong subsidiaries will need to maintain the CbCR information of the entire global group to the extent required under Section 58L. The IRD should not impose such record-keeping requirement on the Hong Kong subsidiary. If the IRD requires information, they should approach the Korean tax office to collect it. Hong Kong subsidiaries of foreign MNE groups are now faced with this unreasonable statutory requirement.
Penalties – Section 80G
Division 6 of Part 9A contains the penalty provisions for CbCR. The new Section 80G provides that a Reporting Entity commits an offence if the entity, without reasonable excuse: (a) fails to file the CbC Return (Section 58E(1) or 58F); (b) fails to file notification under Section 58H; or (c) fails to keep records as required under Section 58L. That Reporting Entity would be liable on conviction to a fine at level 5 (HK$50,000/US$6,400), and the court may order the entity to do, within the time specified in the order, the act that the entity has failed to do. The Reporting Entity is liable to a further fine of HK$500 for every day or part of a day during which the failure to file the CbC Return or notification continues after conviction.
Obviously, there are further penalty provisions for more serious offences.
The penalty provisions are quite harsh especially on MNE Groups filing CbCR outside of Hong Kong. Their Hong Kong operations may be small and with little internal tax support. If the Hong Kong CE, being a Reportable Entity, is not wholly owned by the UPE (i.e. there is a minority shareholder), for information protection reason the MNE Group may not want to provide the detailed records to the CE as required under Section 58L. Is such information protection a “reasonable excuse” for not fulfilling Section 58L? If not, the minority shareholder may demand compensation from the MNE Group for any penalties suffered.
Service Providers
A service provider may be engaged to perform the filing and notification. However, the Reporting Entity’s obligations are not relieved. In addition, the service provider is also subject to the same level of penalties as the Reporting Entity for failure to file the CbC Return or notify the IRD.
Concluding Comments
CbCR is a very unique tax return: there is no tax to be calculated and no money to be paid, the “taxpayer” can in some cases choose where to file it but need to comply with all the CbCR rules and regulations in all jurisdictions that the taxpayer operates in, and corporate restructuring or M&A could bring chaos to the filing. In an acquisition, the buyer will need to obtain warranties or indemnities from the seller for exposures relating to CbCR.
With all the complexities, jurisdictions should implement the CbCR rules in a lenient manner, thereby reducing the pain felt by businesses. For instance, Singapore only accepts UPE filing (i.e. the MNE Group whose UPE is a Singapore tax resident, and no Surrogate Parent or Local Filing is accepted) and the local tax office (IRAS) would inform the UPE that they need to file the CbCR. Why would Singapore give up such power to collect information?
For a relatively small tax jurisdiction like Singapore where many foreign MNE Groups have set up subsidiaries, as long as Singapore has wide AEOI network, she is going to obtain the CbCR filed by the MNE Group elsewhere without imposing undue filing burden on the local taxpayers. According to the OECD website, at present (February 2019), Singapore can obtain CbCR from 63 jurisdictions, mostly from 2016 onwards. Hong Kong can obtain the CbCR from 56 jurisdictions but mostly only from 2019 onwards (before 2019, Hong Kong can only exchange with the 11 jurisdictions mentioned earlier).
Even if Singapore is not collecting all CbCR now, over time, when all jurisdictions around the world have introduced CbCR rules (Action 13 is one of the minimum standards that over 125 jurisdictions, by joining the OECD Inclusive Framework, have agreed to implement), Singapore will collect all CbCR from MNE Groups that operate in Singapore. Comparing with Singapore, subsidiaries of foreign MNE Groups in Hong Kong face the Local Filing burden, notification requirement (and need to obtain the e-Cert), the record-keeping obligations, and face potentially very heavy penalties. Which jurisdiction is wiser: Singapore or Hong Kong?
In case one is not convinced, Singapore’s CbCR filing would be done by sending the CbCR in XML format to the IRAS simply by email.
Tax-imposing jurisdictions would care more about CbCR because they may be able to detect BEPS risks. Tax Havens, however, are introducing CbCR regulations mainly to satisfy the demands of the international community through their participation in the OECD Inclusive Framework. One would expect that Tax Havens would make the process simple and just do the collection and exchange of the CbCR. Not so. The British Virgin Islands (BVI) issued the CbCR Guidance Notes on 19 February 2019 which requires the MNE Groups to provide details of each BVI CE, including those being tax residents elsewhere, on an Excel template.
BVI CbCR Registration
It is probable that the designers of CbCR did not foresee the difficulties and trouble faced by MNE Groups for trying to meet the CbCR notification and filing requirements. Maybe they do not care because in their minds, the MNE Groups have been avoiding taxes and it is time to pay off. It can be foreseen that the tax offices, especially in the OECD countries, will soon announce that the CbCR is leading to successful tax audits recovering millions in taxes. If that is not happening, the scope of CbCR may be extended upon review in 2020, requiring MNE Groups to disclose more information, and lowering the revenue thresholds so that more MNE Groups will need to comply. More resources will have to be deployed by tax offices and MNE Groups to deal with CbCR.
Tax Tips
Readers should by now have an idea of how CbCR is going to hit like a tsunami, except that there is nowhere to hide if the revenue threshold is breached. The best advice is to start preparation early, especially for those MNE Groups that are about to breach the EUR750 million threshold soon. Pick the right Project Manager (we can help!) and do a Dry Run would be the best tips for handling CbCR compliance.
Readers should note that the objective of this article is to highlight the key provisions in the CbCR Rules. For completeness, Readers are advised to seek professional assistance to enhance their understanding of the rules, their obligations and the penalty provisions.
Lastly, answers to the true or false questions:
CEs refer to entities that the UPE owns 50% or more. FALSE
Representative Offices or Branches with separate accounts are themselves CEs. TRUE
“Revenue” includes capital gains. TRUE
Related parties transactions can be eliminated for reporting. FALSE
Income tax paid does not include foreign taxes. FALSE
A CE that left the group during the year (e.g. disposed of) can be excluded from the CbCR for that year. FALSE
The number of employees includes independent contractors. TRUE
The Tax Identification Numbers (taxpayer file number) and addresses of CEs are not required for CbCR filing. FALSE
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 26 February 2019: https://manageyourtax.com/HKEJ Forum 20 )
The last issue of Tax Tips (The Final Days of Tax Havens – 10 December 2018) discussed the paper “Resumption of Application of Substantial Activities Factor to No or Only Nominal Tax Jurisdictions” (the “Paper”) issued by the OECD Inclusive Framework on BEPS Action 5, and forewarned the changes ahead: tax haven companies will be required by law to hire an adequate number of full-time qualified employees and incur an adequate amount of operating expenditure to carry out the activities that they claim to be engaged in.
Tax Havens including the well-known Cayman Islands and the British Virgin Islands (BVI) have swiftly introduced economic substance legislation. Cayman Islands passed The International Tax Co-operation (Economic Substance) Law, 2018 on 17 December and the BVI’s Economic Substance (Companies and Limited Partnerships) Act, 2018 was passed into law on 19 December 2018. These laws have become effective on 1 January 2019.
The rush to pass these laws before the end of 2018 was due to the commitment made to the European Union (EU). The Cayman Islands and BVI, together with countries such as Bermuda, Guernsey, Jersey and Isle of Man were included in a list of countries whose tax policies and economic substance caused concern for the EU Code of Conduct Group (Business Taxation). These countries were given the deadline of 31 December 2018 to introduce laws (the “Economic Substance Law” hereinafter) to avoid blacklisting by the EU.
Economic Substance Law
The economic substance required by the EU is basically identical to those set out in the Paper. Although the Economic Substance Laws have been passed, the Tax Havens still need to wait for the EU to confirm that the EU requirements have been met. However, from the reports on the visit by the OECD representatives (including the Director of the Centre for Tax Policy and Administration Mr. Pascal Saint-Aman) to the Cayman Islands in early January 2019, it seems that things are on the right track. Although the legislation introduced by different countries are broadly similar, details are different and Readers using Tax Haven vehicles should study the specific legislation to analyse the impact.
Impact Assessment
Not all Tax Haven entities will be affected. Here are the general steps one could take to assess if a company shall comply.
Step 1: Is the company a “Relevant Entity”
The Economic Substance Laws generally apply only to entities that are not tax residents outside of the Tax Haven country (the Relevant Entities). For example, if a BVI company is registered to carry on business in Hong Kong, it will likely be regarded a tax resident in Hong Kong and thus out of scope for the BVI Economic Substance Law.
Step 2: Is the Relevant Entity conducting the “Relevant Activities” Corporates and individuals use Tax Haven entities for various activities but only the “Relevant Activities” are subject to the substance requirements. Generally, the geographically mobile activities such as the provision of intangibles (i.e., intellectual property (“IP”) related activities) and the below Non-IP activities would be considered the Relevant Activities:
Headquarters
Distribution centres
Service centres
Financing
Leasing
Fund management
Banking
Insurance
Shipping
Equity holding
Relevant Entities will likely be required to file notices to inform the authorities whether they are conducting Relevant Activities or not. Those conducting Relevant Activities will then need to provide information covering items such as income, expenses, assets, premises, management, employees and physical presence. If the economic substance of the Relevant Entity falls short of the requirements, it will be asked to make an improvement. Persistent failure to fulfil the substance requirement may be subject to fines and even result in being struck-off.
Step 3: Meeting the Economic Substance Requirement
In general, a Relevant Entity conducting any of the above Relevant Activities complies with the economic substance requirements if: (a)the Relevant Activity is directed and managed locally (i.e. in the Tax Haven);
(b)having regard to the nature and scale of the relevant activity:
there are an adequate number of suitably qualified employees in relation to that activity who are physically present locally;
there is adequate expenditure incurred locally;
there are physical offices or premises as may be appropriate for the core income-generating activities; and
where the Relevant Activity is IP business and requires the use of specific equipment, that equipment is located locally; and
(c)the Relevant Entity conducts core income-generating activity. A pure equity holding entity, which carries on no Relevant Activity other than holding equity participations in other entities and earning dividends and capital gains, are subject to the reduced requirement and would be considered to have adequate substance if it:
(a)complies with its statutory obligations under the relevant company laws; and (b)has adequate employees and premises for holding equitable interests or shares and, where it manages those equitable interests or shares, has adequate employees and premises for carrying out that management.
On the other hand, more stringent rules apply to high-risk intellectual property holding companies.
As to what is “adequate”, one has to wait for the details to be announced by each country. The Mauritius example mentioned in Tax Tips (18) would give some indications of what is to come.
Outsourcing of Core Income Generating Activities
The economic substance requirements generally allow for outsourcing of the core income generating activities to third-party within the jurisdiction. The Relevant Entity must, however, be able to prove that it is able to monitor and control the core income generating activities being carried out are conducted locally.
The below flowchart downloaded from the Jersey Government website is a good reference on how the laws work in general.
No-where Income
The Common Reporting Standard (CRS) and Economic Substance Laws are bringing tax residencies of companies and individuals into the limelight. Hong Kong businesses are faced with questions from their bankers that ask them to identify the tax residency of their Tax Haven companies which have bank accounts in Hong Kong. Thanks to creative tax planning advice Hong Kong businesses acted on in the past, many of them use the bank accounts in the following situations:
There is a group company in Mainland China manufacturing goods for domestic sales. Orders of overseas customers are accepted in China and are shipped out without export declaration. The overseas customers pay to the Hong Kong bank account of the group BVI company, and some of the cash received would be used to pay Hong Kong suppliers who provide the raw materials in China. These sales and purchases would not be booked by the manufacturer in China.
Services are provided in Hong Kong or China to overseas clients and they are asked to pay to the Hong Kong bank account of a BVI company. Income is booked in the BVI company while the costs of services are incurred in Hong Kong or China with tax deduction allowed unchallenged.
IPs such as brands, trademarks, designs, rights etc are owned by BVI companies and earning hefty royalty income from group companies or unrelated parties, while the work related to the development, exploitation, maintenance, protection and enhancement of the IPs are carried out in Hong Kong, and the costs of such activities have been fully tax-deducted.
In the above examples, there would be under-reporting of income as profits have been shifted to entities that do not carry out value-creation activities. Once the tax offices in Hong Kong or China have become aware of the situations (which has become more likely these days with all the reporting and information exchange arrangements), they may, for example, treat the BVI companies as carrying on business in Hong Kong or managed and controlled in China, as the case may be, and assess tax on the under-reported amount and impose heavy penalties. On the other hand, from now on the groups in question also need to maintain substance of these BVI companies in the BVI or they risk the companies being struck-off. Things will become more complicated if the shareholders of the companies become Chinese tax residents by spending 183 days or more in China in a calendar year.
Tax Tips
As mentioned in Tax Tips (1), “Base Erosion and Profit Shifting” (BEPS) refers to the tax planning strategy of multinational groups (big or small) making use of differences and mismatches of tax rules across different countries and artificially transferring profits to low or no-tax jurisdictions with little or no economic activity. The pressure now felt by taxpayers is indeed the intended effect of OECD’s project against BEPS. At the same time, the compliance costs of Tax Haven entities are rising. Taxpayers should take action to restructure their operations and shift profits back to where the activities are. There will be an increase in tax burden, but a managed transition would help minimise the tax costs and avoid heavy penalties: tax offices like to punish aggressive taxpayers with the highest penalties.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 24 January 2019: https://manageyourtax.com/HKEJ Forum 19)
What would you do if every tax haven (e.g. BVI) company under your control is required by law to hire full-time qualified employees there and incur an adequate amount of operating expenditure to carry out the activities that they claim to be engaged in?
BEPS Action in action
In Tax Tips (13), the issue of tax residency of tax haven companies was discussed. Smart corporates will be able to ensure that the tax residencies of their tax haven entities are properly managed and thus would not create tax exposures. That does not necessarily mean that these companies can continue to book un-taxed profits with no substance. The BEPS machine is not stopping.
Last month, the OECD Inclusive Framework on BEPS: Action 5 issued a paper called “Resumption of Application of Substantial Activities Factor to No or Only Nominal Tax Jurisdictions” (the “Paper”), which sets out the substance requirements for tax havens. To the tax havens around the world, this Paper could be the last straw on the camel’s back (incidentally, tax havens such as the BVI, Cayman Islands etc are members of the Inclusive Framework).
Background
The OECD issued the report “Harmful Tax Competition: An Emerging Global Issue” in 1998 (“the 1998 Report”) setting out a framework for approaching the perceived problem that certain no or only nominal tax jurisdictions (i.e., tax havens) and harmful preferential tax regimes “affect the location of financial and other service activities, erode the tax bases of other countries, distort trade and investment patterns and undermine the fairness, neutrality and broad social acceptance of tax systems”. The 1998 Report called this “harmful tax practices,” and built a framework to assess these practices. The aim was to deliver a level playing field between jurisdictions in a context where taxpayers can easily relocate their mobile activities in response to tax considerations.
The framework for assessing whether a jurisdiction is a tax haven is based on four criteria:
(a) whether a jurisdiction imposes no or only nominal taxes;
(b) lack of effective exchange of information;
(c) lack of transparency and
(d) the absence of a requirement that the activity be substantial.
Notwithstanding, in 2001 the Forum on Harmful Tax Practice decided to only determine whether or not a jurisdiction was considered uncooperative on the basis of the first three criteria, and focused on making them cooperative and transparent.
With the implementation of BEPS Action 5 and the peer review process to ensure tax breaks are only offered to substantive activities and only if they do not pose risks of harmful competition to others, the focus is now shifted to ensure that business activity does not simply relocate to tax haven in order to avoid the substance requirements. Against this background, the Inclusive Framework has decided to apply the Substantial Activities Requirements for tax havens.
The Scope of the Substantial Activities Requirements
The types of activities that are within the scope of the Substantial Activities Requirements are geographically mobile activities such as the provision of intangibles (i.e., intellectual property (“IP”) related activities) and Non-IP activities which includes headquarters, distribution centres, service centres, financing, leasing, fund management, banking, insurance, shipping and holding companies.
What are the Substantial Activities Requirements
Non-IP-Related
For income from income not related to IP (“Non-IP Income), tax havens would be required to introduce laws to:
(i)define the core income generating activities for each relevant business sector;
(ii)ensure that the activities are undertaken by the entity (or are undertaken in the jurisdiction);
(iii)require the entity to have an adequate number of full-time employees with necessary qualifications and incurring an adequate amount of operating expenditures to undertake such activities; and
(iv)have a transparent mechanism to ensure compliance and provide an effective enforcement mechanism of the laws.
IP-Related
For income related to IP (“IP Income) derived from patents or similar assets, the core income generating activities would be the conducting of research and development activities with an adequate number of qualified full-time employees and adequate amount of operating expenditures. A similar requirement would apply where an entity is exploiting marketing IP assets such as trademarks, where the core income generating activities are branding, marketing, and distribution.
In other cases of IP Income, the entity would need to demonstrate that it is conducting strategic decision making, managing and bearing the principal risks relating to the development and subsequent exploitation of the IP asset, or carrying on the underlying trading activities through which the asset is exploited, with the adequate number of qualified full-time employees and an adequate amount of operating expenditures.
IP Income – Higher risk scenarios
Higher risk scenarios would be cases that involve related parties outside of the tax haven where (i) the entity has acquired the IP asset from related parties or through the entity funding research and development activities which took place outside the tax haven; and (ii) the IP asset is licensed or sold to related parties, or the exploitation is conducted by related parties outside the tax haven (e.g. foreign related parties are paid to develop and sell a product in which the intangible asset is embedded).
An entity in a higher risk scenario could meet the substantial activities requirements by providing evidence that there was, and historically has been, a high degree of control over the development, exploitation, maintenance, enhancement and protection (the DEMPE functions) of the intangible asset, exercised by an adequate number of full-time employees with the necessary qualifications that permanently reside and perform their activities in the tax haven. This would need to be demonstrated by providing additional information including:
detailed business plans which demonstrate the commercial rationale for holding the IP assets in the jurisdiction;
employee information, including the level of experience, type of contracts, qualifications, and duration of employment; and
evidence that decision making is taking place within the jurisdiction, rather than periodic decisions of non-resident board members.
Ensuring Compliance
To ensure compliance, tax havens would need to:
Set up a mechanism to collect various information from entities including details of the core income generating activities, the amount and type of gross income and expenses, the assets and premises held in the course of carrying out the business, and the number of full-time, qualified employees.
Set up a sanction mechanism that is rigorous, effective and dissuasive to take action in the event an entity failed to meet the substantial activities requirements. Sanction mechanism could include striking an entity off the register. The tax havens would also need to continue enforcement efforts and remedy any shortcomings in the enforcement process.
For any entities that do not comply with the substantial activities requirements, tax havens would be required to spontaneously exchange all relevant information with the jurisdictions of residence of the immediate parent, ultimate parent, and ultimate beneficial owner.
The effectiveness of the information collection and exchange mechanism is to be reviewed in 2022.
What about Holding Companies?
As discussed in Tax Tips (13), tax haven company is the ideal type of vehicle for investment holding, i.e. holding equity participations and earn only dividends and capital gains. Such companies are recognised in BEPS Action 5 that they may not require much substance in order to exercise their main activity of holding and managing equity participations, and therefore is less of a concern from BEPS’ perspective. The Substantial Activities Requirements on investment holding companies are that they respect all applicable corporate law filing requirements and have the substance necessary to engage in holding and managing equity participation (for example, by showing that they have both people and the premises necessary for these activities).
The Mauritius Example
Mauritius imposes nominal tax on companies with Category 1 Global Business Licence (“Cat 1 GBL”, commonly used as holding companies with access to the Mauritius tax treaty network). In the recent months, the Mauritius authorities issued new rules to bring about changes with effect from 1 January 2019. Under the new rules, Cat 1 GBL will be replaced by a new licence called Global Business Corporation (“GBC”) and the licensing conditions for GBC include, inter alia, carrying out of its core income generating activities at all times in, or from, Mauritius by:
Employing, either directly or indirectly, a reasonable number of suitably qualified persons to carry out the core activities; and
Having a minimum level of expenditure, which is proportionate to its level of activities.
In addition, the regulations provided the indicative core income generating activities and the minimum annual expenditure and employees (direct or indirect). For an investment holding GBC, the indicative minimum annual expenditure is USD12,000 and there is no minimum employee specified.
The Mauritius rules could be an example of what is forthcoming in other tax havens.
Tax Tips
Subject to the actual regulations to be introduced by the tax havens, the requirement that the entities in tax havens should maintain “an adequate number of qualified full-time employees and adequate amount of operating expenditures” and the threat of information exchange is likely sufficient to kill most tax haven entities earning IP or Non-IP Income (except for investment holding companies). Corporates that have not already restructured the activities to “normal tax jurisdictions” should speed up their review process and take action.
As to investment holding, which probably is a major business activity of most tax havens, corporates should follow the development closely and react to that accordingly. It is foreseeable that the OECD may accept more lenient substance requirements in order not to hurt the economies of the tax havens too significantly. The introduction of requirements on annual minimum expenditure even full-time employees will reduce the attractiveness of tax haven. As these are real additional costs of setting up investment holding companies, corporates should consider consolidating the group holding structures to eliminate duplicated costs, if not pulling out completely. The days of letterbox and brass plate companies appear to be limited.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 10 December 2018: https://manageyourtax.com/HKEJ-Forum-18)
Many people may have forgotten about the “Summit on New Directions for Taxation” held in October last year. In his speech for the event, the Financial Secretary Mr. Paul Chan said that “the most important aspect of today’s Summit is the discussion on how taxation (policy) can play a role in the economic development (of Hong Kong) in multiple directions”, and praised that “our tax system is simple, provides certainty, and it is implemented consistently”. The Financial Secretary also mentioned that the Tax Policy Unit set up in April 2017 is working at full speed, demonstrating the determination of the Government to actively pursue economic growth and development of industries through tax policies.
The Government has indeed done a lot of work on taxation in the past year. Some are for the implementation of the BEPS Minimum Standard (such as the transfer pricing regulations), and some relate to the expansion of industries, such as the super-deduction on research and development expenditure. This issue of Tax Tips discusses Section 15F Sums derived from intellectual property by non-Hong Kong resident associates (“15F”) of the Inland Revenue Ordinance (“IRO”) hidden in the transfer pricing regulations under Inland Revenue (Amendment) (No. 6) Ordinance 2018. 15F was passed by the Legislative Council and is effective from 1 April 2019 onwards.
What Does 15F Say
In simple terms, when a person (say a Hong Kong company, “HK Co”) performs any of the development, enhancement, maintenance, protection or exploitation (collectively as “DEMPE”) activities in Hong Kong for any intellectual property (“IP”), that person would be regarded as having contributed to the value creation of the IP. If a non-Hong Kong associated person (say “X Co”) receives a sum for the exhibition, use or imparting of the IP or the rights of the IP inside or outside Hong Kong, a sum associated with value contributed by HK Co (the “relevant sum”), if not already subject to Hong Kong profits tax, would be deemed as Hong Kong sourced income of HK Co and subject to profits tax.
The original text of 15F* can be found here for Reader’s easy reference.
According to 15F, no matter HK Co is the owner of the IP or not, provided that HK Co has performed any of the DEMPE activities for an IP to contribute value to it, including carrying out the relevant functions, providing assets, or taking up the relevant risks, and the offshore associate (X Co) receives “a sum” from the IP and has not paid any Hong Kong profits tax on any part of the sum, 15F empowers the Hong Kong Inland Revenue Department (“IRD”) to deem the relevant sum as income of HK Co and taxed accordingly.
Readers may already have questions in mind about 15F, some of which may be covered below:
What is the meaning of “a sum”? Is it restricted to mean an identifiable sum received by X Co for the use of the IP? If the IP is a brand, and X Co uses the brand to sell goods, is the sales revenue “a sum”?
Would DEMPE activities performed by HK Co before 1 April 2019 be included in the analysis?
How would the IRD determine the “relevant sum” if the IP is used by various subsidiaries or joint ventures of X Co in different countries, and HK Co is unable to obtain the detailed information of the income of these companies? Even if HK Co is able to provide the information, how would the IRD assess the value contributed by these companies in order to accurately calculate the “relevant sum”?
Under the IRO, is HK Co legally bound to provide information of X Co and the various subsidiaries or joint ventures in different countries to prove whether these companies have each received “a sum” and the amounts?
If HK Co is the owner of the IP and transferred the IP to X Co at an arm’s length price, why would HK Co not be exempt from 15F?
Income of X Co and the various subsidiaries or joint ventures in different countries derived from the IP may have been subject to tax in the relevant countries; if part or all of the income is deemed to be taxable income of HK Co and subject to Hong Kong profits tax, the issue of double taxation would arise. As the double taxation is not arising from a transaction between two jurisdictions but it stems only from the deeming provisions of the IRO, the issue cannot be resolved on a bilateral basis even if Hong Kong and the other side(s) has a Double Tax Arrangement (“DTA”) signed. How would the IRD deal with this issue? Would HK Co be required to provide evidence of tax payment by the various offshore companies in order to avoid an assessment under 15F?
How would the statutory auditors ascertain the tax provision of the X Co Group (including HK Co, all together referred to as “X Group”)? If there is a multinational group interested to acquire X Group, how would the buyer assess the tax exposure of X Group under 15F?
The above may only be some of the questions created by 15F.
Facebook’s Data Centre
Last month, Facebook announced that it will invest US$1 billion to build its 15th data centre, the first in Asia, in Singapore. Tax consideration is not mentioned in the media reports covering this news. It can be imagined that some kind of DEMPE activities must be carried out in the data centre, creating certain IP to be used in different parts of the world. If Facebook were to select Hong Kong as the location for the data centre, would they be worried about the threat of 15F?
Would multinational groups or other tech giants be scared away from Hong Kong because of 15F when they select the location to invest in Asia to carry out DEMPE activities related to IP? It is entirely possible that multinational groups, in any industry, may choose to avoid Hong Kong because of tax risks and uncertainties created by 15F!
Voice Against 15F
When the Inland Revenue (Amendment) (No. 6) Bill 2017 (“the Bill”) was gazetted last year, many professional organisations made submissions to the Bills Committee voicing out concerns on 15F, some even requested that 15F be removed. The Government responded that there are companies that transfer legal ownership of IPs to associates in low-tax jurisdictions where no DEMPE activities are performed but earn the IP income. In order to align taxation with value-creation, which is the objective of BEPS, the Government is introducing 15F to combat such profits shifting activities. The Government claimed that DTA partners are adopting a similar approach to transfer pricing, and genuine commercial transactions would not be affected.
Lastly, in order to pass the Bill (and 15F), the Government has said that various issues will be clarified in a Departmental Interpretation and Practice Notes (“DIPN”) to be issued, and deferred the commencement date of 15F to 1 April 2019 to allow more lead time to taxpayers.
Tax Tips
The scope of 15F is very wide and it is not a specific anti-avoidance provision. 15F would apply even if the taxpayer is not engaged in any tax avoidance. Under the shadow of 15F, the statement that “our tax system is simple, provides certainty, and it is implemented consistently” would no longer be true. 15F discourages companies to conduct IP-related activities in Hong Kong, which is in direct contradiction to the Government policy of encouraging research and development activities in Hong Kong.
If the law is flawed, DIPN would not make it flawless. Therefore, the best approach to 15F is to ask the Government to repeal it or amend it substantially such that it only applies in limited circumstances. The Author would raise the demand through the appropriate professional organisation. In the meantime, Readers may also raise the issue via appropriate means.
If the Government refuses to amend 15F, the only way to eliminate tax risk is not to carry out any DEMPE activities in Hong Kong, which is basically an impossible task. Companies should thus wait for the DIPN before deciding the action to take.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 9 October 2018: https://manageyourtax.com/HKEJ Forum 16)
The rise of globalisation has led to substantial increase in cross-border related party transactions (“RPTs”). For example, by moving a factory to a foreign country, businesses will be scrutinised by at least two tax jurisdictions on RPTs in purchases, sales, intangibles, financing, management fees, shared services etc. by tax offices in at least two jurisdictions. Businesses are expected to provide documentation to support the transfer pricing of each RPT. With the BEPS project, the amount of pressure on meeting the tax offices’ expectation on transfer pricing has increased to the highest.
The OECD, being the major driving force behind BEPS, have updated the OECD Transfer Pricing Guidelines for Multinational Enterprises and Tax Administrations in July 2017 (“TP Guidelines”), which is over 600 pages long, to help reduce possible differences between businesses and tax offices in determining the approach and factors to be considered on what should be the arm’s length price of RPTs.
This Article is based on the Hornbach case (C-382/16), ruled by the Court of Justice of European Union (“CJEU”) on 31 May 2018 to look at a relatively small, but common, RPT, discusses what issues businesses would face and the takeaways from the case that can help businesses strategize for future RPT of this kind.
The Hornbach Case
Background
Hornbach-Baumarkt AG (“Hornbach”) is a public limited company established in Germany which operates do-it-yourself (DIY) and building materials shops in Europe. In 2003, Hornbach, through a German and a Dutch intermediate holding companies (“German Holdco” and “Dutch Holdco” respectively), held an indirect shareholding of 100% in two operating companies established in the Netherlands, Sub1 and Sub2 (collectively ‘the Subsidiaries”).
The Subsidiaries had negative equity capital and required, respectively, in order to continue their business operations and to finance the planned construction of a DIY store and garden centre, bank loans of EUR 10,057,000 as regards Sub1 and of EUR 14,800,000 as regards Sub2. The financing bank had made the granting of the loans contingent on the provision of comfort letters containing a guarantee statement from Hornbach. In September 2002, Hornbach provided the comfort letters gratuitously. In the comfort letters, Hornbach undertook vis-à-vis the financing bank to refrain from divesting of or changing its shareholding in the Dutch Holdco and, in addition, undertook to ensure that the Dutch Holdco would likewise refrain from divesting of or changing its shareholding in the Subsidiaries without giving the bank written notice thereof at least three weeks prior to such divestment or change. Furthermore, Hornbach irrevocably and unconditionally undertook to fund the Subsidiaries in such a way as to enable them to meet all of their liabilities. Accordingly, it had to make available those companies, as necessary, the requisite funds to enable them to settle any liabilities towards the funding bank.
The diagram below illustrates the case background.
The Dispute
Taking the view that unrelated third parties, under the same or similar circumstances, would agree on remuneration in exchange for granting the guarantees, the German Tax Office decided that, according to German tax laws, the income of Hornbach had to be increased by an amount corresponding to the presumed amount of the remuneration for the guarantees granted and accordingly amended the corporation tax and the basis of calculation for that company’s business tax for the year 2003. The Tax Office, therefore, corrected the amount of taxable income of Hornbach as a result of the guarantees granted to Sub1 and Sub2 by EUR 15,253 and EUR 22,447 respectively.
Hornbach objected to the assessment which was rejected by the German Tax Office. Hornbach brought an action against those decisions before the German Finance Court. In the context of that action, Hornbach argued that the relevant German tax law leads to unequal treatment in cases involving domestic and foreign transactions since, in a case involving purely domestic transactions, no corrections of income would be made in order to reflect the presumed amount of the remuneration for guarantees granted to subsidiaries, which could be regarded as a restriction on freedom of establishment. In addition, the tax law does not contain any provision concerning the opportunity to present commercial justification in order to explain a non-arm’s-length transaction. In the present case, according to Hornbach, commercial reasons relate to supportive actions to replace the equity capital of the Subsidiaries explain why no remuneration was given for the comfort letters. The Tax Office contended that the taxpayer had the opportunity to present evidence of the reasonableness of the transaction carried out, and the concept of “commercial justification” within the meaning of the relevant tax laws must be interpreted in the light of the principle of free competition which, by its nature, rules out acceptance of economic reasons resulting from the position of the shareholder. The German Finance Court was uncertain as to (1) whether the relevant German tax law was compatible with the freedom of establishment, and (2) whether commercial justification may be presented as evidence and, in particular, whether any commercial justification may include economic reasons resulting from the very existence of a relationship of interdependence between the parent company resident in the Member State concerned (Germany) and its subsidiaries which are resident in another Member State (the Netherlands).
Consequently, the Finance Court referred the questions to the CJEU for a preliminary ruling.
The Ruling
Readers would see that the CJEU was not asked to rule whether the commercial justification presented by Hornbach was sufficient in supporting the alleged “non-arm’s length” transaction. While CJEU ruled that the German tax law was compatible with the freedom of establishment, and in the case at stake, it is for the German Finance Court to determine whether Hornbach was in a position, without being subject to undue administrative constraints, to put forward elements attesting to a possible commercial justification for the transactions at issue in the main proceedings, without it being precluded that economic reasons resulting from its position as a shareholder of the non-resident company might be taken into account in that regard. In other words, the relationship between Hornbach and Subsidiaries shall be taken into account in assessing the commercial justification for the non-arm’s length transaction, which was what the German Tax Office refused to do. Therefore, whether Hornbach would eventually win the case is uncertain and it is worth keeping an eye on the development.
Food for Thoughts
This case has provided some food for thoughts as to whether a parent company should charge its subsidiary for support, such as the guarantee in this Hornbach case. Here are some of the key comments from CJEU:
It is clear that Subsidiaries had negative equity capital and the financing bank made the granting of the loans required for the continuation and expansion of business operations contingent on the provision of comfort letters by Hornbach.
In a situation where the expansion of the business operations of a subsidiary requires additional capital due to the fact that it lacks sufficient equity capital, there may be commercial reasons for a parent company to agree to provide capital on non-arm’s-length terms.
Furthermore, it should be noted that, in the present case, no argument relating to the risk of tax avoidance has been advanced.
Accordingly, there may be a commercial justification by virtue of the fact that Hornbach is a shareholder in Subsidiaries, which would justify the conclusion of the transaction at issue in the main proceedings under terms that deviated from arm’s-length terms. Since the continuation and expansion of the business operations of those foreign companies was contingent, due to a lack of sufficient equity capital, upon a provision of capital, the gratuitous granting of comfort letters containing a guarantee statement, even though companies independent from one another would have agreed on remuneration for such guarantees, could be explained by the economic interest of Hornbach itself in the financial success of Subsidiaries, in which it participates through the distribution of profits, as a shareholder, in the financing of those companies.
These comments would be quite helpful to companies in structuring their transfer pricing strategy and future defense.
Applications
It is common for the Ultimate Parent Entity (“UPE”) of a Multinational Enterprise (“MNE”) to provide guarantees to banks for funding to the MNE’s subsidiaries. Whether the UPE should charge for a guarantee fee or not is often an issue of debate. In the Hornbach case, the German Tax Office obviously considered that Hornbach should have charged a guarantee fee (in this case, the rate appears to be 0.15%p.a. on the loan amount) and therefore adjusted Hornbach’s taxable income upward. That brings up a few questions for MNEs facing similar situation: (1) when no third party would be in the position to provide the same guarantees, is this really an arm’s length price for the guarantee; (2) can the tax office make adjustment when there is no evidence of tax avoidance; and (3) would the tax office on one side (the Dutch tax office in this case) allow a corresponding deduction for deemed guarantee fee income imposed on the other side (Germany) and how to achieve that? These are very difficult questions that require tax and legal analysis of the tax laws and tax treaties of the jurisdictions involved at that point in time. MNEs are often less interested in what is the correct technical answers, but more interested in how to resolve the matter in the least expensive manner.
An arm’s length price is the consideration that unrelated parties would agree upon in the same or similar circumstances (and that is perhaps why the German Tax Office argued that the concept of “commercial justification” within the meaning of the relevant tax laws must be interpreted in the light of the principle of free competition which, by its nature, rules out acceptance of economic reasons resulting from the position of the shareholder). However, in the Hornbach case and often in real life situations involving parental guarantees, no third parties would be in the position to provide similar guarantees to funding bank because they would not be in the position to guarantee that they would “refrain from divesting of or changing its shareholding” in the Subsidiaries. If there can be no comparables, how does anyone derive an arm’s length price?
In Chapter 1: The Arm’s Length Principle of the TP Guidelines, Para 1.11. pointed out exactly the issue, “A practical difficulty in applying the arm’s length principle is that associated enterprises may engage in transactions that independent enterprises would not undertake. Such transactions may not necessarily be motivated by tax avoidance but may occur because in transacting business with each other, members of an MNE group face different commercial circumstances than would independent enterprises. Where independent enterprises seldom undertake transactions of the type entered into by associated enterprises, the arm’s length principle is difficult to apply because there is little or no direct evidence of what conditions would have been established by independent enterprises. The mere fact that a transaction may not be found between independent parties does not of itself mean that it is not arm’s length.”
Does the Para 1.11 help? Not much, because the guidelines is not saying that tax office have to accept whatever the price set by the taxpayers in this situation, even though no arm’s length comparable price can be found and “no adjustment” is probably the right answer. Therefore, disputes would still arise, as we see in the Hornbach case.
The Reality
There are tax and non-tax reasons for MNEs to consider whether to charge a guarantee fee. In the Hornbach case, Subsidiaries needed funding, which could come from Hornbach in the form of capital or loan via the intermediate holding companies (from internal funds or external borrowing), or from bank borrowing directly by the Subsidiaries as in the present case. MNEs would need to review the cash flow, cost of capital and follow the internal policies in deciding the choice of funding, especially for larger amounts.
The reason for not charging a guarantee fee in the Hornbach case was not disclosed. It could be due to the reason that Subsidiaries may not be able to generate sufficient cash flow to pay the guarantee fee, which could create further funding issue for the group and may therefore incur additional interest expense.
In some situations, UPE may want to charge a guarantee fee. For example, the UPE holds a majority stake in the subsidiary and is providing the letter of comfort to the bank funding the subsidiary covering the full amount of the loan, while the minority shareholder (the “MI”) does not need to provide the proportionate guarantee. The MI would therefore be enjoying a free ride in terms of the subsidiary obtaining the bank loan, often at an interest rate lower than if it was borrowing on a standalone basis, and thus the MI would eventually receive a higher return on investment while the risk is borne by the UPE alone. In this situation, the UPE would often want to charge a guarantee fee to the subsidiary to eliminate this free ride.
The UPE may also charge a guarantee fee if overall tax savings of the group could be created, after taking into account the tax deduction benefit of the subsidiary, withholding tax that may be imposed, and the income tax that the UPE may be subject to after considering the tax credit available on the withholding tax paid. MNEs should fully recognise the BEPS risks for taking such approach.
Tax Tips
In tax jurisdictions where there are statutory transfer pricing requirements (which will include Hong Kong soon), in deciding whether to charge a guarantee fee to the subsidiary when parent guarantee is provided, the thought process should cover the following:
Consider from purely commercial perspective whether there is a preference for charging or not charging a guarantee fee. This preference is the best defense against tax avoidance accusation.
Consider the tax implications of charging and not charging, including local practices, tax treaty applications, case law and compliance costs, and assess the risk of the two alternatives.
Determine the approach based on commercial preference, costs, benefits and risks analysis.
Prepare all necessary supporting documentations (e.g. board minutes, communication with external parties such as banks, loan agreements, guarantee fee agreement and transfer pricing reports) which must include the commercial rationale of the approach taken.
One of the significance of the Hornbach case is the CJEU comment that the parent-subsidiary relationship could justify terms that deviated from arm’s-length terms. Indeed, only the parent company would provide guarantees to banks for financing its subsidiaries, especially at the early development stage of the subsidiaries when banks refuse to lend without a parental guarantee. Such action should be regarded as an investment activity instead of a service. The parent, by providing the guarantee, can earn its return by sharing the future profits of the subsidiary, in just the same way as providing capital to fulfil the funding need. Unfortunately, many tax offices view guarantee as a service, however it arises. Therefore a risk assessment is needed on the attitude of the tax office involved when the UPE decides not to charge a guarantee fee.
Notwithstanding, the underlying nature of the guarantee could change to service when the subsidiary is capable of obtaining standalone financing (i.e. banks would be willing to lend to the subsidiary directly without parental guarantees), and the parental guarantee is provided for the purpose of reducing the financing costs of the subsidiary because banks would lend cheaper due to the lower risks. As the subsidiary would be truly benefiting from the guarantee, it may justify the charging of a guarantee fee from tax perspective.
Along the lines discussed above, MNEs may consider the following transfer pricing strategy on guarantee fees:
The above strategy would help MNEs make decision on whether to charge a guarantee fee. One should note that this may not necessarily be agreed by the tax office. If it is decided that a guarantee fee should be charged, finding the so-called arm’s length amount is another challenge, especially when no third party would enter into the same or similar transaction, as in the Hornbach case. For small amount of adjustments, the cost and administrative burden of searching the right amount is sometimes unproportionately high. If the method of how the German Tax Office derive the guarantee fee of 0.15%p.a. would be disclosed, it would be of good reference to many MNEs.
The problem with transfer pricing in practice is that there are many assumptions in the whole process, and the tax offices often do not understand the commercial rationale behind and they go after companies just because they smell revenue. After lodging objections which the tax offices have rejected, in practice companies would not go to the court in view of the cost and benefits, and may instead restructure the transactions to make the issue go away. It is not often that the taxpayer, like Hornbach in this case, would go to the court for the relatively small amount of tax involved, and those who seek fair treatment deserve much appreciation and applause from people who are concerned.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 14 June 2018: https://manageyourtax.com/HKEJ Forum 12)
A Chinese merger & acquisition case with an eye-catching title has recently been reported on WeChat – “Tax Office Analysed Enterprise Group Packaged Transfer – ChangChun State Tax Bureau Solved the Difficult BEPS Question Posed by Packaged Share Transfer Using Tax Haven”. The Article stated that the source is from the ChangChun State Tax Bureau. The taxpayer was assessed additional Corporate Income Tax (“CIT”) of RMB 2.22million plus interest of RMB 310,000. Although not many details were provided in the Article, there are a few takeaway points that may be helpful to the readers.
Summary of the Article
Case Background
In February 2010, the Chinese Party, a ChangChun Company, formed a 50/50 Sino-Foreign Equity Joint Venture (“JV”) in ChangChun with a Hong Kong Company (“HKCo”) for the manufacture and sale of electronic products and parts of motor vehicles and other products. The shareholding structure is as follows:
In January 2014, HKCo signed a Sale and Purchase Agreement (“SPA”) with a US company (“USCo”) to transfer its shares in the JV and other assets and shareholdings in companies related to motor vehicle electronic business to the USCo. The disposal was packaged deal involving shareholdings in 20 companies. The USCo replaced HKCo as the 50% shareholder of the JV, as below:
There was only one SPA covering the packaged transfer (including the 20 companies). As this was a direct transfer of a Mainland entity, ChangChun tax bureau had the taxing right on the gains derived by HKCo on the JV share transfer. CIT filing was made on the JV share transfer on the basis of No-Gain-No-Loss.
Applicable Regulations
The share transfer was subject to Circular GuoShuiHan (2009) 698, which stated that when the foreign investor (actual controlling party) transfers shareholdings in companies located both inside and outside of China, the companies in China shall provide the SPA of the packaged transfer and the SPA for the transfer of each Chinese company to the in-charge tax bureau. If no separate SPA is available, the companies in China shall provide detailed information about each company being transferred, in order to precisely segregate the consideration of the transfer of each company involved. If it is not possible to precisely segregate the consideration, the in-charge tax bureau may adopt the reasonable method to adjust the transfer price.
The Investigation
The ChangChun tax bureau investigated the case and issued the “Notice on Tax Matters” to the JV requesting various information including: shareholding structure chart of the JV pre- and post-transfer, a report on the deal, method in determining the consideration, the SPA, separate SPAs for the individual companies, detailed information of each company included in the transfer, a chart showing the allocation of the consideration to each company transferred, the balance sheets, profit and loss accounts and cash flow statements of the JV for the previous 5 years, the medium-long term budget plan of the JV prepared in the year immediately before the share transfer, and an explanation of the commercial reasons for the packaged share transfer by the foreign investor. Through consolidating and analysing the information provided and conducting interviews, the tax investigation team found the following facts: (1) HKCo and USCo were unrelated parties, the deal was conducted at arm’s length, and there were commercial reasons for the packaged share transfer; (2) before the deal, the financial position, operating results and cash flow of the JV were satisfactory, there were no special circumstances that would prevent the JV from continued operation, and the future prospect was positive, such that there was a risk that the No-Gain-No-Loss filing position adopted by the JV would understate the value of the company and thus posed a tax risk; (3) as there were no separate SPAs for the companies being transferred and no detailed information on the other 19 companies were provided, it was not possible to determine the value of the JV through an allocation of the deal transfer price; (4) the packaged transfer had in effect created the situation where gains from the transfer of individual companies would not be realised in the jurisdictions where they were located, and with the gains booked by the HKCo in Hong Kong, resulted in the actual utilisation of the benefits of a tax haven.
Additional Tax Assessment
After detailed investigation and rounds of negotiations, as HKCo did not provide separate SPAs or detailed information of the companies transferred, it was agreed that the consideration for the transfer of the JV shall be adjusted based on a reasonable methodology. The taxpayer and the tax bureau agreed to perform a valuation on the JV. The Market Approach was rejected on the basis that there was no sufficient market data available, and since the JV was at a stage of healthy development, the Cost Approach (Asset-based Approach) was considered inappropriate. The two sides agreed to adopt the Income Approach. The JV was accordingly valued at RMB 161,169,400, and the gain on 100% share transfer would be RMB44,361,244. The 50% share being transferred would result in a gain of RMB22,180,622元, and the additional CIT of RMB 2.22 million plus interest of RMB310,000 were assessed.
Our Comments
In this particular case, the Mainland tax office has all the rights to assess income tax on gains derived from the transfer of the JV alone (although the background facts have not mentioned, it seems likely that the other 19 companies sold were not Mainland entities). To determine the standalone value of the JV, the Income Approach is generally adopted and is widely applied in China in similar situations. The discount rate and other assumptions would have a significant impact on the tax liability, and the discussion with tax office could drag on. Depending on the stage of discussion, taxpayers may need to consider the interest costs, if applicable, against the benefits of standing firm on their negotiation position.
Package sale is very common and there are good reasons for the acquirer to buy the lot. There could be various contractual relationships with external as well as internal parties established, banking covenants, employees, licences, regulatory concerns etc. If there are companies that the buyer does not want to acquire, those companies would be carved out. The transaction value must, therefore, reflect the combined value of the Group acquired from the Buyer’s perspective. There may not even be a deal if the acquirer is only allowed to buy one particular company of the target group.
The question, therefore, is how to factor-in the group value into the pricing of the entity that is subject to tax on share transfer (the JV in this case). The JV was not sold on a standalone basis. One could argue that the assessment of income tax on the sale of JV based on a standalone sale model is not reflecting the arm’s situation. Notwithstanding, as the Seller did not provide information on the 19 companies sold to the Mainland tax office, it is not unreasonable for the tax office to ignore the 19 companies and assess tax on the JV disposal based on the stand-alone valuation of the JV as in this case. The fact that the Seller filed the tax return on the JV disposal on a No-Gain-No-Loss basis probably reflected that the other 19 companies might not be performing well, and some might even be loss-making.
The tax on disposal is payable by the Seller. It is therefore very important for the Seller to correctly assess the tax impact of the transaction before the deal is closed. Filing the tax return of the JV disposal in this case on the basis of No-Gain-No-Loss would be a somewhat aggressive position to take if the JV is making a profit. If the Seller genuinely believed that the tax office would accept the filing position, he was probably ill-advised, which cost him RMB 310,000 of interests.
Tax Tips
Some helpful tips can be drawn from this case. Seller – In a merger & acquisition deal, the Seller is often the party responsible for reporting for tax in jurisdictions where the transaction would be taxable. The Seller should, therefore, consult with tax advisors to understand the obligations, exposure, and formulate a strategy to manage the tax filing obligations and position. In the JV case above, other than preparing for the worse case scenario, the advisor should be creative in coming up with arguments of why the deemed disposal price of the JV is less than what the tax office would like to assess.
For example, these days the tax offices around the world are keen on reviewing the value-chain of the group and split up the taxable profits accordingly. Would it be possible to perform a similar analysis on the target group and allocate the deal price to each company (or jurisdiction) according to their value contribution, and put the numbers down onto SPA? Maybe a non-Mainland entity of the group holds intellectual property rights and thus a larger portion of the value should be allocated to it, and thereby reducing the taxable profits of the JV? Thinking-out-of-the-box is just the starting point, establishing convincing arguments and provide solid supporting including contracts and analysis are the keys to success. Obviously, the taxpayer has to be careful in whether such analysis would create issues for the past, present, and future tax filings in different parts of the world.
Buyer – The Buyer would also have a vested interest in how much tax the Seller is to pay even after the deal is closed. Why? The deemed disposal value assessed by the tax office could become the stepped-up cost-base of the company acquired. In the future disposal of the same company, the Buyer would deduct the stepped-up cost-base of RMB 80,584,700 (50% of RMB161,169,400). In theory, the more tax the Buyer pays now, the less tax that the Seller would pay in the future. In the case of an indirect disposal involving Mainland entities, the Buyer may even have a withholding obligation on the tax that they Seller may need to pay under Public Notice 2015 No.7. The two sides must agree on action to be taken for completing the tax filing obligations. For indirect transfer case, even though the Buyer has no plan of disposal of the acquired companies in the foreseeable future, he should closely follow up with the Seller and obtain copies of the relevant tax filing records as soon as possible for two purposes: (1) be sure that the tax withholding obligation is no longer applicable; and (2) substantiate the cost-base of the Mainland company acquired.
Finally, it is interesting to note that the Article mentioned that “the packaged share deal transferred the gains to a tax haven, and avoided the reporting of tax at the location of the group entities”. According to the Article, Hong Kong is a tax haven, which is something that almost no Hong Kong taxpayer would agree. It reflects that some misunderstanding still exists between Hong Kong and the Mainland. Such misunderstanding would increase the challenges that Hong Kong taxpayers face when they negotiate with the Mainland tax authorities in a situation similar to this JV case. Also, in this particular case, as it is a Hong Kong company directly disposing of the equity in a Mainland enterprise, it is difficult to understand why there are BEPS concerns as mentioned in the Article. Given the mindset of the Mainland tax office as demonstrated in the Article, taxpayers should be prepared to fight the uphill battle in any tax negotiation.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 28 May 2018: https://manageyourtax.com/HKEJ Forum 11)
It was mentioned in the last issue that Hong Kong has become a part of the OECD BEPS “Inclusive Framework” and published the Inland Revenue (Amendment) (No. 6) Bill 2017 (the “Bill”) in the Gazette on 29 December 2017, in order to implement the “Minimum Standards” for the BEPS program in the Fiscal Year 2018/19. The Bill was passed in the Legislative Council on 4 July 2018. This issue examines how the implementation of the BEPS Action 13 “Transfer Pricing Documentation and Country-by-Country Reporting” under the “Minimum Standard” will affect Hong Kong taxpayers.
Large Hong Kong Multinational Corporations
Many large Hong Kong multinational corporations (“MNC”, Hong Kong resident groups headquartered in Hong Kong) have invested overseas. Many MNCs have been busy with complying with the BEPS Actions because they are subject to the overseas tax laws and many countries, especially the European countries, have already amended the tax regulations to incorporate the BEPS Actions. If their annual consolidated group revenues exceeded 750 million euros, the MNCs would likely have prepared the Country-by-Country Reporting (“CbCR”) and would have been filing notifications in different countries beginning the end of 2016, and by the end of 2017 file the CbCR in probably more than one country. In addition, they also need to prepare the Master File for transfer pricing, ready for inspection by tax bureaus worldwide. The Bill sets the threshold for CbCR at HK$6.8 billion. If the Bill is passed on schedule, Hong Kong’s major MNCs will have to decide whether they need to prepare the 2018 CbCRs based on whether their 2017 consolidated revenue exceeded HK$6.8 billion. By 31 December 2019, “Hong Kong Ultimate Parent Entity” shall submit the CbCR to the Hong Kong Inland Revenue Department (“IRD”). To make it more complex, MNCs need to assess whether Hong Kong can automatically exchange their CbCRs to the tax bureaus of their overseas operations. If not, these MNCs may also submit CbCRs individually in different countries, which can be an exhausting exercise.
To facilitate Readers’ understanding, I quickly summarise CbCR as follows. CbCR is a report consisting of three tables. Table 1 requires the reporting MNC to list out, by tax jurisdiction, the aggregate figures of various attributes of all entities of the MNC in that tax jurisdiction. The attributes are: (1) Revenue from Unrelated Party; (2) Revenue from Related Party; (3) Total Revenue; (4) Profits before Tax; (5) Income Tax Paid (cash basis); (6) Income Tax Accrued; (7) Stated Capital; (8) Accumulated Earnings; (9) Number of Employees; and (10) Tangible Asset (other than cash and cash equivalent). For example, an MNC group has 100 entities in Mainland China, then on the CbCR on the row for “Mainland China”, the MNC shall report the aggregated figure of each attribute for the 100 entities, translated into the reporting currency of the CbCR. Table 2 lists out every entity of the MNC group and report their tax residencies and main business activities. Table 3 is for reporting any other information such as exchange rates that helps users of the CbCR to better understand the report.
The CbCR may appear to be straight-forward, but if the MNC is very large, with operations in many jurisdictions and internally use more than one accounting software, it is not an easy task to compile all the figures correctly. Although the OECD has been issuing further guidance (while MNCs are already preparing the reports), there are numerous challenges faced by MNCs in preparing the CbCR. In the last issue of Tax Tips, it was mentioned that the concept of the BEPS program is to establish a modern international tax framework that allows companies to pay tax at the location of their real business activities and value creation. CbCR is designed to let all tax bureau worldwide to have a bird’s-eye view on the MNC group’s revenue, profits, assets, and people, so as to assess if there are tax risks (potential tax avoidance activities). Since the Bill proposed to penalise the MNC (and also the service provider engaged to prepare the CbCR for the MNC) for incorrect CbCR, the IRD should issue further detailed guidance on one hand, and be lenient to MNCs on the other hand, at least for the initial years, taking into account the difficulties in preparing the CbCR error-free.
All Hong Kong Companies
Large Hong Kong MNCs and many Small and Medium-Sized Enterprises (“SMEs”) will likely be required to prepare transfer pricing Master Files and Local Files. According to the Bill, if the company satisfies two of the below three conditions, it will have to prepare Local File for itself and Master File for the Group:
Total Amount of Revenue: HK$400 million
Total Value of Assets: HK$300 million
Average number of employees: 100
Notwithstanding, SMEs would be able to reduce compliance costs if they satisfy conditions set out in the Bill. Based on the type of transaction, provided that the amounts of controlled transactions are under the thresholds, no transfer pricing documentation shall be prepared for that relevant transaction. Insofar as domestic transactions between associated persons that do not give rise to actual tax difference (or domestic transactions involving non-arm’s length loans (e.g. interest-free loans) that are not carried out in the ordinary course of money lending or intra-group financing business), and provided that such transactions do not have a tax avoidance purpose, then the relevant persons will not be obliged to compute the income or loss arising from these transactions on the basis of the arm’s length provision in their tax returns and no corresponding assessment on that basis will be made by IRD. The Bill has therefore exempted domestic transactions from the preparation of transfer pricing documentation. As a related matter, therefore, the volume of domestic controlled transaction would also be disregarded in assessing if the company has breached the nature and volume threshold for preparing the documentation. If the company’s controlled transactions fall below all four thresholds, the company is exempt from preparing the Local File and Group Master File:
Transfers of properties (whether movable or immovable but excluding financial assets and intangibles) HK$220 million
Transactions in respect of financial assets HK$110 million
Transfers of intangibles HK$110 million
Other transactions HK$44 million
I prepared the below diagram to facilitate Readers’ understanding.
These thresholds seem clear, but as always, the devils are in the details. For example, what is meant by “total amount of revenue”? Is it only the top line revenue in the profit and loss account, or would it also include items such as asset disposal gains, exchange gains, interest income and dividend income? “Total value of assets” is relatively simple, but do not forget that if an enterprise leases assets under an operating lease, according to IFRS 16, to be implemented on January 1, 2019, lessees may need to book the value of the assets and companies are therefore more likely than before in breaching the threshold. As for the type of the company’s annual related party transactions, in the case of related party loans, is the threshold based on the loan amount or interest amount? It seems that some techniques are required in classifying related party transactions in order to decide whether the relevant transfer pricing documentation shall be prepared. To avoid any controversy and inconvenience, the tax authorities should formulate relevant guidelines as soon as possible.
As to the deadlines for preparing the Master File and Local File, the Bill requires such documents to be completed within 9 months after the end of the accounting period. Time is tight. Companies need to understand that preparing the two files are just the beginning, the critical part is what would the IRD do with the files. Also, the Bill is silent on how the provisions work together with the territorial system of taxation in Hong Kong. Future Tax Tips will look into the area.
A couple of side-points: during the BEPS Consultation in 2016 organised by the Financial Services and Treasury Bureau (“FSTB”), the thresholds of Total Amounts of Revenue and Total Values of Assets were proposed to be HK$100 million, without the exemption conditions mentioned above. Myself, various business and tax organisations reflected to the FSTB that the thresholds were too low, and that companies with small amounts of related party transactions should not be required to prepare the documentation. The Bill has reflected the comments made. On the other hand, as many Hong Kong companies have dealings with related parties in Mainland China, the above thresholds of controlled transaction were determined with reference to the thresholds in Mainland China for preparing transfer pricing documentation, so if companies have prepared documentation to satisfy the rules in Mainland China, the documents can be easily adapted to comply with the Hong Kong rules.
Tax Tips:
(1) : CbCR does not only apply to Hong Kong Ultimate Parent Entity. If a foreign group reaches the CbCR threshold, the Hong Kong Constituent Entities are required to comply with the Hong Kong notification rules and perhaps need to file the CbCR with the IRD.
(2) : The exemption of domestic transactions between associated persons that do not give rise to actual tax difference and do not have a tax avoidance purpose from the obligation to compute the income or loss arising from these transactions on the basis of the arm’s length provision in their tax returns and the exemption of such transactions from the preparation of transfer pricing documentation would substantially reduce the administrative burden faced by companies. The Hong Kong Government estimated that around 1,000 enterprises, representing less than 2% of the total number of profits tax-paying enterprises in Hong Kong, would be required to prepare the Master File and Local File. Notwithstanding, all businesses should immediately check whether they would exceed the threshold (including considering the accounting standards changes) and prepare the relevant transfer pricing documents to meet the new requirements. As the definition of the thresholds are not clear, if the company is close to the thresholds, the conservative approach is to assume that the thresholds have been breached. More important is to prepare the supporting documents such as contracts, because in order to analyse the transaction for transfer pricing purposes one has to refer to the contract to determine the nature of the transaction and analyse the functions and risks borne by the parties to the transaction. It may be too late to start preparing in 2019.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on January 24, 2018: https://manageyourtax.com/HKEJ Forum 3. As the Bill was passed in the Legislative Council on 4 July 2018 with amendments, this Tax Tips is updated to reflect the changes).
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on January 15, 2018: https://manageyourtax.com/HKEJ Forum 2).
The last issue of Tax Tips explained what constitutes “Base Erosion and Profit Shifting” (BEPS) and mentioned that one of the main objectives of the Inland Revenue (Amendment) (No. 6) Bill 2017 (the Bill) is to incorporate the BEPS Minimum Standard into the Inland Revenue Ordinance. The Inland Revenue Ordinance affects everyone in Hong Kong. What would be the impact on the Hong Kong people? One should first understand the concept and goal of the BEPS program.
The concept of the BEPS program is to establish a modern international tax framework that allows companies to pay tax at the location of their real business activities and value creation. The goal is to create a more equitable international tax system to combat BEPS. The BEPS program identified 15 Actions along three fundamental pillars: introducing coherence in the domestic rules that affect cross-border activities, reinforcing substance requirements in the existing international standards and improving transparency, as well as certainty for businesses that do not take aggressive positions.
A small sidetrack before we continue. The example of interest-bearing loans in the last issue of Tax Tips [see attached diagram] is, in fact, Case 1.1 of the BEPS Action 2, “Neutralising the Effects of Hybrid Mismatch Arrangements”. In Action 2, OECD proposed that country B should not allow interest deduction. If Country B allows the interest expense deduction, Country A should regard the income as taxable income in order to “ensure coherence of domestic laws and regulations on cross-border transactions”. In short, OECD is asking jurisdictions to amend the tax code. Logically, Country A and Country B themselves must determine their own tax treatment according to their laws and may be tax cases (where applicable). The laws, regulations and tax cases must have been formulated by history, circumstances and people’s empowerment of the respective countries. Large and small enterprises are only acting according to the laws and regulations. Going forward, would all jurisdictions determine their tax treatments based on how the other countries rule?
Since it is an international tax framework, in theory, all 15 BEPS Actions should be unanimously implemented globally. However, it is obviously a very difficult task. Each jurisdiction has its own tax laws and legal process in amending legislation, which could take years to complete. Even the G20 countries would unlikely be able to incorporate all Actions into their own laws in one go. In order to put the most important actions into practice, the G20 and the OECD set out four Actions that cover the above three pillars to be the Minimum Standards and require all countries to join the Inclusive Framework (thus declaring their commitment to implementing the Minimum Standard). Hong Kong joined the Inclusive Framework in 2016. At present, there are more than 110 countries or regions who have “joined the club”. The Minimum Standard covers:
Action 5: Countering Harmful Tax Practices More Effectively, Taking into Account Transparency and Substance Action 6: Preventing the Granting of Treaty Benefits in Inappropriate Circumstances Action 13: Guidance on Transfer Pricing Documentation and Country-by-Country Reporting Action 14: Making Dispute Resolution Mechanisms More Effective
Actually, implementation of Action 6 has already started. The OECD implemented Action 15 “Developing a Multilateral Instrument to Modify Bilateral Tax Treaties” and published last year the “Multilateral Convention to Implement Tax Treaty Related Measures to Prevent Base Erosion and Profit Shifting” (“Multilateral Convention”). As one of the purposes of the convention is to prevent abuse of preferential tax treaties, the amendment will make it harder for taxpayers to obtain treaty benefits. In June last year, Hong Kong signed the “Multilateral Convention” by representatives of Mainland’s State Administration of Taxation in order to amend the bilateral tax arrangements signed by Hong Kong and other countries or regions in one go. As of 20 December 2017, 72 countries or regions have signed the “Multilateral Convention”, and the OECD expects that as early as the beginning of 2018, as the parties to the convention completed their respective legislative formalities related to the “Multilateral Convention,” thousands of bilateral tax treaties would be amended swiftly and implement the measures against BEPS. According to the Consultation Report on Measures to Counter BEPS released by the Financial Services and Treasury Bureau in July last year, Hong Kong plans to submit the relevant amendment bill to the Legislative Council by mid-2018 for the implementation of the Multilateral Convention.
Tax Tips: The tax arrangement that Hong Kong people are most concerned about must be the Double Tax Arrangement (“DTA”) between Hong Kong and the Mainland. The Multilateral Convention signed by the Mainland on behalf of Hong Kong does not cover the DTA between Hong Kong and the Mainland. Does it mean that the DTA will not be amended? No. It is expected that Hong Kong and the Mainland will announce how to amend (tighten) the DTA, and Hong Kong will then carry out the legislative procedures to implement the Multilateral Convention. As for what changes are in store? Stay-tuned.
About five or six years ago, the international media reported more and more tax news. However, the news was not directly related to Hong Kong. At that time, the news mainly focused on a number of large U.S. companies such as Google, Facebook, Apple, Starbucks etc, which were exposed by the media in Europe for alleged malpractice in taxation or were brought to the courts by the Tax Departments. The main reason for these happening is that the governments were short of revenue after the financial crisis, so tax audits were conducted focusing on large foreign Multinational Corporations (“MNCs”). As a result, leaders of the Group of Twenty (G20) commissioned the Organization for Economic Co-operation and Development (OECD) to study how to combat the use of international corporate structures and transactions by MNCs in 2013 for tax avoidance. This is known as the “Base Erosion and Profit Shifting” (“BEPS”). OECD released 15 BEPS Action Plans in October 2015.
What is BEPS? Let us first talk about what is meant by “Base Erosion”: “Base” refers to “tax base”, which is the basis of which tax is calculated on. Using Profits Tax as an example, the assessable profit is the tax base. “Erosion” naturally means “to reduce”. How can taxable profit be eroded? MNCs take advantage of differences in tax rules of countries to create tax benefits over the same transaction (often involving complex planning). For example, in a transaction a person making payment could get a tax deduction, and the recipient in another country does not have to pay tax on the income according to the local tax regulations (typical example: Company A in Country A lends an interest-bearing loan to Company B in Country B. Company B is allowed to deduct interest expense, while Company A is not subject to tax on the income, which is characterised under Country A’s rules to be a tax-exempt return on investment [see diagram]). “Profit Shifting” is the use of intra-group transactions to legally transfer profits from a company located in a high-tax area to another company located in a low-tax area, as long as the relevant payment is supported by the transfer pricing report (there will be more discussion on transfer pricing in future articles), to reduce the Group’s overall tax burden. In summary, BEPS refers to the tax planning strategy of MNCs making use of differences and mismatches of tax rules across different countries and artificially transferring profits to low or no-tax jurisdictions with little or no economic activity.
One of the killers of the BEPS program of action is to require the headquarters of large MNCs to complete “Country-by-Country Reports” (to be further discussed in Tax Tips 3 and Tax Tips 20) to provide detailed global operational information to the tax office-in-charge of the Ultimate Parent of the MNC, which will then be automatically exchanged with tax offices in jurisdictions where the MNC operates. Readers who are familiar with company’s structure and international tax planning should be able to foresee what would be the consequences. Tax Tips: Do not think that the BEPS program of action is just a matter for large MNCs. The Hong Kong Government gazetted the Inland Revenue (Amendment) (No. 6) Bill 2017 (“the Bill”) on 29 December 2017. The main purpose of the Bill is to include transfer pricing principles in the Inland Revenue Ordinance and to implement the minimum standards proposed by the OECD for fighting the BEPS. The Bill, which is 162 pages long, is very complex and has a profound impact on Hong Kong’s tax system. The most important point is that Hong Kong taxpayers may need to prepare transfer pricing reports even if they do not have cross-border related party transactions. In the future, the compliance costs of taxpayers will be greatly increased.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 8 January 2018: https://manageyourtax.com/HKEJ Forum 1).
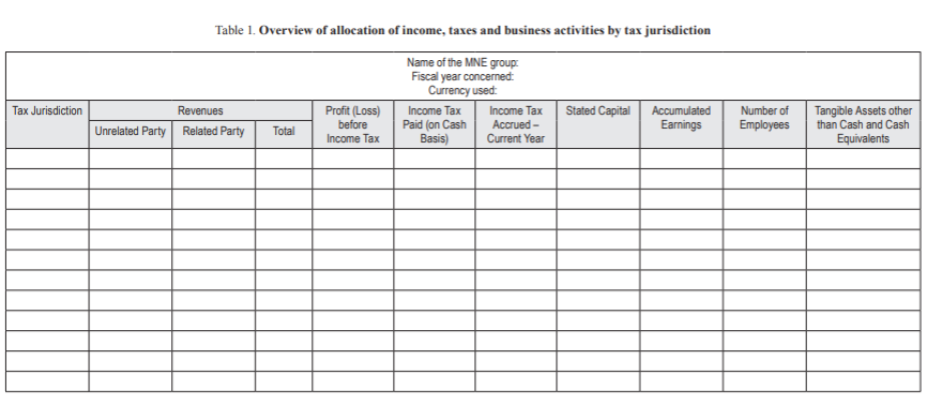
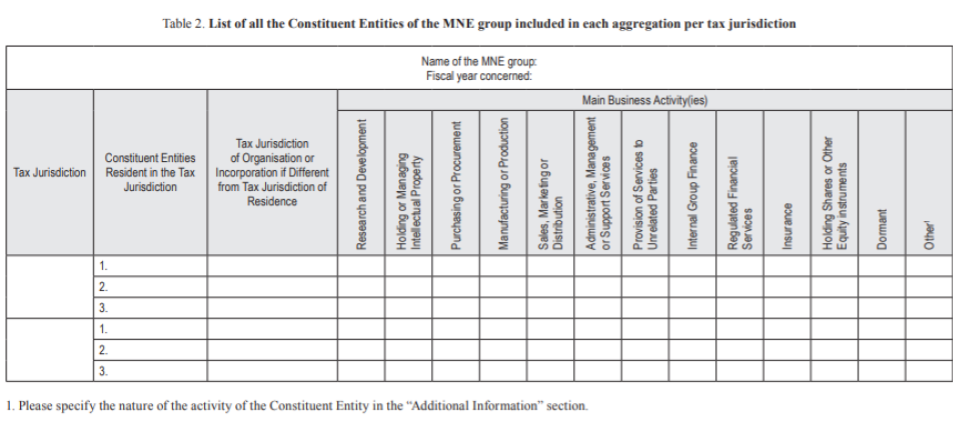
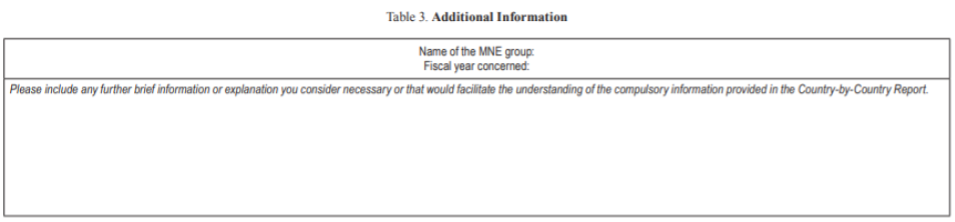
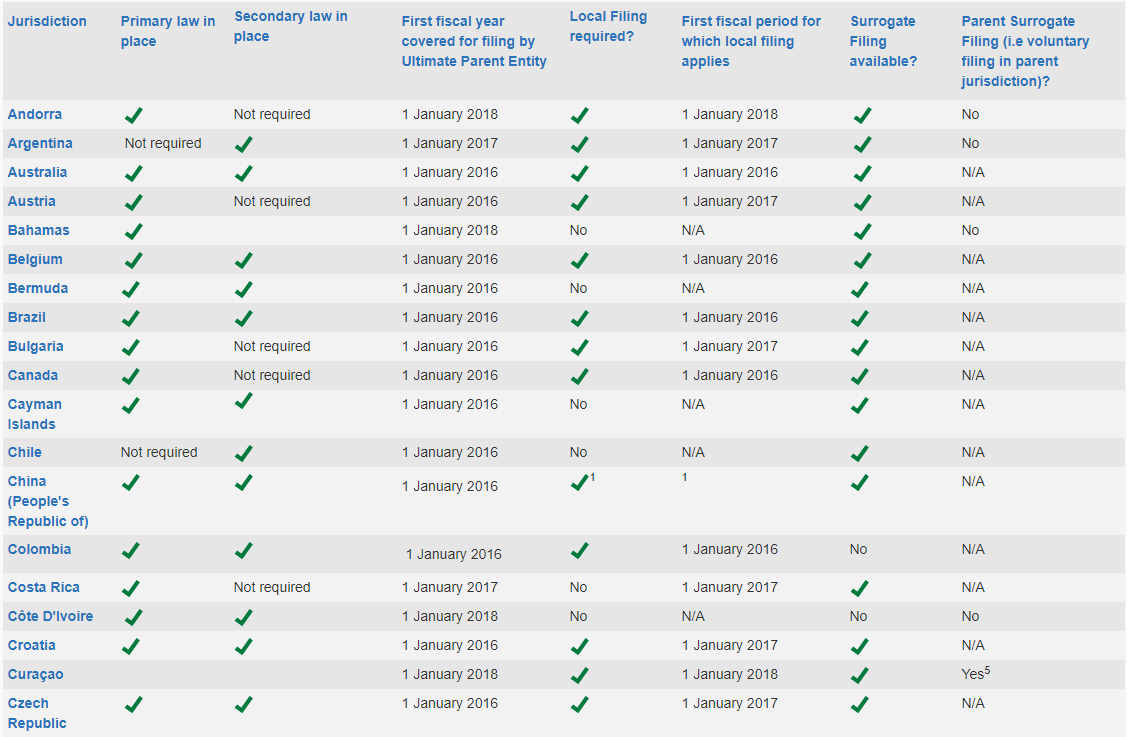
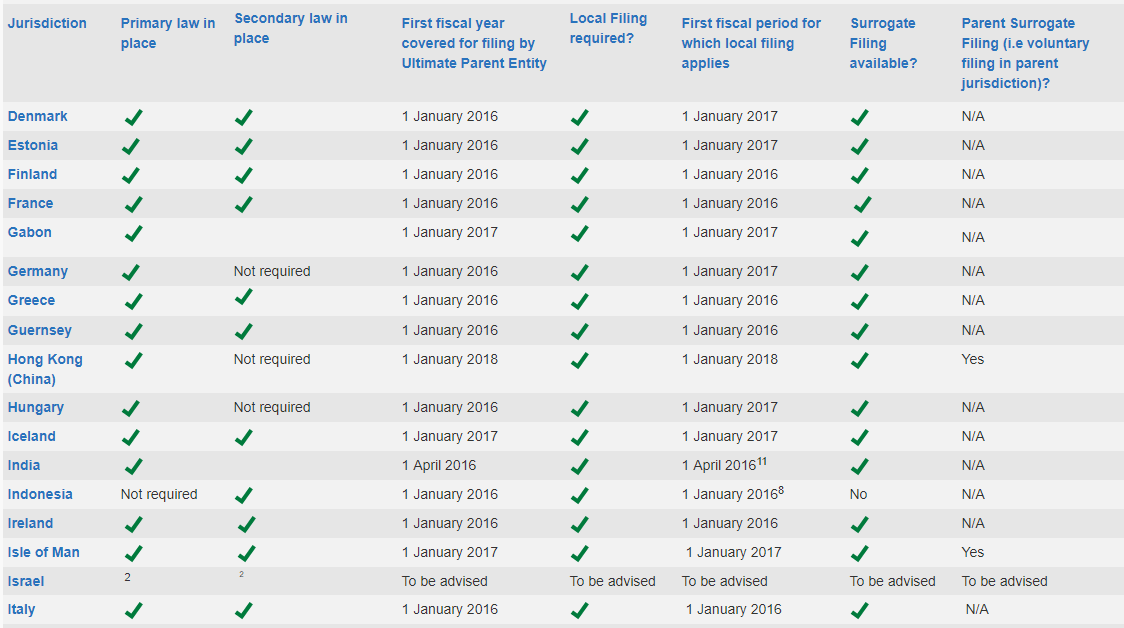
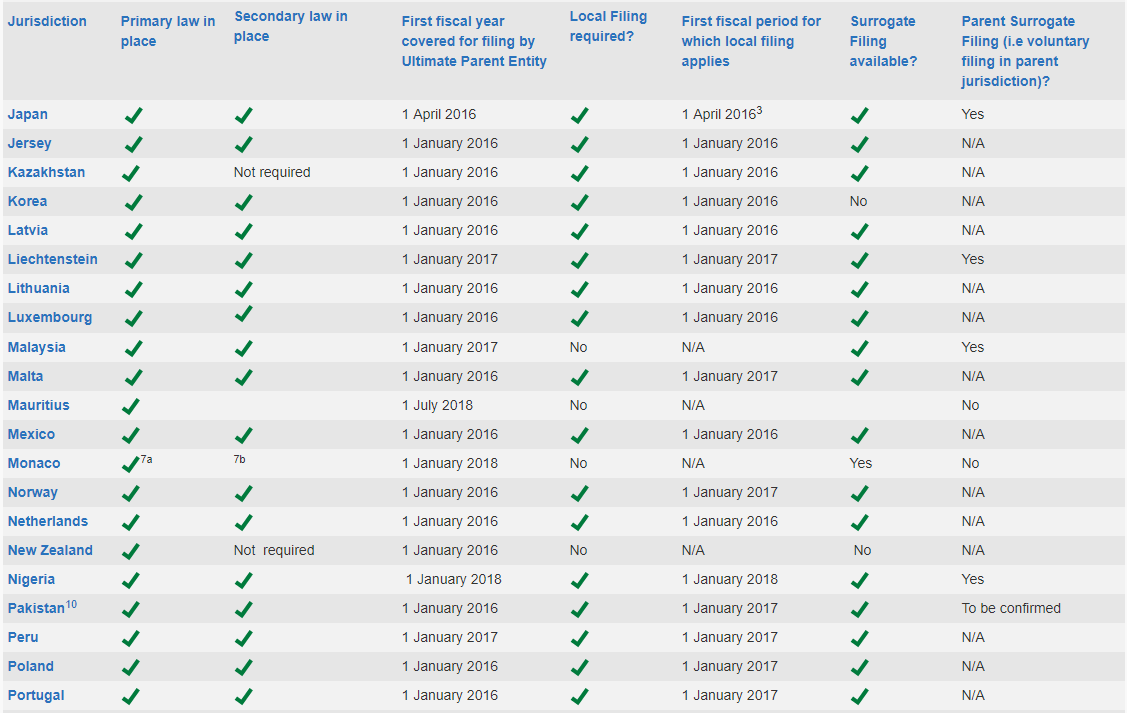
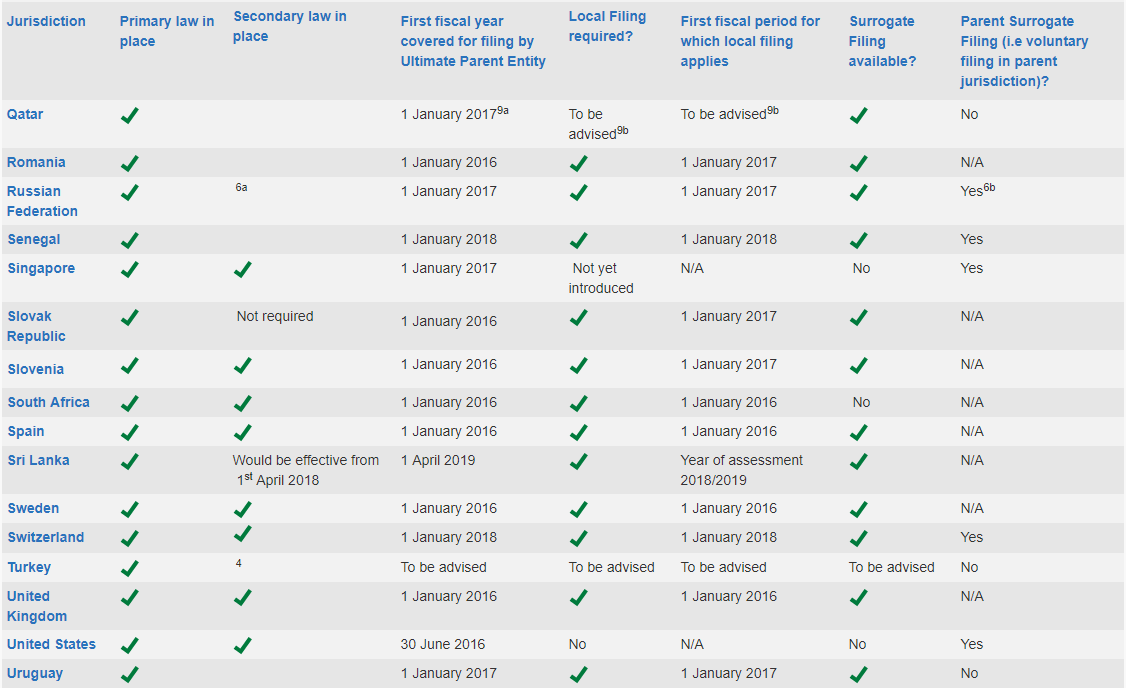 Anyone who had the experience of managing the CbCR filing for a reportable MNE Group for years 2016 and 2017 would know how much headache it is to ensure compliance.
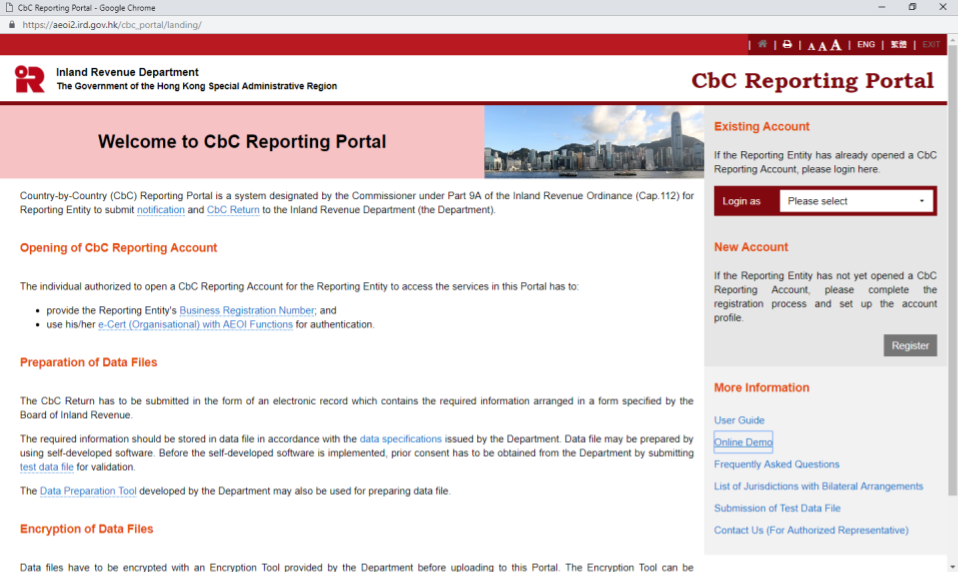
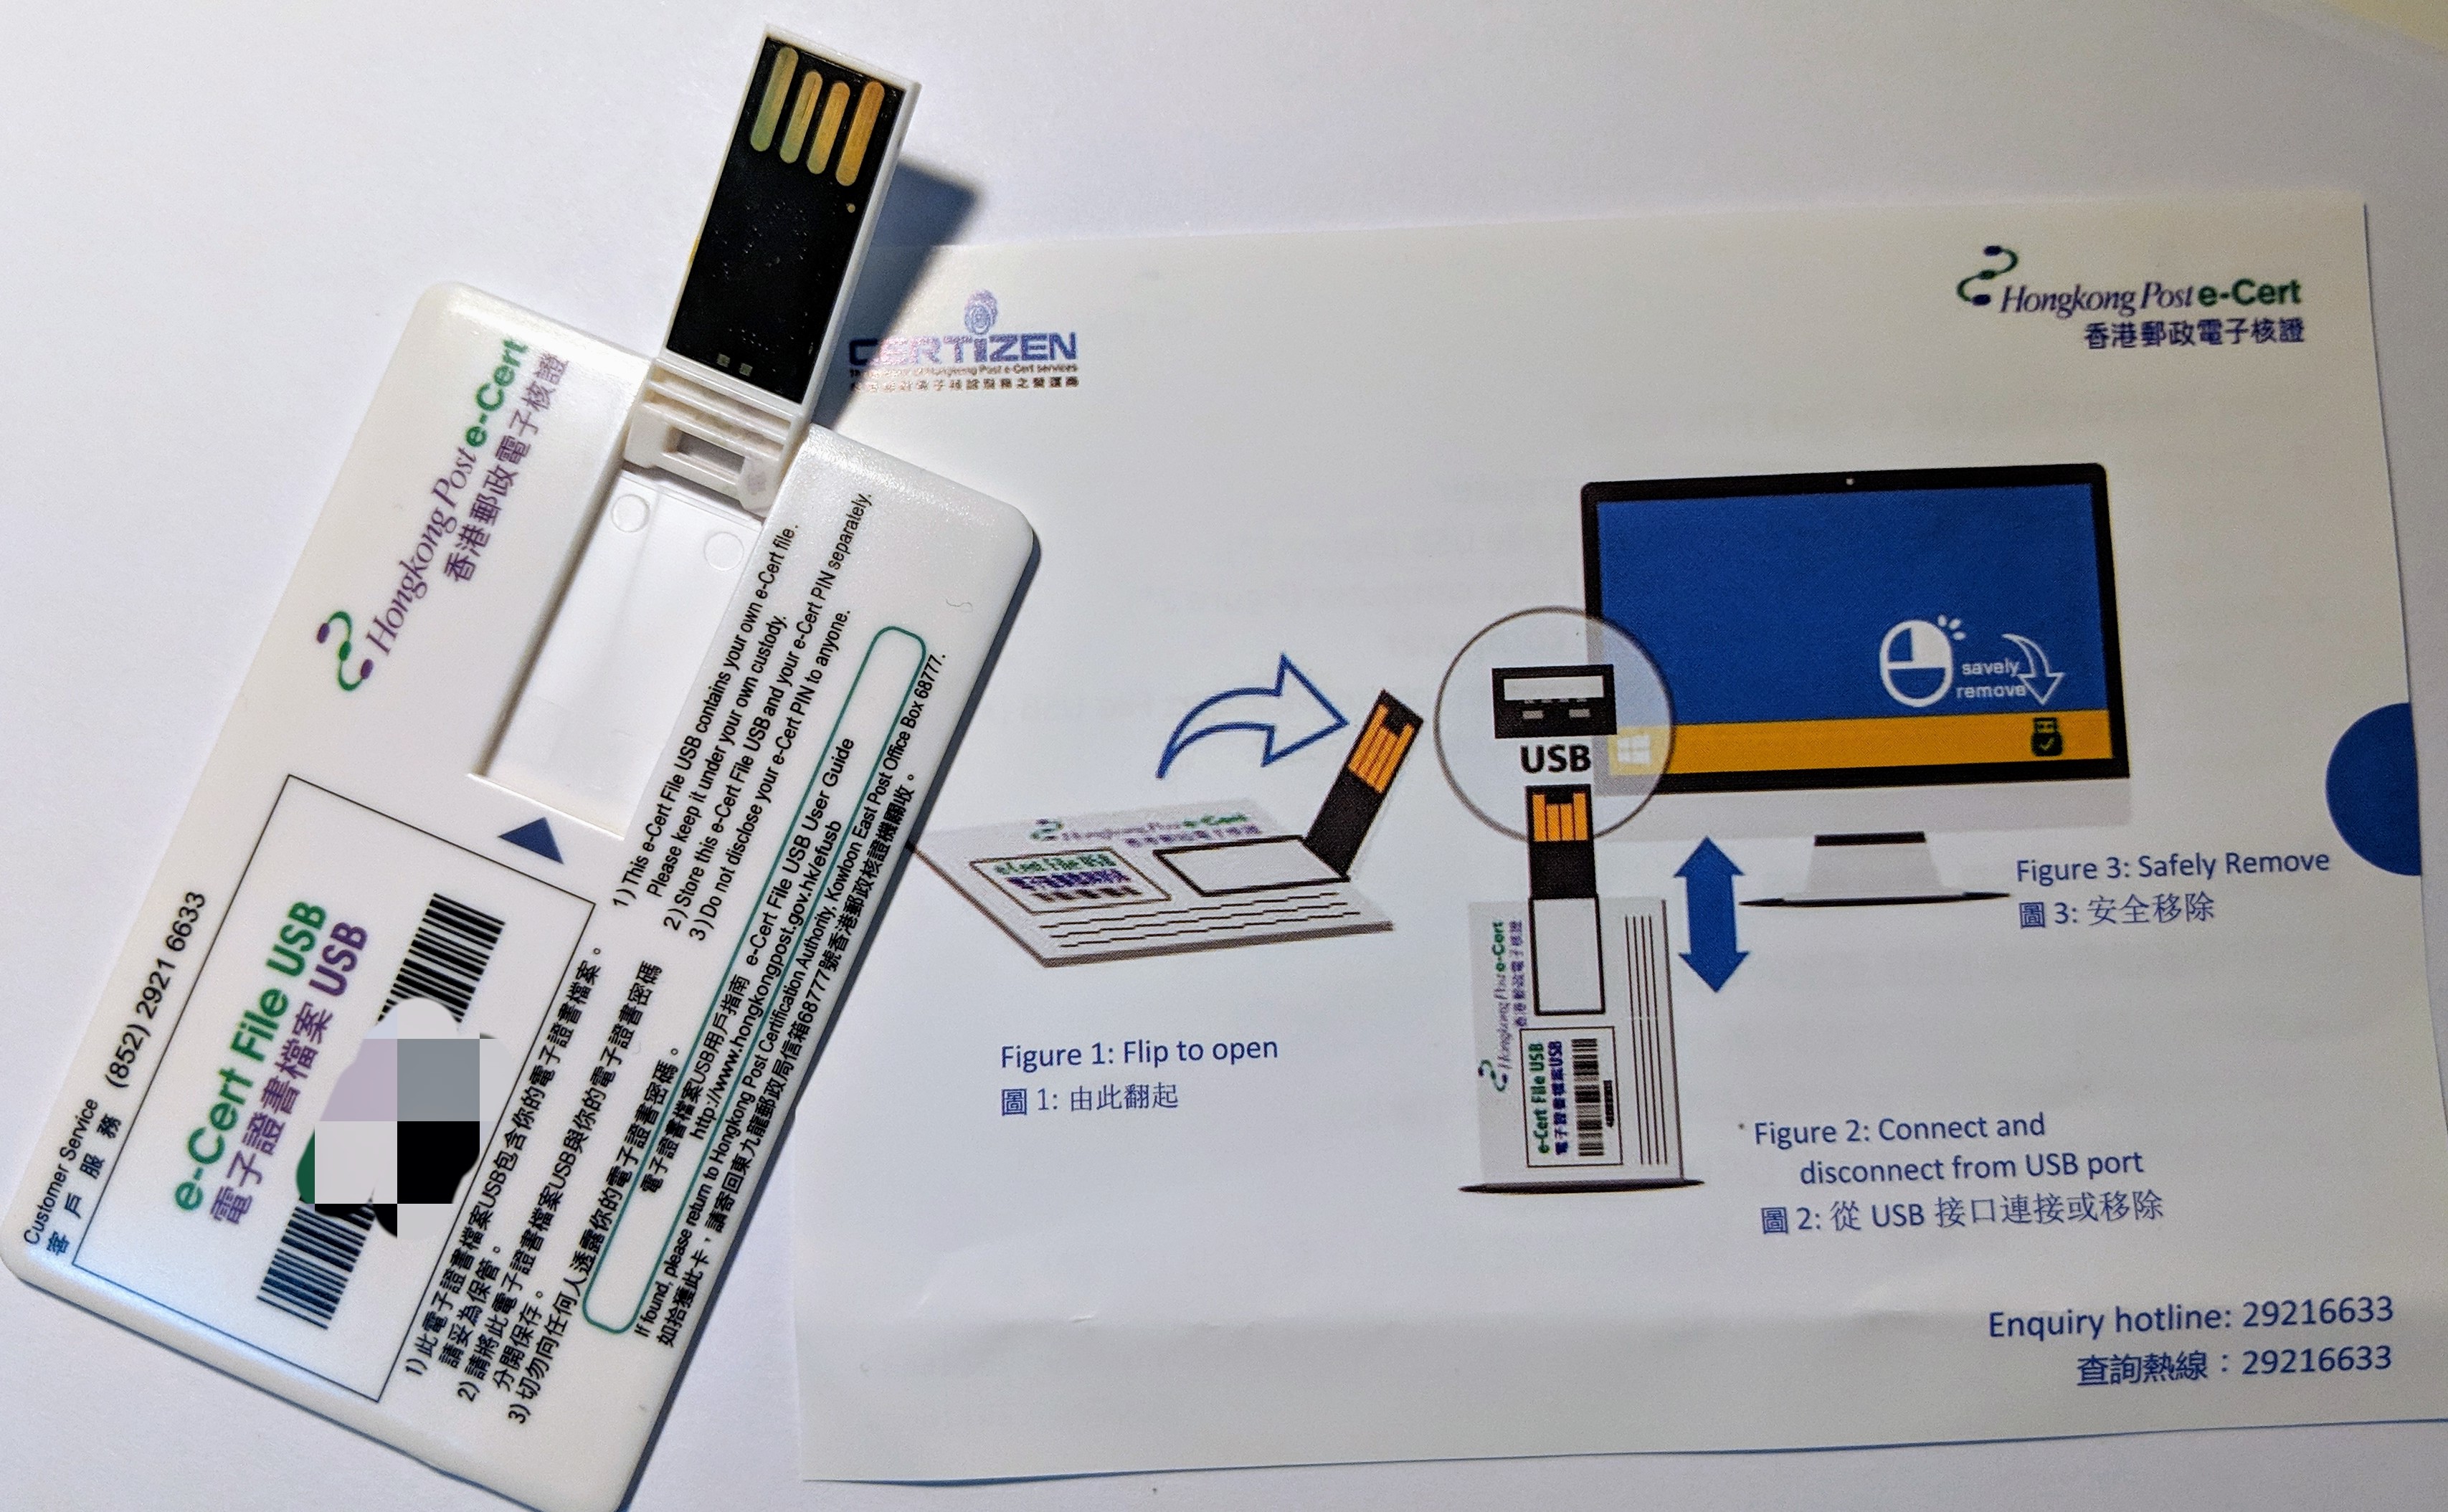
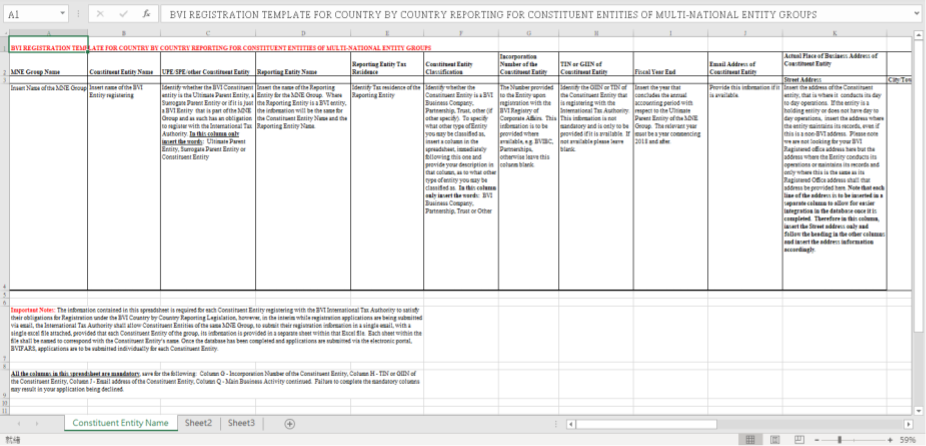
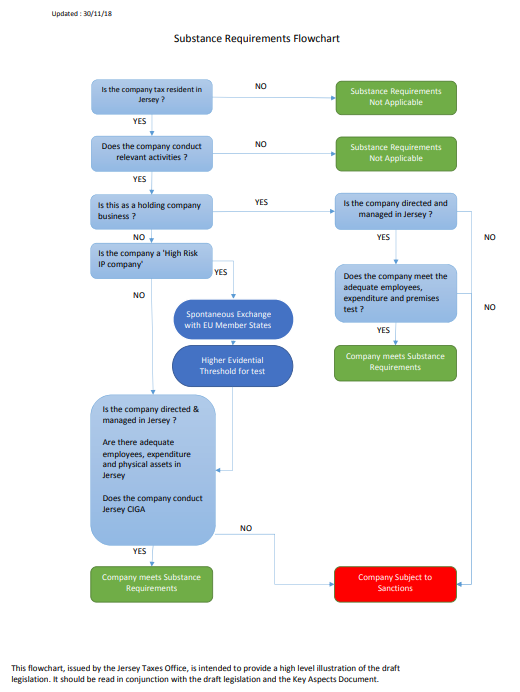
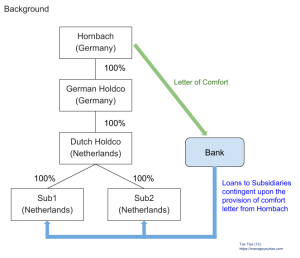
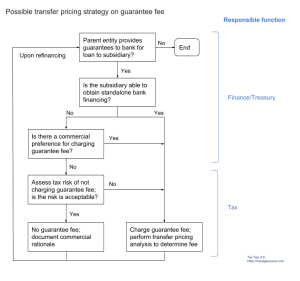
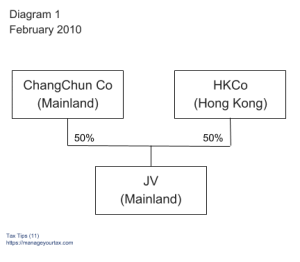
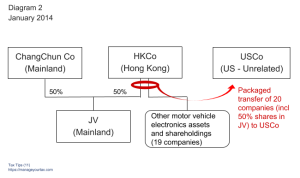
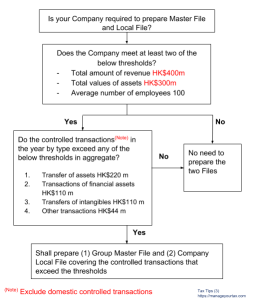
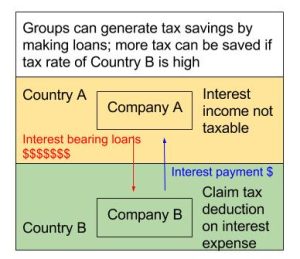 A small sidetrack before we continue. The example of interest-bearing loans in the last issue of Tax Tips [see attached diagram] is, in fact, Case 1.1 of the BEPS Action 2, “Neutralising the Effects of Hybrid Mismatch Arrangements”. In Action 2, OECD proposed that country B should not allow interest deduction. If Country B allows the interest expense deduction, Country A should regard the income as taxable income in order to “ensure coherence of domestic laws and regulations on cross-border transactions”. In short, OECD is asking jurisdictions to amend the tax code. Logically, Country A and Country B themselves must determine their own tax treatment according to their laws and may be tax cases (where applicable). The laws, regulations and tax cases must have been formulated by history, circumstances and people’s empowerment of the respective countries. Large and small enterprises are only acting according to the laws and regulations. Going forward, would all jurisdictions determine their tax treatments based on how the other countries rule?