A multilateral tax cooperation mechanism under the Belt and Road Initiative (BRI), the Belt and Road Initiative Tax Administration Mechanism (BRITACOM) which includes tax authorities from 34 countries and regions, was established on 18 April 2019. The reported aim of BRITACOM is to facilitate cross-border trade and investment along BRI routes by expanding tax dispute resolution activities, increasing transparency, streamlining compliance and digitizing filing. An office will be opened in Beijing to help facilitate these goals.
Since the BRI consists primarily of Chinese outbound investment in infrastructure projects in the participating countries, BRITACOM will likely function more in facilitating outbound Mainland Chinese entities’ local tax compliance and dispute resolution when engaged in such projects. BRITACOM will be different from the various anti-tax avoidance initiatives of the OECD and other international organisations.
International Effort in Anti-Tax Avoidance
The most well-known international effort against tax avoidance is the Base Erosion and Profit Shifting (BEPS) project. The 15 BEPS Actions issued in October 2015 challenge tax avoidance practices by large Multinational Enterprises (“L-MNEs”) by amending the global tax treaties, increasing disclosure and transparency, introducing new documentation in transfer pricing, countering harmful tax practices, lowering threshold of permanent establishment recognition, investigating into new form of taxation for digital services and toughening interest deduction rules. The primary aim of BEPS is to ensure that the international tax rules do not facilitate the shifting of corporate profits away from the real economic activity and value creation are taking place. Many of these Actions have been implemented already, the latest being the Economic Substance Law (with the BVI just issued the Draft Economic Substance Code).
In addition, the OECD has stepped up efforts in international cooperation on tax matters in recent years. Heads of tax administrations meet regularly at the Forum of Tax Administration (FTA). Cross-border tax avoidance intelligence is shared among tax offices under the Joint International Taskforce on Shared Intelligence and Collaboration (JITSIC). The International Compliance Assurance Programme (ICAP) invites large MNEs to engage voluntarily with tax administrations from 17 jurisdictions (expanded from 8 when the pilot began in January 2018). Tax Inspectors Without Borders sends experience tax officials to train those in developing countries to perform tax audits on MNEs.
The United Nation, the World Bank, the International Monetary Fund, and the European Unions are also very active in introducing new initiatives in combating tax avoidance.
Large MNEs have Acted
Many L-MNEs have already started restructuring back in around 2013/14 in view of the disclosure requirements especially the Country-by-Country Reporting (CbCR). In the past, many L-MNEs housed the intellectual properties (“IP”) in tax haven jurisdictions earning untaxed royalties or have captive insurance companies there to provide insurance coverage to group companies in order to receive untaxed income while the group companies could take a tax deduction. Smart L-MNEs would have restructured early so that no tax office would have the opportunity to ask the sensitive questions. Their most immediate challenge to the L-MNEs would likely be dealing with the economic substance law in the tax haven countries, especially those that have been acting as funding vehicles.
Smaller MNEs – Act Now
L-MNEs have internal tax resources to help them manage tax risks in this rapidly changing tax environment. What about the Small and Medium Size MNEs (S-MNEs) that do not have in-house tax people? They obviously have to rely on external tax consultants. The key is to identify the right consultants to do the following two things:
1. Review the existing structure, operations and arrangements
The objective of such review is to identify tax risks and opportunities currently embedded in the group structure and operations. The author had seen a group missing out the 50/50 offshore claim in the Hong Kong profits tax filing on a contract manufacturing arrangement. In another case, a Hong Kong-based listed group devoted resources in Hong Kong to help the overseas affiliates in high tax countries to become highly profitable but they do not realise that they should recoup the costs incurred in Hong Kong via transfer pricing in order to align with the commercial reality and reduce the group’s effective tax rate. These can be dug out and properly addressed in order to create legitimate tax saving.
Some groups have not paid attention to documentation of decision making and thereby creating risks of being regarded as tax resident in jurisdictions unexpectedly. The old model of cost-plus remuneration of agents may now be exposed to permanent establishment risks. Some have ignored the documentation of substance. The impact of the Economic Substance Law introduced by the tax havens such as the British Virgin Islands (BVI) must be properly analysed with a set of action determined to address the issue.
To be a good manager, issues should be addressed and resolved upfront so that the expectation of shareholders and directors of the group/company is well-managed. The review should be conducted by professionals with solid technical and business experience. There are well-qualified tax advisors in the market to do the work at competitive rates and high efficiency to deliver substantial value to the groups.
Often the finance managers of the groups/companies prefer to stick their heads into the sand instead of dealing with the problems because they don’t want to take the blame for issues uncovered by the seasoned tax advisors. It is thus important for the directors or even the shareholders to realise what the current tax environment is like and take initiative in carrying out the review. At the end of the day, if the hidden tax exposures are not cleared before they crystalise, the group/company, the directors and shareholders would be badly hurt.
2. Seek on-going tax support especially on documentation
Having identified and dealt with past issues, it is important that no such issue will arise again in the future. This can be achieved by retaining the tax advisor to review transactions or documentation as and when required, just a family doctor caring for the health of the family. For example, sometimes the auditors, being unaware of the tax exposure created, may make disclosures in the audited financial statements that are unnecessary and sometimes even harmful to the tax arrangement of the company. For listed companies, they should be very careful in the disclosures in the annual reports.
Board papers are crucial. It is direct evidence of management and control which is one of the key factors in determining substance and tax residency. Tax advisors play an important role in advising who should be on the board of each company, location of board meetings and review the board papers.
Also, management should be made aware of tax law changes and new cases that affect their business. Questions they should ask, or proactively addressed by the tax advisor, include:
What are the benefits of the new tax incentives introduced in Hong Kong such as the two-tier tax system to the group?
Should something be done about intellectual property in view of the new Section 15F of the Inland Revenue Ordinance?
What should the group do in view of the Beneficial Ownership rules in Mainland China to ensure that the benefits can be obtained?
It is time for the smaller groups to gear up the tax risk monitoring and compliance, and ensure that structures are sustainable in the medium term. The BEPS Project is at the implementation stage and it will not be long before OECD reviews the achievement and point to the next target: the S-MNE groups. The time to act is NOW.
If you work in a Hong Kong subsidiary of a large Multinational Enterprise (MNE) Group and you think Country-by-Country Reporting (CbCR) has nothing to do with you, think again.
Your employer could be facing a penalty of HK$50,000 (US$6,400) on each Hong Kong entity for failing to file CbCR notification with the Hong Kong Inland Revenue Department (“IRD”), the first deadline falls on 31 March 2019 (the IRD announced on 21 March 2019 that the notification deadline for qualifying entities is extended by 45 days to 15 May 2019). Failing to file the CbCR will also attract the same level of penalties. In addition, you may be under a statutory obligation to keep the underlying records of the CbCR, which includes detailed information of the global operations of the Group, for 6 years or you may once again get hit with the HK$50,000 penalty. What is more, the Hong Kong CbCR Rules could impact your Group’s relationship with business partners and potential investors.
The CbCR rules are contained in Part 9A Division 3 of the Inland Revenue Ordinance (“IRO”) introduced under Inland Revenue (Amendment) (No 6) Ordinance 2018, which also included the other transfer pricing documentation requirements, namely the master file and local file. This Tax Tips focuses on the CbCR, which many in the community are not aware of the statutory requirements, the additional hurdles introduced for compliance, the practical issues of preparing the CbCR, and the importance of project management. The Hong Kong CbCR rules are, unfortunately, very tough.
Worried? Read on.
The Basics about CbCR
The CbCR was introduced under the Final Report on Action 13 of the OECD Base Erosion and Profit Shifting (“BEPS”) Project (“Action 13”) as a tool for high-level transfer pricing risk assessment. It may be used by tax administrations in evaluating other BEPS related risks and where appropriate for economic and statistical analysis.
Action 13 – Who needs to prepare CbCR and where to file
Normally it should be relatively easy to determine if an entity is required to file a tax return or not. Not the case for CbCR. The general rule under Action 13 is that if an MNE Group’s annual consolidated group revenue in the immediately preceding fiscal year (for example, for the year ended 31 December 2017) exceeds EUR750 million, then Ultimate Parent Entity (“UPE”) of the group will need to prepare CbCR for the following year (the year ended 31 December 2018 in the example), and file it with the UPE’s tax office which is due within 12 months after the year-end date (31 December 2019 in the example).
The CbCR submitted will then be automatically exchanged with other jurisdictions (based on an international agreement – the Multilateral Competent Authority Agreement on the Exchange of CbC Reports (the “CbC MCAA”)) that the MNE Group operates in (as indicated on the CbCR) so that there is no need for the UPE to file the report multiple times in different tax jurisdictions. However, there are a variety of situations for CbCR exchanges. The United States, for example, did not sign the document but instead arrange bilateral exchange agreements with other jurisdictions. Some jurisdictions, such as the Cayman Islands and Bermuda, are only doing one-way exchange: sending the CbCR collected to other jurisdictions but is not accepting CbCR (likely because there is no tax there).
The CbCR
The CbCR consists of three tables. Table One requires aggregate tax jurisdiction-wide information relating to the global allocation of the income, the taxes paid, and certain indicators of the location of economic activity among tax jurisdictions in which the MNE Group operates. Below is Table One.
Table 1
Table Two requires a listing of all the Constituent Entities (“CE”) of the MNE Group for which financial information is reported, including the tax jurisdiction of incorporation, where different from tax jurisdiction of residence, as well as the nature of the main business activities carried out by that CE.
Table 2
MNE Groups may use Table Three to provide additional information or explanation that is considered necessary or that would facilitate the understanding of the compulsory information provided in Table One and Two.
Table 3
Simple in Design, Difficult to Comply
After Action 13 was published in 2015, tax jurisdictions around the world have to pass the filing requirements into the local laws before CbCR can be collected. Naturally, some tax jurisdictions (mostly OECD countries) managed to swiftly implement the rules (the first year of filing would be for the year 2016, meaning the financial year that began within the calendar year 2016) but many were late. Hong Kong passed the law in July 2018 and the first year of filing is for the year 2018.
What would happen if the jurisdiction where the UPE is located has not introduced the CbCR laws but in some jurisdictions that the MNE Group operates the CbCR laws have been implemented?
This is where the “fun” is.
Local Filing, Parent Surrogate Filing, Surrogate Parent Filing
The MNE Group has to find out at each location that it operates, what is the status of CbCR implementation, and whether there is a “Local Filing” requirement. Local Filing, in simple terms, refers to the filing requirement imposed on the CE located in the tax jurisdiction to file the Group CbCR when the tax office is not able to obtain the CbCR from the UPE’s tax jurisdiction. In some jurisdictions, Local Filing is needed only upon request (for example, during a tax investigation).
If the UPE is required to file CbCR, it will need to check all the locations where the group operates whether the tax jurisdiction of the local CE is able to obtain the CbCR via an exchange mechanism with the UPE’s tax jurisdiction. If not, the local CE needs to perform Local Filing. In which case, the UPE needs to provide the CbCR to the local CE for filing. Multiple Local Filings may be needed.
If the UPE is not required to file CbCR, the Group is more likely to face multiple filings in different jurisdictions. To help reduce the compliance burden, Action 13 introduced two solutions: Parent Surrogate Filing and Surrogate Parent Filing (there is no typo here, these are two different terms), but it is up to each tax jurisdiction to determine if they allow such filing.
Parent Surrogate Filing refers to a voluntary CbCR filing by the UPE at the UPE’s tax jurisdiction before statutory filing is introduced into law. The tax office will exchange the CbCR obtained with other jurisdictions via automatic exchange or bilateral agreement. Hong Kong is a jurisdiction that accepted Parent Surrogate Filing for years 2016 and 2017 but it is unlikely that this offer has ever been taken up as the exchange network was very limited (thus incapable to avoid multiple Local Filing in other jurisdictions).
Surrogate Parent Filing allows the UPE to appoint a CE in another jurisdiction to be the parent entity for CbCR purposes and file the group’s CbCR with that other jurisdiction as if the CE is the UPE of the Group. This is a more popular solution for avoiding multiple Local Filing because the group can choose a CE in a jurisdiction with the widest automatic-exchange network (for example, the United Kingdom) as the Surrogate Parent Entity (“SPE”). Many Hong Kong groups selected this filing method for the years 2016 and 2017.
The OECD has been keeping track of the CbCR implementation status of different jurisdictions as well as their acceptance of Parent Surrogate and Surrogate Parent Filing. Below is the status as at 10 January 2019 extracted from the OECD website:
Anyone who had the experience of managing the CbCR filing for a reportable MNE Group for years 2016 and 2017 would know how much headache it is to ensure compliance.
Are You Ready for Preparing the CbCR Correctly?
Test your knowledge by answering the following true or false statements:
TRUE or FALSE:
CEs refer to entities that the UPE owns 50% or more.
Representative Offices or Branches with separate accounts are themselves CEs.
“Revenue” includes capital gains.
Related parties transactions can be eliminated for reporting.
Income tax paid does not include foreign taxes.
A CE that left the group during the year (e.g. disposed of) can be excluded from the CbCR for that year.
The number of employees includes independent contractors.
The Tax Identification Numbers (taxpayer file number) and addresses of CEs are not required for CbCR filing.
Answers are at the end of this article.
The OECD Action 13, the Guidance on the Implementation of CbCR (the “CbCR Guidelines”, issued by the OECD and last updated in September 2018) and the CbCR: Handbook on Effective Implementation (the “CbCR Handbook” issued by the OECD in 2017) provide some guidance on the definition of various terms and how to deal with different situations. However, it is far from comprehensive. Groups need to decide in situations specific to them the position to take in the CbCR and ensure that all CEs take the same position. It is thus important that the MNE Group studies the OECD documents and guidance issued by tax offices and prepare a set of CbCR Instructions for internal use to align the basis of preparation.
For larger groups, especially those with different business lines and frequent M&A activities, a set of Frequently Asked Questions would be helpful as the first point of contact when the people in different jurisdictions involved in the data input face questions, as some of them may raise the same questions. Where applicable, part of the CbCR Instructions and FAQ can be disclosed in Table 3 of the CbCR. For example, the Instructions and FAQ may cover items such as:
How to report newly set-up CEs that have not closed their books as at the year-end date of the UPE
Source of data
Which entities are “related entities” for CbCR purposes
How to account for withholding taxes paid if the tax is calculated on a gross-up basis
How to report the tax paid in the case of a tax grouping
How to check the “main business activity(ies)” boxes for the different businesses of the group
Who is to determine if a CE is dormant
Approach to prepare the CbCR – Top-Down or Bottom-Up?
Obviously, if the group prepares the CbCR centrally at one location (say at the headquarters) based on financial data on CEs around the world that it possesses, it can achieve the best level of consistency. This Top-Down approach can avoid worldwide training for data input. However, the central location will inevitably need to obtain information from local CEs, and they may provide incorrect information if they do not understand CbCR. In addition, when the CbCR submitted is exchanged to the jurisdictions of the local CEs, the local CEs may be approached by the local tax office for explanations on the data. In such a situation, the headquarters will need to answer the questions from afar. The situation will become unmanageable if many tax offices ask questions at the same time.
Automation or manual input?
Another question that all MNE Groups would go through is: how to avoid the manual data collection process? There is no right or wrong answer to that and it is more a cost-benefit analysis. There are two important factors to consider: (i) whether the same accounting system is adopted across the group and (ii) whether the adjustments required (for example, identifying the related party transactions with CEs) can be dealt with by the system. Further, if the Group makes acquisitions, which often happen in the corporate world, substantial efforts may be required to change the legacy accounting system of the newly acquired entities. In real life, several different accounting systems may be deployed within an MNE Group.
How to manage the CbCR preparation
If an MNE Group is required to prepare CbCR and the bottom-up, manual input approach is adopted, the steps would include the following:
Assign a Project Manager – a person who is knowledgeable about CbCR or has access to technical resources;
Manage notifications across the group;
Compile the list of CE for the reporting year and determine the tax jurisdiction of each entity including the tax haven entities;
Assign a staff person from the finance or accounts department to each CE as the first level data input;
Assign a “CbCR Champion” to each group of entities which can be based on jurisdiction and/or business lines. The CbCR Champions would need to ensure consistency in the data compilation and address questions, and review data input by staff. More difficult questions can be forwarded to the Project Manager for resolution;
Prepare a detailed Instructions and FAQ and everyone involved in the process should study them before commencing work;
Training for all involved in the process, timeline and the position taken on different aspects;
Prepare an Excel format data input worksheet for data input;
Staff perform data input and submit to CbCR champion for review with supporting documents (financial statements etc);
Final review by the Project Manager and combine all input to prepare tables;
Sign off by senior management;
Convert the file into XML format (as requested by the tax office);
Submission.
The above is not rocket science. However, each step requires careful planning and execution in order to meet the filing deadline. Needless to say, the more CEs spreading across different jurisdictions, the more difficult it will be to manage the process and the risk of error will increase. Training and project management will become most important.
In addition, although MNE Groups are given 12 months to prepare the CbCR, when they can actually commence data input depends on how long it takes post-year-end to finalise the local financial statements. The longer it takes to finalise the accounts, the less time there is to prepare for the CbCR. Realistically, the time available would likely be less than 9 months.
The Hong Kong Rules are Making Life Even Harder
The Hong Kong rules on CbCR fully incorporated the Action 13, CbCR Guidelines and CbCR Handbook. As long as MNE Groups follow these documents and adequately disclose some of the position taken, there should be relatively little concern of incorrect filing. However, on the administration side, MNE Groups with CEs in Hong Kong must pay special attention to the Hong Kong rules.
Notification – Section 58H
Section 58H under Division 3, Part 9A of the IRO sets out the requirement for notification: each Hong Kong CE of a reportable group must file a notification informing the IRD, effectively, which entity in Hong Kong will file the CbC Return* or, if the CbC Report* is to be filed in another jurisdiction, various information about such filing. One Hong Kong entity of the MNE Group can represent other group entities to file the notification. Notification deadline is within 3 months after the end of the year-end of the MNE Group.
* This article used the term “CbCR” in a broad sense to describe both the CbC Report (the three tables) that is filed with the tax office and the act of preparing the CbC Report. The Hong Kong rules distinguish between the “CbC Return” and the “CbC Report”. The CbC Report is the report containing the three tables discussed above. Under Section 58K(1), the CbC Return is the CbC Report and “any other information specified by the Board of Inland Revenue”.
In many jurisdictions (for example, the UK, Malaysia and South Korea), notification can be done by writing a letter or filling in a prescribed form. In Hong Kong, one needs to file notification via the CbC Reporting Portal (“Portal”). The Portal is developed by the IRD to facilitate the Hong Kong entities to:
submit notifications of obligations to file CbC Returns;
submit notifications of change of address;
file CbC Returns; and
receive or send messages in relation to CbC reporting.
IRD CbC Portal
Just like any online system, a registration procedure is required to access the Portal. A Hong Kong Entity should register a CbC Reporting Account under the Portal. The person authorized to register a CbC Reporting Account for the entity has to possess an e-Cert (Organisational) with AEOI Functions (“e-Cert”) for authentication purposes. The person has to apply for the e-Cert at the Hong Kong Post.
Manage Your Tax’s e-Cert (Organisation) with AEOI function
Filing – Section 58E and 58F
The deadline for the filing of a CbC Return is within 12 months after the end of the accounting period, which obviously shall be filed via the Portal. Similar to most jurisdictions, a CbC Report must be made in the form of an XML document for submission to the IRD. The reason for this is that XML documents can be validated and provide a common medium for exchange between the jurisdictions that have introduced CbCR requirements. In this regard, the IRD has developed a data schema in XML which is based on the CbC XML Schema v1.0.1 issued by the OECD. The data schema specifies the data structure and format for filing CbC Report to the IRD. The current version of the data schema and related user guide is available on the IRD website for download.
It is important to note that other than the information required in Table 1, 2 and 3 of the CbC Report, the XML Schema User Guide issued by the Hong Kong IRD mandatorily requires that the Tax Identification Number (“TIN”) of each CE, where issued by the tax administration of the tax jurisdiction of the CE, be provided. If the CE does not have a TIN, the value “NOTIN” shall be entered. In addition, the XML Schema User Guide “strongly recommended” that the address of each CE shall be provided. Finally, if the CE is a Permanent Establishment, the name of the CE should be followed by “(P.E.)”.
To the unwary, these additional information and formatting requirements may create an issue if only discovered upon XML conversion, potentially causing late filing.
Automatic Exchange of the CbCR
After filing the CbCR with the IRD as the UPE or SPE, can the MNE Group rely on the IRD to send the CbCR out to other tax jurisdictions such that the filing obligations there would be satisfied? It depends. Although Hong Kong has signed the CbC MCAA, the automatic exchange with applies for accounting period starting on or after 1 January 2019. Therefore, for a Hong Kong UPE or SPE who is filing a CbCR with the IRD for the accounting period for the year ended 31 December 2018, the IRD would only exchange it with the following 11 jurisdictions (as at 31 January 2019) based on bilateral exchange arrangement in place:
France
Guernsey
Ireland
Japan
Jersey
Korea
Malta
Netherlands
New Zealand
South Africa
United Kingdom
If the Hong Kong UPE has CEs in a jurisdiction not listed above which requires Local Filing (e.g. Germany), the Germany CEs may need to file the CbCR locally. If the Hong Kong UPE is also considered a resident in another jurisdiction and that jurisdiction has an exchange agreement with Germany, then it may file in a second CbCR with that jurisdiction to cover the German filing and elsewhere.
Record keeping – Section 58L
Section 58L requires that a Reporting Entity must (a) keep sufficient records to enable the accuracy and completeness of the CbC Return filed under this Division (i.e. Division 3, Part 9A of the IRO) to be readily ascertained; and (b) retain the records for a period of 6 years beginning on the date on which the return is filed. The burden on the Reporting Entity is indeed substantial and thus it is important to know which entity is the Reporting Entity.
Under Section 58J, a Reporting Entity includes (a) a Hong Kong UPE required to file a CbC Return (Section 58E(1)), (b) a Hong Kong entity that is required to file a CbC Return by Section 58F (i.e. either under Local Filing or the entity is appointed the SPE), and (c) a Hong Kong entity that is required to provide a notice by Section 58H.
If a Hong Kong UPE or SPE is required to file the CbC Return it is fair to expect that entity to possess information that satisfies Section 58L. It is debatable whether it is fair to demand the same level of record keeping for an entity that performs Local Filing. It is, however, unreasonable and unnecessary to impose statutory obligations for the entity that files only a notification under Section 58H to maintain sufficient records for 6 years to enable the accuracy and completeness of the Group’s CbC Return be ascertained.
To illustrate, assume a Korean conglomerate engaged in shipbuilding, mobile phone manufacturing, financial services and health care is filing the CbCR in Korea, and only the mobile phone division has subsidiaries in Hong Kong and are required to file CbCR notification to the IRD. The Hong Kong subsidiaries will need to maintain the CbCR information of the entire global group to the extent required under Section 58L. The IRD should not impose such record-keeping requirement on the Hong Kong subsidiary. If the IRD requires information, they should approach the Korean tax office to collect it. Hong Kong subsidiaries of foreign MNE groups are now faced with this unreasonable statutory requirement.
Penalties – Section 80G
Division 6 of Part 9A contains the penalty provisions for CbCR. The new Section 80G provides that a Reporting Entity commits an offence if the entity, without reasonable excuse: (a) fails to file the CbC Return (Section 58E(1) or 58F); (b) fails to file notification under Section 58H; or (c) fails to keep records as required under Section 58L. That Reporting Entity would be liable on conviction to a fine at level 5 (HK$50,000/US$6,400), and the court may order the entity to do, within the time specified in the order, the act that the entity has failed to do. The Reporting Entity is liable to a further fine of HK$500 for every day or part of a day during which the failure to file the CbC Return or notification continues after conviction.
Obviously, there are further penalty provisions for more serious offences.
The penalty provisions are quite harsh especially on MNE Groups filing CbCR outside of Hong Kong. Their Hong Kong operations may be small and with little internal tax support. If the Hong Kong CE, being a Reportable Entity, is not wholly owned by the UPE (i.e. there is a minority shareholder), for information protection reason the MNE Group may not want to provide the detailed records to the CE as required under Section 58L. Is such information protection a “reasonable excuse” for not fulfilling Section 58L? If not, the minority shareholder may demand compensation from the MNE Group for any penalties suffered.
Service Providers
A service provider may be engaged to perform the filing and notification. However, the Reporting Entity’s obligations are not relieved. In addition, the service provider is also subject to the same level of penalties as the Reporting Entity for failure to file the CbC Return or notify the IRD.
Concluding Comments
CbCR is a very unique tax return: there is no tax to be calculated and no money to be paid, the “taxpayer” can in some cases choose where to file it but need to comply with all the CbCR rules and regulations in all jurisdictions that the taxpayer operates in, and corporate restructuring or M&A could bring chaos to the filing. In an acquisition, the buyer will need to obtain warranties or indemnities from the seller for exposures relating to CbCR.
With all the complexities, jurisdictions should implement the CbCR rules in a lenient manner, thereby reducing the pain felt by businesses. For instance, Singapore only accepts UPE filing (i.e. the MNE Group whose UPE is a Singapore tax resident, and no Surrogate Parent or Local Filing is accepted) and the local tax office (IRAS) would inform the UPE that they need to file the CbCR. Why would Singapore give up such power to collect information?
For a relatively small tax jurisdiction like Singapore where many foreign MNE Groups have set up subsidiaries, as long as Singapore has wide AEOI network, she is going to obtain the CbCR filed by the MNE Group elsewhere without imposing undue filing burden on the local taxpayers. According to the OECD website, at present (February 2019), Singapore can obtain CbCR from 63 jurisdictions, mostly from 2016 onwards. Hong Kong can obtain the CbCR from 56 jurisdictions but mostly only from 2019 onwards (before 2019, Hong Kong can only exchange with the 11 jurisdictions mentioned earlier).
Even if Singapore is not collecting all CbCR now, over time, when all jurisdictions around the world have introduced CbCR rules (Action 13 is one of the minimum standards that over 125 jurisdictions, by joining the OECD Inclusive Framework, have agreed to implement), Singapore will collect all CbCR from MNE Groups that operate in Singapore. Comparing with Singapore, subsidiaries of foreign MNE Groups in Hong Kong face the Local Filing burden, notification requirement (and need to obtain the e-Cert), the record-keeping obligations, and face potentially very heavy penalties. Which jurisdiction is wiser: Singapore or Hong Kong?
In case one is not convinced, Singapore’s CbCR filing would be done by sending the CbCR in XML format to the IRAS simply by email.
Tax-imposing jurisdictions would care more about CbCR because they may be able to detect BEPS risks. Tax Havens, however, are introducing CbCR regulations mainly to satisfy the demands of the international community through their participation in the OECD Inclusive Framework. One would expect that Tax Havens would make the process simple and just do the collection and exchange of the CbCR. Not so. The British Virgin Islands (BVI) issued the CbCR Guidance Notes on 19 February 2019 which requires the MNE Groups to provide details of each BVI CE, including those being tax residents elsewhere, on an Excel template.
BVI CbCR Registration
It is probable that the designers of CbCR did not foresee the difficulties and trouble faced by MNE Groups for trying to meet the CbCR notification and filing requirements. Maybe they do not care because in their minds, the MNE Groups have been avoiding taxes and it is time to pay off. It can be foreseen that the tax offices, especially in the OECD countries, will soon announce that the CbCR is leading to successful tax audits recovering millions in taxes. If that is not happening, the scope of CbCR may be extended upon review in 2020, requiring MNE Groups to disclose more information, and lowering the revenue thresholds so that more MNE Groups will need to comply. More resources will have to be deployed by tax offices and MNE Groups to deal with CbCR.
Tax Tips
Readers should by now have an idea of how CbCR is going to hit like a tsunami, except that there is nowhere to hide if the revenue threshold is breached. The best advice is to start preparation early, especially for those MNE Groups that are about to breach the EUR750 million threshold soon. Pick the right Project Manager (we can help!) and do a Dry Run would be the best tips for handling CbCR compliance.
Readers should note that the objective of this article is to highlight the key provisions in the CbCR Rules. For completeness, Readers are advised to seek professional assistance to enhance their understanding of the rules, their obligations and the penalty provisions.
Lastly, answers to the true or false questions:
CEs refer to entities that the UPE owns 50% or more. FALSE
Representative Offices or Branches with separate accounts are themselves CEs. TRUE
“Revenue” includes capital gains. TRUE
Related parties transactions can be eliminated for reporting. FALSE
Income tax paid does not include foreign taxes. FALSE
A CE that left the group during the year (e.g. disposed of) can be excluded from the CbCR for that year. FALSE
The number of employees includes independent contractors. TRUE
The Tax Identification Numbers (taxpayer file number) and addresses of CEs are not required for CbCR filing. FALSE
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 26 February 2019: https://manageyourtax.com/HKEJ Forum 20 )
Many people may have forgotten about the “Summit on New Directions for Taxation” held in October last year. In his speech for the event, the Financial Secretary Mr. Paul Chan said that “the most important aspect of today’s Summit is the discussion on how taxation (policy) can play a role in the economic development (of Hong Kong) in multiple directions”, and praised that “our tax system is simple, provides certainty, and it is implemented consistently”. The Financial Secretary also mentioned that the Tax Policy Unit set up in April 2017 is working at full speed, demonstrating the determination of the Government to actively pursue economic growth and development of industries through tax policies.
The Government has indeed done a lot of work on taxation in the past year. Some are for the implementation of the BEPS Minimum Standard (such as the transfer pricing regulations), and some relate to the expansion of industries, such as the super-deduction on research and development expenditure. This issue of Tax Tips discusses Section 15F Sums derived from intellectual property by non-Hong Kong resident associates (“15F”) of the Inland Revenue Ordinance (“IRO”) hidden in the transfer pricing regulations under Inland Revenue (Amendment) (No. 6) Ordinance 2018. 15F was passed by the Legislative Council and is effective from 1 April 2019 onwards.
What Does 15F Say
In simple terms, when a person (say a Hong Kong company, “HK Co”) performs any of the development, enhancement, maintenance, protection or exploitation (collectively as “DEMPE”) activities in Hong Kong for any intellectual property (“IP”), that person would be regarded as having contributed to the value creation of the IP. If a non-Hong Kong associated person (say “X Co”) receives a sum for the exhibition, use or imparting of the IP or the rights of the IP inside or outside Hong Kong, a sum associated with value contributed by HK Co (the “relevant sum”), if not already subject to Hong Kong profits tax, would be deemed as Hong Kong sourced income of HK Co and subject to profits tax.
The original text of 15F* can be found here for Reader’s easy reference.
According to 15F, no matter HK Co is the owner of the IP or not, provided that HK Co has performed any of the DEMPE activities for an IP to contribute value to it, including carrying out the relevant functions, providing assets, or taking up the relevant risks, and the offshore associate (X Co) receives “a sum” from the IP and has not paid any Hong Kong profits tax on any part of the sum, 15F empowers the Hong Kong Inland Revenue Department (“IRD”) to deem the relevant sum as income of HK Co and taxed accordingly.
Readers may already have questions in mind about 15F, some of which may be covered below:
What is the meaning of “a sum”? Is it restricted to mean an identifiable sum received by X Co for the use of the IP? If the IP is a brand, and X Co uses the brand to sell goods, is the sales revenue “a sum”?
Would DEMPE activities performed by HK Co before 1 April 2019 be included in the analysis?
How would the IRD determine the “relevant sum” if the IP is used by various subsidiaries or joint ventures of X Co in different countries, and HK Co is unable to obtain the detailed information of the income of these companies? Even if HK Co is able to provide the information, how would the IRD assess the value contributed by these companies in order to accurately calculate the “relevant sum”?
Under the IRO, is HK Co legally bound to provide information of X Co and the various subsidiaries or joint ventures in different countries to prove whether these companies have each received “a sum” and the amounts?
If HK Co is the owner of the IP and transferred the IP to X Co at an arm’s length price, why would HK Co not be exempt from 15F?
Income of X Co and the various subsidiaries or joint ventures in different countries derived from the IP may have been subject to tax in the relevant countries; if part or all of the income is deemed to be taxable income of HK Co and subject to Hong Kong profits tax, the issue of double taxation would arise. As the double taxation is not arising from a transaction between two jurisdictions but it stems only from the deeming provisions of the IRO, the issue cannot be resolved on a bilateral basis even if Hong Kong and the other side(s) has a Double Tax Arrangement (“DTA”) signed. How would the IRD deal with this issue? Would HK Co be required to provide evidence of tax payment by the various offshore companies in order to avoid an assessment under 15F?
How would the statutory auditors ascertain the tax provision of the X Co Group (including HK Co, all together referred to as “X Group”)? If there is a multinational group interested to acquire X Group, how would the buyer assess the tax exposure of X Group under 15F?
The above may only be some of the questions created by 15F.
Facebook’s Data Centre
Last month, Facebook announced that it will invest US$1 billion to build its 15th data centre, the first in Asia, in Singapore. Tax consideration is not mentioned in the media reports covering this news. It can be imagined that some kind of DEMPE activities must be carried out in the data centre, creating certain IP to be used in different parts of the world. If Facebook were to select Hong Kong as the location for the data centre, would they be worried about the threat of 15F?
Would multinational groups or other tech giants be scared away from Hong Kong because of 15F when they select the location to invest in Asia to carry out DEMPE activities related to IP? It is entirely possible that multinational groups, in any industry, may choose to avoid Hong Kong because of tax risks and uncertainties created by 15F!
Voice Against 15F
When the Inland Revenue (Amendment) (No. 6) Bill 2017 (“the Bill”) was gazetted last year, many professional organisations made submissions to the Bills Committee voicing out concerns on 15F, some even requested that 15F be removed. The Government responded that there are companies that transfer legal ownership of IPs to associates in low-tax jurisdictions where no DEMPE activities are performed but earn the IP income. In order to align taxation with value-creation, which is the objective of BEPS, the Government is introducing 15F to combat such profits shifting activities. The Government claimed that DTA partners are adopting a similar approach to transfer pricing, and genuine commercial transactions would not be affected.
Lastly, in order to pass the Bill (and 15F), the Government has said that various issues will be clarified in a Departmental Interpretation and Practice Notes (“DIPN”) to be issued, and deferred the commencement date of 15F to 1 April 2019 to allow more lead time to taxpayers.
Tax Tips
The scope of 15F is very wide and it is not a specific anti-avoidance provision. 15F would apply even if the taxpayer is not engaged in any tax avoidance. Under the shadow of 15F, the statement that “our tax system is simple, provides certainty, and it is implemented consistently” would no longer be true. 15F discourages companies to conduct IP-related activities in Hong Kong, which is in direct contradiction to the Government policy of encouraging research and development activities in Hong Kong.
If the law is flawed, DIPN would not make it flawless. Therefore, the best approach to 15F is to ask the Government to repeal it or amend it substantially such that it only applies in limited circumstances. The Author would raise the demand through the appropriate professional organisation. In the meantime, Readers may also raise the issue via appropriate means.
If the Government refuses to amend 15F, the only way to eliminate tax risk is not to carry out any DEMPE activities in Hong Kong, which is basically an impossible task. Companies should thus wait for the DIPN before deciding the action to take.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 9 October 2018: https://manageyourtax.com/HKEJ Forum 16)
The global crackdown on tax avoidance and money laundering at both individual and corporate levels have brought about a substantial increase in disclosure in the financial world. Anyone who has the experience of trying to open a bank account for a company would know, as part of the bank’s Know Your Client (KYC) procedure thanks to FATCA and the Common Reporting Standard, that there will be questions on the beneficial owner and tax residency of the company. If one is lucky enough to have to file the Country-by-Country Report (“CbCR”, see Tax Tips 3), tax residency of every Constituent Entity in the group shall be reported. There could be serious consequences of incorrectly reporting the tax residency.
Tax residency of a company would be relatively straight-forward if it is incorporated and filed tax returns in a jurisdiction where there is income tax or profits tax. What if the company is incorporated in a jurisdiction that does not impose income tax (commonly referred to as an “Offshore Company”), such as Tax Havens like the British Virgin Islands (BVI), Bermuda, Western Samoa? Many people think that Offshore Companies are not subject to tax anywhere…is it really the case?
Becoming Taxable in Another Jurisdiction
Business profits of a company (say “Co A” located in Country A) could be subject to tax in another jurisdiction (say Country B) under two situations: (1) Co A has become a tax resident in Country B; or (2) Co A is a tax resident of Country A and has created a Permanent Establishment (“PE”) in Country B. The difference between the two is that as a tax resident of Country B, Co A may be subject to tax in Country B in full. On the other hand, if a PE is created, only the business profits attributable to the PE is subject to tax in Country B.
A company can also be taxable in a foreign jurisdiction without tax residency or PE. That would be the case on capital gains or passive income such as dividend, royalties and interests derived from that foreign jurisdiction.
This article focuses on business profits situation one: under what circumstances would a company become a tax resident in a foreign jurisdiction.
Determination of Tax Residency
For Hong Kong, the concept of tax residency does not attract too much attention because of the territorial concept of taxation. A foreign company would be taxed in Hong Kong just like a local Hong Kong company when it carries on a trade, profession or business in Hong Kong and derives Hong Kong sourced profits therefrom.
However, in many residency-based tax jurisdictions, a foreign company would be subject to income tax in full if it is regarded as a tax resident and carries on business in the jurisdiction. What determines tax residency? Using Australia as an example, a company is a resident of Australia under Subsection 6(1) of the Income tax Assessment Act 1936, if:
it is incorporated in Australia, or
if it is not incorporated in Australia, it carries on business in Australia and has either:
its voting power controlled by shareholders who are resident of Australia (the voting power test of residency), or;
its central management and control in Australia (the central management and control test of residency).
For a company incorporated outside of Australia, the test, essentially, is to lift the corporate veil and see in substance whether the company is really managed and controlled in Australia, just like a company incorporated in Australia.
Tax residency is also highly relevant in determining if a Double Taxation Agreement/Arrangement (“DTA”) is applicable to the company or not. Using the DTA entered into between Hong Kong and Mainland China (“HK-CN DTA”) as example, a resident in Hong Kong, for a company, is defined under Article 4(1) of the HK-CN DTA as “a company incorporated in Hong Kong, or if incorporated outside Hong Kong, being normally managed or controlled in Hong Kong”. Under Article 4(3), when “a person other than an individual is a resident of both Sides, then it shall be deemed to be a resident only of the Side in which its place of effective management is situated”. The place of effective management (“POEM”) is the tie-breaker in determining which Side should the company be regarded as a resident of. Readers should note that in the OECD Model Tax Convention on Income and on Capital: Condensed Version 2017 (“the 2017 Model Tax Convention”), the tie-breaker clause has been revised such that the two sides shall agree on the matter with due consideration of the place of effective management, place of incorporation and any other relevant factors. It is however up to the contracting sides to adopt the previous tie-breaker clause, which reads exactly like Article 4(3) of the HK-CN DTA mentioned above.
Not only is tax residency relevant to Hong Kong under DTAs, the concept is also being introduced under the transfer pricing rules in the Inland Revenue (Amendment) (No.6) Bill 2017 (“the Bill”) which was enacted on 4 July 2018. “Hong Kong resident person” is defined to mean “a person who is resident for tax purposes in Hong Kong”, and “resident for tax purposes”, for a company, means “a company incorporated in Hong Kong or, if incorporated outside Hong Kong, normally managed or controlled in Hong Kong”.
The Place of Management and Control
Among the three terms came across above: the normal place of management and control, the central place of management and control, and the place of effective management (POEM), it appears that the “normal” place of management and control is a comparatively relaxed definition, and thus it may be easier for companies to be considered a tax resident in such case, which may or may not be a good thing. Legal experts will be able to better differentiate the three terms.
From a practical standpoint, what corporates would like to avoid, in most situations, is to be regarded as a tax resident unexpectedly. There will not be a One-Size-Fits-All guidance on what characteristics of management and control would make a company a tax resident of a foreign jurisdiction. For the purpose of this article, the search is, therefore, for general guidance on The Place of Management and Control (“TPMC”) that corporates can follow to help lower the chance of their Offshore Companies inadvertently become tax residents of residency-based tax jurisdictions.
Guidance on TPMC
OECD would be a handy resource to look for an answer. With the change in the Article 4(3) of the 2017 Model Tax Convention, the Commentary (of the Condensed Version) no longer provides an explanation to POEM. To understand OECD’s view on the matter, one may go back to the Commentary to the previous version of the Model Convention (Model Tax Convention on Income and on Capital 2014 (Full Version)), which says: “The POEM is the place where key management and commercial decisions that are necessary for the conduct of the entity’s business as a whole are in substance made. All relevant facts and circumstances must be examined to determine the POEM. An entity may have more than one place of management, but it can have only one POEM at any one time”. This definition is helpful but not in sufficient details for companies to follow and act on.
A good reference to offshore companies would be the Tax Ruling TR 2018/5 Income Tax: Central Management and Control Test of Residency issued by the Australian Tax Office (ATO) on 21 June 2018 (with an effective date of 15 March 2017). The three questions related to Central Management and Control are: What is it? Who exercises it? Where is it?
(1) What does central management and control mean?
Per TR 2018/5, the key element in the control and direction of a company’s operations is the making of high-level decisions that set the company’s general policies, and determine the direction of its operations and the type of transactions it will enter. It is different from the day-to-day conduct and management of its activities and operations, which is not ordinarily regarded as an act of central management and control. However, for small companies, their day-to-day conduct and management of a company’s operations might also be an exercise of central management and control.
What is “decision making”?
A person, or group of people, make a decision if they actively consider and decide to do, or not do something based on it being in the best interests of the company. It does not include the mere implementation, or rubber-stamping, of decisions made by others.
Acts of central management and control
Exercising central management and control of a company can involve setting investment and operational policy including buying and selling of stock or significant assets, appointing company officers, overseeing and controlling those appointed to carry out the day-to-day business of the company, and matters of finance, including determining how profits are used and the declaration of dividends.
Matters of company administration such as keeping a company’s share register, accounts, payment of dividend, are not acts of central management and control.
(2) Who exercises central management and control?
Identifying who exercises central management and control is a question of fact. It cannot be determined solely by identifying who has the legal power or authority to control and direct a company. The crucial question is who controls and directs a company’s operations in reality.
Normally, where a company is run by its directors in accordance with its constitution and the company law rules applicable to that company, which give its directors the power to manage the company, the company’s directors will control and direct its operations. It follows that ordinarily it is a company’s directors who exercise its central management and control.
When determining who exercises a company’s central management and control, all the relevant facts and circumstances must be considered. Facts and circumstances to be considered include the role of anyone who assumes the directors’ role in managing and controlling the company’s affairs or has a role in the decision-making processes or governance of the company. Therefore, mere legal power or authority to manage a company is not sufficient to establish an exercise of central management and control. On the other hand, the ATO would also examine who tacitly control and regularly exercise oversight of the affairs of the company. As such, legal authority or power is not necessary for a person to exercise central management and control. If an outsider actually dictates or controls the decisions made by the directors, the outsider will exercise central management and control of the company.
The directors’ knowledge of the business is also relevant. A lack of knowledge of the business sufficient to enable them to make decisions, suggests they are not the real decision makers and are more likely rubber-stamping or implementing decisions already made by others.
(3) Where is central management and control exercised?
A company will be controlled and directed where those making its high-level decisions do so as a matter of fact and substance. It is not where they are merely recorded and formalised, or where the company’s constitution, bylaws or articles of association require it be controlled and directed if, in reality, it occurs elsewhere. This will not necessarily be the place where those who control and direct a company live.
Multiple places of central management and control
Control and direction of a company may be undertaken by those controlling a company in multiple places. This means a company’s central management and control may be divided between more than one place. However, a company’s central management and control will only be exercised in a place for the purpose of the central management and control test if it is exercised in that place to a substantial degree, sufficient to conclude the company is really carrying on business there.
Residence of directors vs residence of a company
Where a company’s central management and control is exercised is not determined by where the directors, or other persons, who control and manage it, are resident or live. What matters is where they actually perform the activities to control and direct the company.
Summary
TR 2018/5 is a good reference because it is newly issued guidance which presumably has taken into account the latest court cases and BEPS. According to the ruling, in summary, TPMC is the location where the making of high-level decisions that set the company’s general policies, determine the direction of its operations and the type of transactions it will enter into, are made in substance.
The Offshore Company
Many individuals and corporate groups have set up companies in Offshore Tax Havens such as the BVI for various purposes. Many tax offices around the world see them, understandably, as tax avoidance vehicles because some of these companies book large amount business income from trade, services or intellectual properties. These individuals or corporate groups are not based in the offshore paradises but in the onshore commercial centres of the world, and often the directors of these offshore companies are the individual themselves or the senior management of the corporate groups. Even if local residents are appointed as directors, they would be acting as nominee only and tax offices will see-through them. Therefore, if not structured and maintained properly, TPMC of these Offshore Companies would be in the onshore commercial centres where the decisions are made, and the tax and penalties exposures could be significant. In the past, they could be hidden from sight but in the new transparent world, they will be exposed.
Offshore Companies are, on the other hand, the ideal type of vehicle for investment holding. They are inexpensive to maintain, useful in organising the group structure, aligning the financial results with management responsibilities, ring-fence risks, and offer great flexibility when a particular arm of the business is to be disposed of: the transaction can be done quickly without burdensome governmental administrative process. Although there may not be tax avoidance motive behind such a structure as the income of holding companies, namely dividend and capital gains, are often not taxed in many jurisdictions, corporates with such offshore holding companies should also be mindful of the issue of tax residency to avoid surprises, because these days tax offices are all trying to tax untaxed income.
Tax Tips
As the world is getting more transparent, corporates with Offshore Companies in the group structure should revisit the tax residency of such companies based on each company’s facts and circumstances and the applicable tax rules. One should note that having established TPMC is not necessarily the end of the risk analysis: the requirement of carrying on business is also relevant in many jurisdictions in determining tax residency. With the information in hand, corporates can decide what to do: make the necessary changes, perform tax filings, or prepare documentation for future defence as appropriate. No corporate can avoid exposures to tax but by knowing the risks and actively managing them would help win half of the battle. Corporates should review their organisational structures at once.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 12 July 2018: https://manageyourtax.com/HKEJ Forum 13)
The Inland Revenue (Amendment) (No. 6) Bill 2017 (the “Bill”) that was discussed in Tax Tips (2) and (3) proposed to introduce Part 8AA – Transfer Pricing Rules to the Inland Revenue Ordinance. Transfer Pricing rules require transactions with associated enterprises be conducted under the Arm’s Length Principle. Section 50AAD(1) of Part 8AA reads: “This Part applies in determining a person’s liability for property tax, salaries tax and profits tax”. Putting aside Property Tax and Salaries Tax (the Author does not think that it is appropriate to extend transfer pricing regulations to Salaries Tax), the Author’s interpretation of this Section is that “when a person is liable to Profits Tax, Part 8AA operates to determine the extent of the liability”. Whether a person is liable to Profits Tax, one shall mainly refer to Section 14(1) of the Inland Revenue Ordinance, which says:
Subject to the provisions of this Ordinance, profits tax shall be charged for each year of assessment at the standard rate on every person carrying on a trade, profession or business in Hong Kong in respect of his assessable profits arising in or derived from Hong Kong for that year from such trade, profession or business (excluding profits arising from the sale of capital assets) as ascertained in accordance with this Part.
If the profits of a connected transaction are derived from outside Hong Kong and not subject to Profits Tax under Section 14(1), the Hong Kong taxpayer should be regarded as “not liable to profits tax” and thus Section 50AAD(1) of Part 8AA would not be applicable. Even if the Hong Kong taxpayer has substantive business and operating activities in Hong Kong, as long as the profits of the connected transactions are derived from outside Hong Kong, the Inland Revenue Department (“IRD”) should not impose Profits Tax on the profits attributable to the risks assumed and functions carried out in Hong Kong. This is the correct treatment because if the substantive business activities carried out by non-associated enterprises would not be subject to Profits Tax, the same activities carried out by associated enterprises should not be treated differently. This principle has been mentioned in Paragraph 71 of the Departmental Interpretation and Practice Notes No. 46 – Transfer Pricing Guidelines – Methodologies and Related Issues (December 2009) (“DIPN 46”). In theory, the principle of territorial-based taxation is maintained.
Connected Transactions in D25/14
In the last issue of Tax Tips, the Inland Revenue Board of Review (“BOR”) Decision for Case D25/14 (published in February 2016 Volume 30 First Supplement) was discussed. Although the matter in dispute was not related to transfer pricing, as the case involved both the source of profits and transfer pricing, it can be used to discuss this topic: if Part 8AA Section 50AAD(1) was already the law, how would it apply to the case? [Please refer to Tax Tips (5) for the background of the case]
Case Appellant Company A (“Co A, a Hong Kong company) had no employee and asset in Hong Kong, all contracts were entered into and performed outside Hong Kong, but the BOR determined that regardless of the whereabouts of the controlling staff and the places where the contract was entered into and performed, the trading between Taiwan Co and Mainland Co would have been impossible in the absence of the Appellant as the “middleman”. The activity of playing such role was obviously in Hong Kong. The BOR rejected the Appellant’s argument that “the profits were not arising in or derived from Hong Kong”, and confirmed that the profits of Co A were fully subject to Profits Tax. Assuming Part 8AA has been implemented, given that Co A’s transaction was definitely a connected transaction and has been ruled by the BOR to be liable to Profits Tax, how would the IRD “determine the extent of such liability?”
Under normal circumstances, “to determine the extent of such liability”, one basically assumes Co A was not an associated company of Taiwan Co and Mainland Co, and based on Co A’s functions, risks, government policies etc., search for comparable companies in the market, select the appropriate transfer pricing method to determine whether Co A’s profit is lower than those earned by comparable companies under the Arm’s Length Principle. If it is determined to be lower than the arm’s length profits, the IRD may adjust the assessable profits upward and assess Profits Tax. Although Co A’s case did not disclose the functions performed and risks assumed by each of the affiliated companies, it can be reasonably assumed that most of the risks were borne by Taiwan Co, such as bad debts, cargo insurance, foreign exchange risks etc. The three companies each had their own functions, but Co A did not have employee and asset so it could only have performed limited functions. In addition, as Co A only served as an intermediary for the entire transaction, if the Taiwan Co did not own Co A, but rather traded with the mainland manufacturer through an independent, non-affiliated Hong Kong company (call it “Co X”), it would be likely that a lot of genuine Hong Kong trading companies would be happy to take up the middleman role for a relatively lower return for the limited risks it would bear. This “middleman” role, which was regarded as extremely important by the IRD and the BOR, would not seem to be very valuable from transfer pricing perspective.
The Author suspects that the entire planning behind Co A was that Co A was expected to be successful in Hong Kong Profits Tax exemption on the basis that the profits were sourced from outside Hong Kong, thus it is likely that Co A made excessive profits during the years. According to publicly available information, from 2002 to 2005, Co A’s total sales revenue was HK$237,121,169, with an aggregated pre-tax profit of HK$60,053,849 (after loss offset), resulting in a high net profit margin of 25%! Would this “very important intermediary role” be entitled to earn such a high profit? Would the Taiwan Co give more than HK$60 million of profits to the independent, non-affiliated Co X? As for the Mainland Co, the total profits from 2002 to 2005 was only RMB918,234 (after loss offset)! It seems that Co A was carefully operated to lower the group’s overall tax burden by making the offshore claim.
Anti-Avoidance is the Highest Principle?
The Author also suspects that the IRD was aware of the possible tax avoidance via offshore claim. As it would be inappropriate to invoke the General Anti-Avoidance provisions under Section 61A of the Inland Revenue Ordinance to tackle this case, the IRD countered such avoidance act by seeking to disallow the Offshore Claim. As the contracts of sale and purchase of Co A were effected and performed outside Hong Kong, under DIPN 21 as referred to in the last issue of the “Tax Tips” the profits would not be subject to tax in Hong Kong. In order to win the case, the IRD linked the “extremely important” middleman’s role and functions (which is a concept of transfer pricing) with the source of profits, and succeeded in winning at the cost of overturning DIPN 21. In the past, the IRD would respect the territorial concept of taxation and would not inquire whether the relevant profits were taxed elsewhere. However, under the bandwagon of BEPS(1), it seems that anti-avoidance has become the highest principle. As for the BEPS concept of “allowing companies to pay tax at the location of their real business activities and value creation”, the real idea seems to be that “if no one is claiming tax on profits, I will come forward”. Therefore, it will become more and more difficult to be granted the offshore treatment in the future (many people would have felt it already in the past few years). This is particularly worrying as the law and DIPN 21 have remained unamended.
Finally, would the IRD adjust-down Co A’s assessable profits (assuming the transfer pricing report determines that Co A’s profit is too high) in accordance with the arm’s length principle? The answer is “No”, not only because the subject matter in question is the source of profit, as a matter of policy, the IRD would simply not proactively adjust-down excessive profits. Furthermore, unless the tax authorities in the Mainland decided that Co A has constituted a permanent establishment in the Mainland and imposed a 25% corporate income tax on the profits of Co A, there is no double taxation and the IRD can safely pocket the tax revenue. This principle is also illustrated in paragraphs 71 and 72 of DIPN 46.
(1) See “Tax Tips” (1) and (2)
Tax Tips: Taxpayers must recognise the general direction and current climate of transfer pricing. Before making any arrangement, it is important to anticipate that every tax office involved in a transaction wants a share of your profits — tax authorities are increasingly interested in using “Profits Split” to divide the profits of the entire supply chain. It is conceivable that there will also be disagreements between tax authorities, and taxpayers in Hong Kong may eventually have to ask the IRD to invoke the Mutual Agreement Procedure and Arbitration under the double taxation arrangements to negotiate with the other side (or multiple sides) on who gets to tax which part of your profits. After lengthy discussions, taxpayers would also have to pay IRD the relevant fees (Section 50AAB introduced in the Bill refers). It is recommended that taxpayers should immediately review all connected transactions, collect evidence and supporting arguments, determine the most suitable transfer pricing methodologies, and prepare appropriate transfer pricing documentation to meet possible challenges in the future.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on February 26, 2018: https://manageyourtax.com/HKEJ Forum 6)
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on February 9, 2018: https://manageyourtax.com/HKEJ Forum 5).
Foreword: Bad answers to IRD enquiries can be catastrophic to other taxpayers…
As mentioned in the previous issue, one of the criteria for a good tax system is fairness, while others include simple and easy to understand, low compliance costs, high transparency and high certainty. The author started working on Hong Kong tax more than 20 years ago. At that time, the Hong Kong tax system did meet the requirements of a good tax system. But is the tax system in Hong Kong still good today? The speech by the Financial Secretary, Mr Paul Chan, at the “Summit on New Directions for Taxation” in October last year referred to the government’s tax policy direction in recent years and the future prospects. In the Tax Tips to follow the author will comment based on the Financial Secretary’s speech. The Financial Secretary said: “Hong Kong has always followed the simple low-tax system and the territorial concept of taxation. Today it has one of the lowest tax rates in the world in terms of corporations and individuals, making it the world’s premier business location … However, today we are in the 21st century, great changes are happening in the global political and economic arena. Tax measures have gradually become a means of competition among various economies, attracting investors and supporting industries through this competitive approach. We are seeing the shortcomings of Hong Kong’s simple and low tax system… “. This issue discusses the territorial concept of taxation.
The Territorial Concept of Taxation
In theory, as long as Section 14(1) of the Inland Revenue Ordinance (“IRO”) is not changed, the Government can still claim that Hong Kong is maintaining the territorial concept of taxation, the problem is whether in practice this concept is still being respected. One criticism of the Inland Revenue Department (“IRD”) is that the Department no longer respects the territorial concept of taxation. Taxpayers today are finding out that the same profits with the same offshore source would no longer be considered offshore source by the IRD. Let us first revisits what Section 14(1) says:
Subject to the provisions of this Ordinance, profits tax shall be charged for each year of assessment at the standard rate on every person carrying on a trade, profession or business in Hong Kong in respect of his assessable profits arising in or derived from Hong Kong for that year from such trade, profession or business (excluding profits arising from the sale of capital assets) as ascertained in accordance with this Part. (NB: fonts in bold added by the author)
The Inland Revenue Board of Review (“BOR”) Decision for Case D25/14 (published in February 2016 Volume 30 First Supplement) is an interesting case worth looking at. The Appellant was a Hong Kong incorporated company (“A Co”/”HK Co”) that acted as the middleman in the trading between Taiwan and the Mainland to circumvent the direct trading restriction (the “Three Direct Links” – Direct Posts, Direct Vessels, Direct Flights) between Taiwan and the Mainland at that time. The diagram below sets out the relationships and operations of the companies involved.
Except for the transshipment of raw materials and finished goods through Hong Kong, the following operations are carried out by either the Taiwan Co or employees of the Mainland Co in these two locations: receiving orders from Taiwan Co for purchasing products / contacting Mainland Co for manufacturing / negotiating with Taiwan Co for raw materials purchases / arrange the delivery of raw materials / test the quality of raw materials / test the quality of finished products / issuance of invoices, billing and settlement. The Appellant’s directors were only involved in the raw materials purchases for the Mainland Co and the activities were carried out in the Mainland. On the profits tax return, the Appellant claimed that it operated entirely outside Hong Kong and therefore did not have any profit taxable profits or losses that can be set off against profit tax. The IRD dismissed the claim issued an assessment of profits tax of HK$12.36 million in total for the years of assessment 2002/03 to 2005/06. After rounds of correspondences, the Appellant failed to convince the IRD and subsequently appealed to the BOR. The core issue of this case is the answer to the following three questions: (1) Did the Appellant carry on a trade, profession or business in Hong Kong? (2) Did the Appellant’s profits that should be assessed come from the trade, profession or business of the Appellant? (3) Was the profit arisen in or derived from Hong Kong? These three issues are precisely the conditions under Section 14 (1) of the IRD. All three conditions must be met for profits to be chargeable to Profits Tax.
What the Appellant said
The Appellant did not consider it appropriate to determine that a trade, profession or business has been established in Hong Kong solely because it was a limited company incorporated in Hong Kong. Instead, one should focus on the nature of the activities carried out in Hong Kong and exclude any ancillary activities. Since the Appellant considered its activities in Hong Kong to be ancillary in nature, the Appellant contended that no business was conducted in Hong Kong, and thus the above first condition was not met. With regard to the second condition, the Appellant did not deny that it made profits out of its business, which was conducted outside of Hong Kong. Therefore, the Appellant considered the second condition to be met, for the offshore business activities. As for the above conditions for “profits arising in or derived from Hong Kong”, the Appellant did not think Hong Kong should be the source of profits simply because the taxpayer was operating in Hong Kong. In summary, the Appellant argued that the “actual cause” of the trading profits came from the contracts which were entered into and performed outside Hong Kong. Therefore, the Appellant considered that its profits were not arising in or derived from Hong Kong, and thus the third condition was not met.
Views of the IRD Representative and Judgement by the BOR
With regard to Condition 1: whether the Appellant carried on a trade, profession or business in Hong Kong, the Board considered that the Appellant’s operations in Hong Kong was more than ancillary nature and dismissed the Appellant’s statement. The Board arguments included: A Co acted as the “middleman” and was a true legal entity with specific functions within a Taiwanese corporate group. It was not a paper company. A Co prepared financial statements in Hong Kong and has bank accounts in Hong Kong. The documents of A Co showed that the company’s business address was in Hong Kong. Another important factor is that the customs documents showed that the raw materials and finished goods landed in Hong Kong for transshipment, and the finished goods were consolidated onto a large vessel in Hong Kong for shipping to Taiwan. A Co clearly intended to ensure that trading activities must be conducted through Hong Kong. These activities are direct evidence that A Co had an actual and important business. Without this “middleman”, it would have been virtually impossible for any trade to be conducted under the environment at that time. Therefore, although A Co’s business activities were not as substantial as other trading companies, it had certain, and indeed very important, business and specific roles. The IRD representative also pointed out during the hearing that there was no evidence to show that the central management and control of the taxpayer was outside Hong Kong (the information showed that one of the five directors of A Co was a director and supervisor of the Taiwan Co, one served as both the director of Taiwan Co and Mainland Co, the other three were also directors of Mainland Co, with one of them being also the general manager of Mainland Co. It seems that none of them was managing the business of A Co in Hong Kong).
In regard to the most crucial question: Whether the profits were arising in or derived from Hong Kong, the IRD representative said: “The business of a company must be carried out in a place where the important activities are carried out, and that place is not necessarily the same place of decision making. Business can be conducted in Hong Kong with a limited scale of actual activities”. The representative of the IRD also claimed that “the place where the documents are produced [the author: the negotiation and conclusion of the contracts?] is not important for determining the source of the Appellant’s profits. The sources of profits shall be determined based on facts, which is a commercial issue rather than technical issue. In this appeal case, the reality is that the Appellant earned profits by selling goods from a subsidiary in the Mainland to the parent company in Taiwan. These sales must be routed through Hong Kong. In fact, the goods were transshipped through Hong Kong. The antecedent and ancillary activities were carried out in various locations. The actual reason for the generation of profits is the transshipment activities”.
The Board opined that in deciding whether the source of profits came from Hong Kong, the place where a contract was entered into and performed was an important factor, but not a decisive one. In investigating the activities from which the Appellant derived profits, attention must be given to the fact that the activities might not be the trading activities which one conventionally perceived (i.e. the entering into and performance of the contract, etc.). As Lord Janucey mentioned in the IRC v HK-TVB International Ltd case, “one looks to see what the taxpayer has done to earn the profit in question and where he has done it”.
The Board pointed out that the Appellant was inserted as a “middleman” to circumvent the trade restrictions in force between the Mainland and Taiwan. Although the number of activities was not large, it had a necessary role. In other words, regardless of the whereabouts of the controlling staff and the places where the contract was entered into and performed, the trading between Taiwan Co and Mainland Co would become impossible in the absence of the Appellant. The activity of playing such role was obviously in Hong Kong. There was no evidence to show that the profits were derived from outside of Hong Kong.
Lastly, the Board mentioned that according to authorities, the place where a contract was entered into was an important factor in deciding the source of profits, and the mode of trade and destination of the goods shipped might be a factor of less importance; but in light of the trade restriction which was in force at the material period, the former became peripheral and less important, while the latter was an important factor when considering the source of profits. The appeal was dismissed. The author understands that A Co has not lodged a further appeal.
What the IRD said before
Readers would likely be familiar with the “Departmental Interpretation and Practice Notes No. 21 – Locality of Profits” (Revised in July 2012). The IRD’s views which are reflected in its assessing practice on the locality of profits derived from trading in commodities or goods by a business carried on in Hong Kong are contained in Para 23, as follows:
(a) Where both the contract of purchase and contract of sale are effected in Hong Kong, the profits are fully taxable. (b) Where both the contract of purchase and contract of sale are effected outside Hong Kong, no part of the profits are taxable. (c) Where either the contract of purchase or contract of sale is effected in Hong Kong, the initial presumption will be that the profits are fully taxable. (d) Where the sale is made to a Hong Kong customer (including the Hong Kong buying office of an overseas customer), the sale contract will usually be taken as having been effected in Hong Kong. (e) Where the commodities or goods are purchased from either a Hong Kong supplier or manufacturer, the purchase contract will usually be taken as having been effected in Hong Kong. (f) Where the effecting of the purchase and sale contracts does not require travel outside Hong Kong but is carried out in Hong Kong by telephone, fax, etc., the contracts will be considered as having been effected in Hong Kong. (g) The purchase and sale contracts are important factors but all the relevant operations that produce the trading profits must be looked at to determine the locality of the profits.
DIPN 21 Para 24 reads: “Having regard to the points expressed above [author: (a) to (g) above], it will be apparent that, in the Department’s view, the question of apportionment does not arise in relation to trading profits. Trading profits will be either wholly taxable or wholly non-taxable. There is no room to substitute a mixed source for a Hong Kong source even though there might be some overseas activities”.
After revisiting DIPN 21 and look back to the case, would readers agree to the statements made by the IRD representative and the decision of the BOR? They both placed high importance on the role of the Hong Kong company but did not say anything about the contracts were entered into and performed outside Hong Kong. They focused on the essential role that the Hong Kong company played and determined the source of profits based entirely on this factor; yet the source of profits has always been determined based on the conclusion of the sales and purchase contract, but not the level of importance of the Hong Kong company (is there any middleman that has no role and not needed?). Further, without the sales and purchase contracts, there would not be any profits. If there is another identical case but without the “Three Direct Links” background (for example, replace Taiwan Co with a UK company), would the IRD and the BOR maintain the same judgment? If the conclusion would be different (offshore profits), then I would recommend the IRD to revise DIPN 21 so that taxpayers would know under what situations would profit be treated as onshore even when the contracts are effected and performed outside of Hong Kong. If the conclusion is the same (source of profits is determined based on the taxpayer’s role and degree of importance), the territorial concept of taxation is effectively abolished, and the Government should commence tax reform and amend the IRO as soon as possible.
An alternative route is profit apportionment. DIPN 21 Para 46 mentioned “The Department accepts that, notwithstanding the absence of a specific provision for apportionment of profits in the IRO, there are certain situations in which an apportionment of the chargeable profits is appropriate. The example of manufacturing profits has already been explained above. A further example is service fee income where the services are performed partly in Hong Kong and partly outside. On the other hand, as has been mentioned in paragraph 24 above, the Department does not find an apportionment of trading profits is required”. If the IRD no longer follows principles set out in Para 23, what is the reason for sticking to the principle of no apportionment of trading profits?
This case reflects the IRD’s approach to the territorial concept of taxation has changed. Numerous taxpayers may currently be in dispute with the IRD over the source of profit. When facing unreasonable assessments, many taxpayers may prefer to settle the case in view of the long appeal time and high costs. It is likely that this case of Co A will be cited by the IRD in future disputes with taxpayers. The Financial Secretary, Mr. Paul Chan, said at the end of his speech that “Our tax system is simple and clear, and its implementation is fair and consistent…we absolutely do not want to gradually make our tax system more complex, which would lead to disproportionate increase in tax administrative costs and corporate compliance costs”. In the face of today’s environment, is Hong Kong’s tax system still territorial based, easy and straightforward, apply equally to all, consistent in implementation, and low in compliance costs? Can Hong Kong continue to be, in the eyes of the Financial Secretary, the world’s premier business location? In the environment of BEPS, it seems that it is time to consult the Hong Kong people for a tax reform.
Tax Tips :
The case of A Co could have been resolved satisfactorily during the enquiry stage, and maintain that the profits were arising in or derived from outside Hong Kong. There are certain techniques in answering queries from the IRD; other than pointing out the relevant legal provisions and cases, if the IRD’s views are unreasonable, one had to point out directly the issue, such as asking the above question “If there is another identical case but without the “Three Direct Links” background (for example, replace Taiwan Co with a UK company), would the IRD argue the same?”. Besides the source of profit, the IRD’s approach in determining revenue and capital expenditures can sometimes be unreasonable too. As taxpayer or tax representative one has to know how to close the issue at an early stage.
The case also has Mainland tax implications. Co A would likely have created a permanent establishment in the Mainland (or even in Taiwan), and the Mainland tax authorities could impose corporate income tax at 25% on the profits of Co A (and Co A should claim the profits tax suffered in this appeal case from the IRD under the Hong Kong-Mainland Double Tax Arrangement?). Further, as Co A has no substance in Hong Kong, the IRD may not issue the Certificate of Residence to Co A, and the Mainland authorities would unlikely consider Co A as the beneficial owner of dividend from Mainland Co, so that Co A would not be able to enjoy the 5% dividend withholding tax rate under the Double Tax Arrangement but would need to pay 10% instead. Hong Kong taxpayers conducting similar business should learn from the case in how to improve the overall arrangement.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on January 30, 2018: https://manageyourtax.com/HKEJ Forum 4).
The current Government has repeatedly mentioned about “New Fiscal Philosophy,” and the “New Direction for Taxation” plays a key role in realising this new philosophy. The most eye-catching new tax initiative must be the two-tier profit tax system. The Government introduced the two-tier system of profits tax in the Inland Revenue (Amendment) (No. 7) Bill 2017 (the “Bill 7”) on the 29th of December 2017 and it is scheduled to be implemented in Fiscal Year 2018/19. Most people would know that the two-tier profit tax system introduced the lower 8.25% tax rate (half of the normal rate) on the first HK$2 million of assessable profits each year (a tax saving of HK$165,000 if the annual taxable profit of a company reaches HK$2 million), and each Group can only designate one company within the group to enjoy preferential tax rate. Is this design good or bad?
First look at what the Government says. The two-tier system was first proposed by Ms Carrie Lam in her campaign for the Chief Executive of Hong Kong for the purpose of “reducing the tax burden on enterprises (especially the small, medium and start-up enterprises)”. After Ms Lam’s election victory, the Government started to study the implementation, and put forward in the 2017 Policy Address that “To ensure that the tax benefits will target SMEs, we will introduce restrictions such that each group of enterprises may only nominate one enterprise to benefit from the lower tax rate”. According to the blog “Thinking about the 2018/19 Budget” released by the Financial Secretary, Mr Paul Chan, on January 7, 2018 (there is no English version), taking the 2015/16 assessment year as an example, there are about 100,000 companies paying Hong Kong Profits Tax, with distribution as follows:
Speaking at the “Summit on New Directions for Taxation” held in October last year, Financial Secretary Mr. Paul Chan said that if every company is allowed to enjoy the preferential profits tax rate, the Treasury would reduce its tax revenue by about HK$7.1 billion. The Financial Secretary also mentioned that “as the cost of setting up and maintaining a company in Hong Kong is relatively low, there would be tax revenue loss if groups spin-off companies”. In addition, “the United Kingdom introduced a similar taxation measure more than a decade ago, the corporation tax on the first £10,000 of profits was 0% with the amount exceeding that to be subject to tax. In the two years since the introduction of the initiative, new local company formation increased 40% and 20% respectively, and the UK abolished the arrangement after some years”, “therefore, after due consideration, we decided to include some provisions to such that each group is only allowed to nominate one company to benefit from the lower tax rate, which helps to concentrate tax incentives on SMEs on the one hand and at the same time make it impossible for enterprises to spin off new companies for tax concessions”. According to the statement made by the Secretary for Financial Services and the Treasury Bureau Mr James Lau, JP, on the second reading of “Bills 7” at the Legislative Council on January 10, “Assuming that 20% of the taxpayers are related enterprises, the implementation of the proposal will result in annual government tax revenue reduction of approximately HK$5.8 billion”.
The question is, is this estimate made based on the assumption that around 20% of companies have taxable profits exceeding HK$2 million? That is, the Government assumes that all enterprises with an assessable profit of more than HK$2 million are large group enterprises and the rest (80%) are SMEs or start-ups and can enjoy a low tax rate?
I have no objection to two-tier profits tax. The level of tax rates should be determined based on various factors including the international environment and consider the local policy direction. Tax increases, tax reduction or two-tier system can all achieve policy objectives. The key is to be clear about the objective. The objective of this reform is obviously to reduce the tax burden on SMEs and start-up companies. The only question, therefore, is whether the two-tier profits tax system as proposed by “Bill 7” can achieve this objective.
The “connected enterprise” mentioned by Secretary Lau should be the “connected entity” mentioned in Bill 7. The definition of “connected entity” in simple terms is an entity that controls another entity or is jointly controlled by another entity or natural person. The threshold of “control” is more than 50% (for details, see Article 4 of Bill 7 for the new S.14AAB). Accordingly, if a businessman sets up two companies to run small businesses, one is a fashion retail shop which he holds 90% interest (Friend A holds 10%), and a snackfood trading company for which he holds 60% (Friend B holds 40%), under the Bill 7 the two companies are “connected entities”, so the businessman can only choose one company to enjoy the preferential tax rate, how should he choose without upsetting one of his friends?
As a matter of fact, many small business operations require more than one company to operate. This is for business reasons such as licenses, the composition of shareholders, business categories, and risks containment. Are these small businesses “large enterprises” in the Government’s eyes? On the other hand, according to my own personal experience, many companies that belong to the same group have assessable profits of well under HK$2 million (in fact, anyone who has handled Hong Kong profits tax compliance for large and small groups would know), thus I would say Secretary Lau’s estimation is too conservative. Since there is no concession for large and small enterprises, I believe the number of companies that can enjoy the preferential tax treatment under the two-tier profits tax system would be very small. The annual cost of revenue to the Government should be well below HK$5.8 billion.
The UK Example
The provision that only allows one of the “connected entities” to enjoy the lower tax rate should be the anti-avoidance measure (Specific Anti-avoidance Rule) mentioned by the Financial Secretary to prevent companies from abusing the tax preference by splitting up profitable ones. The Financial Secretary also mentioned the example of the UK. According to the Institute for Fiscal Studies in the UK, the measure was introduced in 2000 with an applicable tax rate of 10% on the profits of the first £10,000 for the first two years (2000 and 2001) and zero for the next four years (a specific anti-avoidance provision was introduced), and the measure was abolished after 2005. The purpose of introducing the low tax rate in those days was to encourage entrepreneurship and increase employment opportunities. However, it also unexpectedly encouraged the conversion of existing self-employed persons into corporate forms, which, in addition to saving corporate tax, also reduced National Insurance contribution. As for splitting up of companies to enjoy the low rate, although not impossible, I was not able to find materials covering this point. More importantly, there was no “General Anti-Avoidance Rule” (GAAR) in the UK at that time (GAAR was introduced in the UK in 2013), meaning that the HMRC could not prosecute a company for entering into transactions or arrangement for the sole or dominant purpose of obtaining a tax benefit. On the contrary, Hong Kong has always had a GAAR (Section 61A of the Inland Revenue Ordinance).
When the Hong Kong Inland Revenue Department (“IRD”) considers any transaction has been entered into or effected and that transaction has, or would have had, the effect of conferring a tax benefit on a person, and it would be concluded that the person, or one of the persons, who entered into or carried out the transaction, did so for the sole or dominant purpose of enabling the relevant person, either alone or in conjunction with other persons, to obtain a tax benefit, the IRD shall assess the liability to tax of the relevant person as if the transaction or any part thereof had not been entered into or carried out; or in such other manner as the assistant Commissioner considers appropriate to counteract the tax benefit which would otherwise be obtained. In other words, even if there is no Special Anti-avoidance Rule in Bill 7, when an enterprise, regardless of its size, sets up a company to split its profits in order to enjoy a lower tax rate, the IRD can apply GAAR to counteract the benefits and may impose a fine. Any enterprise that avoids tax knowingly would certainly calculate the cost-effectiveness of arrangement. Although it is not ruled out that enterprises may enter into an arrangement for saving just HK$165,000 (which would be the case only if the company has assessable profits of more than HK$4 million), apart from facing GAAR, dividing a business into two business is actually not easy in practice. For example, a businessman operates a fashion retail shop and signed a five-year lease for the premises. If he now wants to split into two companies to operate the same shop, he will need to seek consent from the landlord. If you were the landlord would you agree to it unconditionally? Then the business owner needs to bill customers separately, employees shall be hired by two companies, and vendors shall contract with two companies? To save HK$165,000 for doing all these the business owner will likely end up losing money. Of course, another approach is to maintain the operation of a company and to split the account into another company by means of internal allocation and accounting entries. But would this pass the sharp eyes of the IRD assessors?
As to the question “Can the two-tier profits tax system proposed in Bill 7 help reduce the tax burden on SMEs and start-ups?”, my answer to “No”. This is because of the Special Anti-avoidance Rule contained in which is restrictive to SMEs and start-ups. This provision is complicated and deviates from the requirements of a good tax system. One of the criteria for a good tax system is “fairness”. “Fairness” means that tax treatment should be the same for different taxpayers doing the same thing. It is fair for everyone to pay a high tax rate for higher profits, but it is unfair if benefits would be denied for being part of a group. In fact, groups that set up a company to operate a business is no different from an SME, the group also needs to invest capital, hire qualified personnel and take risks, and the difference is that large groups can generally be able to do these more efficiently. Perhaps “fairness” in the eyes of the government is that all large corporations and small enterprises can only choose one company to enjoy the benefits without discrimination. Hong Kong does not have a group consolidation profits tax regime, but the lower tier profits tax rate is applied on a group basis, so there seems to be a conflict in administration.
In fact, there are quite a lot of channels for the Government to use financial means to help alleviate the burden on SMEs or start-ups, some of which may not have any assessable profit at all. The Government could consider providing low-cost office space or industrial premises consider help reduce their operating costs, and even set up some special support funds for eligible enterprises or small size groups to apply? When these enterprises become tax paying, the Government will recover the investments through tax revenue.
Tax Tips: If a business earns HK$2 million profits a year, but it is actually earned through four companies (each HK$500,000), according to the two-tier system, the business can only save HK$41,250 (instead of HK$165,000). It is time for SMEs to review the assessable profits of its companies and to choose one to enjoy the preferential tax rate in the future. If commercially viable with the business transformation, businesses have the opportunity to enjoy the HK$165,000 benefits in full. The premise, of course, is to strictly abide by the requirements of the tax regulations.
It was mentioned in the last issue that Hong Kong has become a part of the OECD BEPS “Inclusive Framework” and published the Inland Revenue (Amendment) (No. 6) Bill 2017 (the “Bill”) in the Gazette on 29 December 2017, in order to implement the “Minimum Standards” for the BEPS program in the Fiscal Year 2018/19. The Bill was passed in the Legislative Council on 4 July 2018. This issue examines how the implementation of the BEPS Action 13 “Transfer Pricing Documentation and Country-by-Country Reporting” under the “Minimum Standard” will affect Hong Kong taxpayers.
Large Hong Kong Multinational Corporations
Many large Hong Kong multinational corporations (“MNC”, Hong Kong resident groups headquartered in Hong Kong) have invested overseas. Many MNCs have been busy with complying with the BEPS Actions because they are subject to the overseas tax laws and many countries, especially the European countries, have already amended the tax regulations to incorporate the BEPS Actions. If their annual consolidated group revenues exceeded 750 million euros, the MNCs would likely have prepared the Country-by-Country Reporting (“CbCR”) and would have been filing notifications in different countries beginning the end of 2016, and by the end of 2017 file the CbCR in probably more than one country. In addition, they also need to prepare the Master File for transfer pricing, ready for inspection by tax bureaus worldwide. The Bill sets the threshold for CbCR at HK$6.8 billion. If the Bill is passed on schedule, Hong Kong’s major MNCs will have to decide whether they need to prepare the 2018 CbCRs based on whether their 2017 consolidated revenue exceeded HK$6.8 billion. By 31 December 2019, “Hong Kong Ultimate Parent Entity” shall submit the CbCR to the Hong Kong Inland Revenue Department (“IRD”). To make it more complex, MNCs need to assess whether Hong Kong can automatically exchange their CbCRs to the tax bureaus of their overseas operations. If not, these MNCs may also submit CbCRs individually in different countries, which can be an exhausting exercise.
To facilitate Readers’ understanding, I quickly summarise CbCR as follows. CbCR is a report consisting of three tables. Table 1 requires the reporting MNC to list out, by tax jurisdiction, the aggregate figures of various attributes of all entities of the MNC in that tax jurisdiction. The attributes are: (1) Revenue from Unrelated Party; (2) Revenue from Related Party; (3) Total Revenue; (4) Profits before Tax; (5) Income Tax Paid (cash basis); (6) Income Tax Accrued; (7) Stated Capital; (8) Accumulated Earnings; (9) Number of Employees; and (10) Tangible Asset (other than cash and cash equivalent). For example, an MNC group has 100 entities in Mainland China, then on the CbCR on the row for “Mainland China”, the MNC shall report the aggregated figure of each attribute for the 100 entities, translated into the reporting currency of the CbCR. Table 2 lists out every entity of the MNC group and report their tax residencies and main business activities. Table 3 is for reporting any other information such as exchange rates that helps users of the CbCR to better understand the report.
The CbCR may appear to be straight-forward, but if the MNC is very large, with operations in many jurisdictions and internally use more than one accounting software, it is not an easy task to compile all the figures correctly. Although the OECD has been issuing further guidance (while MNCs are already preparing the reports), there are numerous challenges faced by MNCs in preparing the CbCR. In the last issue of Tax Tips, it was mentioned that the concept of the BEPS program is to establish a modern international tax framework that allows companies to pay tax at the location of their real business activities and value creation. CbCR is designed to let all tax bureau worldwide to have a bird’s-eye view on the MNC group’s revenue, profits, assets, and people, so as to assess if there are tax risks (potential tax avoidance activities). Since the Bill proposed to penalise the MNC (and also the service provider engaged to prepare the CbCR for the MNC) for incorrect CbCR, the IRD should issue further detailed guidance on one hand, and be lenient to MNCs on the other hand, at least for the initial years, taking into account the difficulties in preparing the CbCR error-free.
All Hong Kong Companies
Large Hong Kong MNCs and many Small and Medium-Sized Enterprises (“SMEs”) will likely be required to prepare transfer pricing Master Files and Local Files. According to the Bill, if the company satisfies two of the below three conditions, it will have to prepare Local File for itself and Master File for the Group:
Total Amount of Revenue: HK$400 million
Total Value of Assets: HK$300 million
Average number of employees: 100
Notwithstanding, SMEs would be able to reduce compliance costs if they satisfy conditions set out in the Bill. Based on the type of transaction, provided that the amounts of controlled transactions are under the thresholds, no transfer pricing documentation shall be prepared for that relevant transaction. Insofar as domestic transactions between associated persons that do not give rise to actual tax difference (or domestic transactions involving non-arm’s length loans (e.g. interest-free loans) that are not carried out in the ordinary course of money lending or intra-group financing business), and provided that such transactions do not have a tax avoidance purpose, then the relevant persons will not be obliged to compute the income or loss arising from these transactions on the basis of the arm’s length provision in their tax returns and no corresponding assessment on that basis will be made by IRD. The Bill has therefore exempted domestic transactions from the preparation of transfer pricing documentation. As a related matter, therefore, the volume of domestic controlled transaction would also be disregarded in assessing if the company has breached the nature and volume threshold for preparing the documentation. If the company’s controlled transactions fall below all four thresholds, the company is exempt from preparing the Local File and Group Master File:
Transfers of properties (whether movable or immovable but excluding financial assets and intangibles) HK$220 million
Transactions in respect of financial assets HK$110 million
Transfers of intangibles HK$110 million
Other transactions HK$44 million
I prepared the below diagram to facilitate Readers’ understanding.
These thresholds seem clear, but as always, the devils are in the details. For example, what is meant by “total amount of revenue”? Is it only the top line revenue in the profit and loss account, or would it also include items such as asset disposal gains, exchange gains, interest income and dividend income? “Total value of assets” is relatively simple, but do not forget that if an enterprise leases assets under an operating lease, according to IFRS 16, to be implemented on January 1, 2019, lessees may need to book the value of the assets and companies are therefore more likely than before in breaching the threshold. As for the type of the company’s annual related party transactions, in the case of related party loans, is the threshold based on the loan amount or interest amount? It seems that some techniques are required in classifying related party transactions in order to decide whether the relevant transfer pricing documentation shall be prepared. To avoid any controversy and inconvenience, the tax authorities should formulate relevant guidelines as soon as possible.
As to the deadlines for preparing the Master File and Local File, the Bill requires such documents to be completed within 9 months after the end of the accounting period. Time is tight. Companies need to understand that preparing the two files are just the beginning, the critical part is what would the IRD do with the files. Also, the Bill is silent on how the provisions work together with the territorial system of taxation in Hong Kong. Future Tax Tips will look into the area.
A couple of side-points: during the BEPS Consultation in 2016 organised by the Financial Services and Treasury Bureau (“FSTB”), the thresholds of Total Amounts of Revenue and Total Values of Assets were proposed to be HK$100 million, without the exemption conditions mentioned above. Myself, various business and tax organisations reflected to the FSTB that the thresholds were too low, and that companies with small amounts of related party transactions should not be required to prepare the documentation. The Bill has reflected the comments made. On the other hand, as many Hong Kong companies have dealings with related parties in Mainland China, the above thresholds of controlled transaction were determined with reference to the thresholds in Mainland China for preparing transfer pricing documentation, so if companies have prepared documentation to satisfy the rules in Mainland China, the documents can be easily adapted to comply with the Hong Kong rules.
Tax Tips:
(1) : CbCR does not only apply to Hong Kong Ultimate Parent Entity. If a foreign group reaches the CbCR threshold, the Hong Kong Constituent Entities are required to comply with the Hong Kong notification rules and perhaps need to file the CbCR with the IRD.
(2) : The exemption of domestic transactions between associated persons that do not give rise to actual tax difference and do not have a tax avoidance purpose from the obligation to compute the income or loss arising from these transactions on the basis of the arm’s length provision in their tax returns and the exemption of such transactions from the preparation of transfer pricing documentation would substantially reduce the administrative burden faced by companies. The Hong Kong Government estimated that around 1,000 enterprises, representing less than 2% of the total number of profits tax-paying enterprises in Hong Kong, would be required to prepare the Master File and Local File. Notwithstanding, all businesses should immediately check whether they would exceed the threshold (including considering the accounting standards changes) and prepare the relevant transfer pricing documents to meet the new requirements. As the definition of the thresholds are not clear, if the company is close to the thresholds, the conservative approach is to assume that the thresholds have been breached. More important is to prepare the supporting documents such as contracts, because in order to analyse the transaction for transfer pricing purposes one has to refer to the contract to determine the nature of the transaction and analyse the functions and risks borne by the parties to the transaction. It may be too late to start preparing in 2019.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on January 24, 2018: https://manageyourtax.com/HKEJ Forum 3. As the Bill was passed in the Legislative Council on 4 July 2018 with amendments, this Tax Tips is updated to reflect the changes).
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on January 15, 2018: https://manageyourtax.com/HKEJ Forum 2).
The last issue of Tax Tips explained what constitutes “Base Erosion and Profit Shifting” (BEPS) and mentioned that one of the main objectives of the Inland Revenue (Amendment) (No. 6) Bill 2017 (the Bill) is to incorporate the BEPS Minimum Standard into the Inland Revenue Ordinance. The Inland Revenue Ordinance affects everyone in Hong Kong. What would be the impact on the Hong Kong people? One should first understand the concept and goal of the BEPS program.
The concept of the BEPS program is to establish a modern international tax framework that allows companies to pay tax at the location of their real business activities and value creation. The goal is to create a more equitable international tax system to combat BEPS. The BEPS program identified 15 Actions along three fundamental pillars: introducing coherence in the domestic rules that affect cross-border activities, reinforcing substance requirements in the existing international standards and improving transparency, as well as certainty for businesses that do not take aggressive positions.
A small sidetrack before we continue. The example of interest-bearing loans in the last issue of Tax Tips [see attached diagram] is, in fact, Case 1.1 of the BEPS Action 2, “Neutralising the Effects of Hybrid Mismatch Arrangements”. In Action 2, OECD proposed that country B should not allow interest deduction. If Country B allows the interest expense deduction, Country A should regard the income as taxable income in order to “ensure coherence of domestic laws and regulations on cross-border transactions”. In short, OECD is asking jurisdictions to amend the tax code. Logically, Country A and Country B themselves must determine their own tax treatment according to their laws and may be tax cases (where applicable). The laws, regulations and tax cases must have been formulated by history, circumstances and people’s empowerment of the respective countries. Large and small enterprises are only acting according to the laws and regulations. Going forward, would all jurisdictions determine their tax treatments based on how the other countries rule?
Since it is an international tax framework, in theory, all 15 BEPS Actions should be unanimously implemented globally. However, it is obviously a very difficult task. Each jurisdiction has its own tax laws and legal process in amending legislation, which could take years to complete. Even the G20 countries would unlikely be able to incorporate all Actions into their own laws in one go. In order to put the most important actions into practice, the G20 and the OECD set out four Actions that cover the above three pillars to be the Minimum Standards and require all countries to join the Inclusive Framework (thus declaring their commitment to implementing the Minimum Standard). Hong Kong joined the Inclusive Framework in 2016. At present, there are more than 110 countries or regions who have “joined the club”. The Minimum Standard covers:
Action 5: Countering Harmful Tax Practices More Effectively, Taking into Account Transparency and Substance Action 6: Preventing the Granting of Treaty Benefits in Inappropriate Circumstances Action 13: Guidance on Transfer Pricing Documentation and Country-by-Country Reporting Action 14: Making Dispute Resolution Mechanisms More Effective
Actually, implementation of Action 6 has already started. The OECD implemented Action 15 “Developing a Multilateral Instrument to Modify Bilateral Tax Treaties” and published last year the “Multilateral Convention to Implement Tax Treaty Related Measures to Prevent Base Erosion and Profit Shifting” (“Multilateral Convention”). As one of the purposes of the convention is to prevent abuse of preferential tax treaties, the amendment will make it harder for taxpayers to obtain treaty benefits. In June last year, Hong Kong signed the “Multilateral Convention” by representatives of Mainland’s State Administration of Taxation in order to amend the bilateral tax arrangements signed by Hong Kong and other countries or regions in one go. As of 20 December 2017, 72 countries or regions have signed the “Multilateral Convention”, and the OECD expects that as early as the beginning of 2018, as the parties to the convention completed their respective legislative formalities related to the “Multilateral Convention,” thousands of bilateral tax treaties would be amended swiftly and implement the measures against BEPS. According to the Consultation Report on Measures to Counter BEPS released by the Financial Services and Treasury Bureau in July last year, Hong Kong plans to submit the relevant amendment bill to the Legislative Council by mid-2018 for the implementation of the Multilateral Convention.
Tax Tips: The tax arrangement that Hong Kong people are most concerned about must be the Double Tax Arrangement (“DTA”) between Hong Kong and the Mainland. The Multilateral Convention signed by the Mainland on behalf of Hong Kong does not cover the DTA between Hong Kong and the Mainland. Does it mean that the DTA will not be amended? No. It is expected that Hong Kong and the Mainland will announce how to amend (tighten) the DTA, and Hong Kong will then carry out the legislative procedures to implement the Multilateral Convention. As for what changes are in store? Stay-tuned.
About five or six years ago, the international media reported more and more tax news. However, the news was not directly related to Hong Kong. At that time, the news mainly focused on a number of large U.S. companies such as Google, Facebook, Apple, Starbucks etc, which were exposed by the media in Europe for alleged malpractice in taxation or were brought to the courts by the Tax Departments. The main reason for these happening is that the governments were short of revenue after the financial crisis, so tax audits were conducted focusing on large foreign Multinational Corporations (“MNCs”). As a result, leaders of the Group of Twenty (G20) commissioned the Organization for Economic Co-operation and Development (OECD) to study how to combat the use of international corporate structures and transactions by MNCs in 2013 for tax avoidance. This is known as the “Base Erosion and Profit Shifting” (“BEPS”). OECD released 15 BEPS Action Plans in October 2015.
What is BEPS? Let us first talk about what is meant by “Base Erosion”: “Base” refers to “tax base”, which is the basis of which tax is calculated on. Using Profits Tax as an example, the assessable profit is the tax base. “Erosion” naturally means “to reduce”. How can taxable profit be eroded? MNCs take advantage of differences in tax rules of countries to create tax benefits over the same transaction (often involving complex planning). For example, in a transaction a person making payment could get a tax deduction, and the recipient in another country does not have to pay tax on the income according to the local tax regulations (typical example: Company A in Country A lends an interest-bearing loan to Company B in Country B. Company B is allowed to deduct interest expense, while Company A is not subject to tax on the income, which is characterised under Country A’s rules to be a tax-exempt return on investment [see diagram]). “Profit Shifting” is the use of intra-group transactions to legally transfer profits from a company located in a high-tax area to another company located in a low-tax area, as long as the relevant payment is supported by the transfer pricing report (there will be more discussion on transfer pricing in future articles), to reduce the Group’s overall tax burden. In summary, BEPS refers to the tax planning strategy of MNCs making use of differences and mismatches of tax rules across different countries and artificially transferring profits to low or no-tax jurisdictions with little or no economic activity.
One of the killers of the BEPS program of action is to require the headquarters of large MNCs to complete “Country-by-Country Reports” (to be further discussed in Tax Tips 3 and Tax Tips 20) to provide detailed global operational information to the tax office-in-charge of the Ultimate Parent of the MNC, which will then be automatically exchanged with tax offices in jurisdictions where the MNC operates. Readers who are familiar with company’s structure and international tax planning should be able to foresee what would be the consequences. Tax Tips: Do not think that the BEPS program of action is just a matter for large MNCs. The Hong Kong Government gazetted the Inland Revenue (Amendment) (No. 6) Bill 2017 (“the Bill”) on 29 December 2017. The main purpose of the Bill is to include transfer pricing principles in the Inland Revenue Ordinance and to implement the minimum standards proposed by the OECD for fighting the BEPS. The Bill, which is 162 pages long, is very complex and has a profound impact on Hong Kong’s tax system. The most important point is that Hong Kong taxpayers may need to prepare transfer pricing reports even if they do not have cross-border related party transactions. In the future, the compliance costs of taxpayers will be greatly increased.
(This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 8 January 2018: https://manageyourtax.com/HKEJ Forum 1).
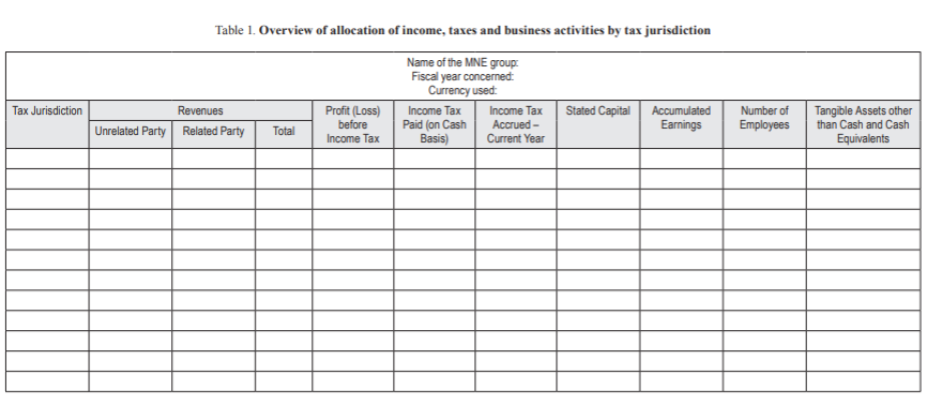
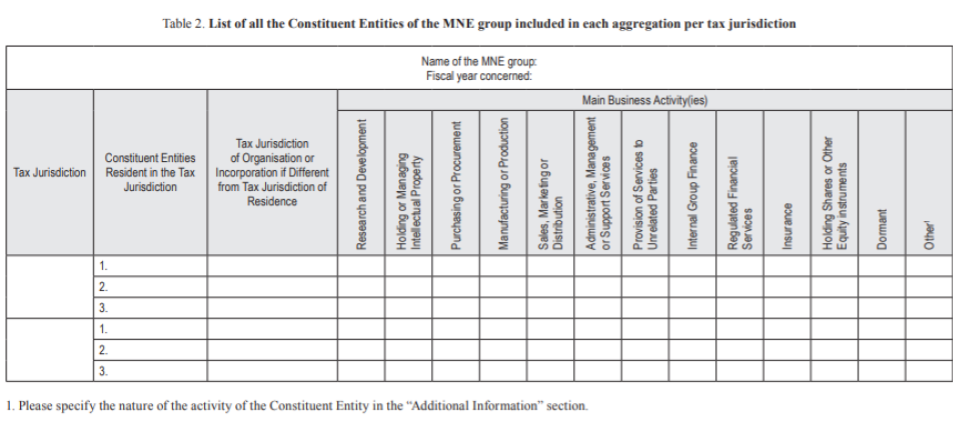
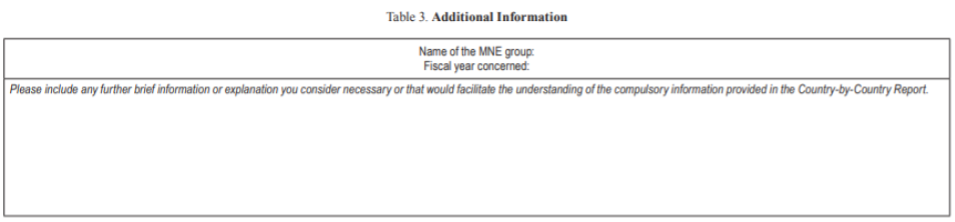
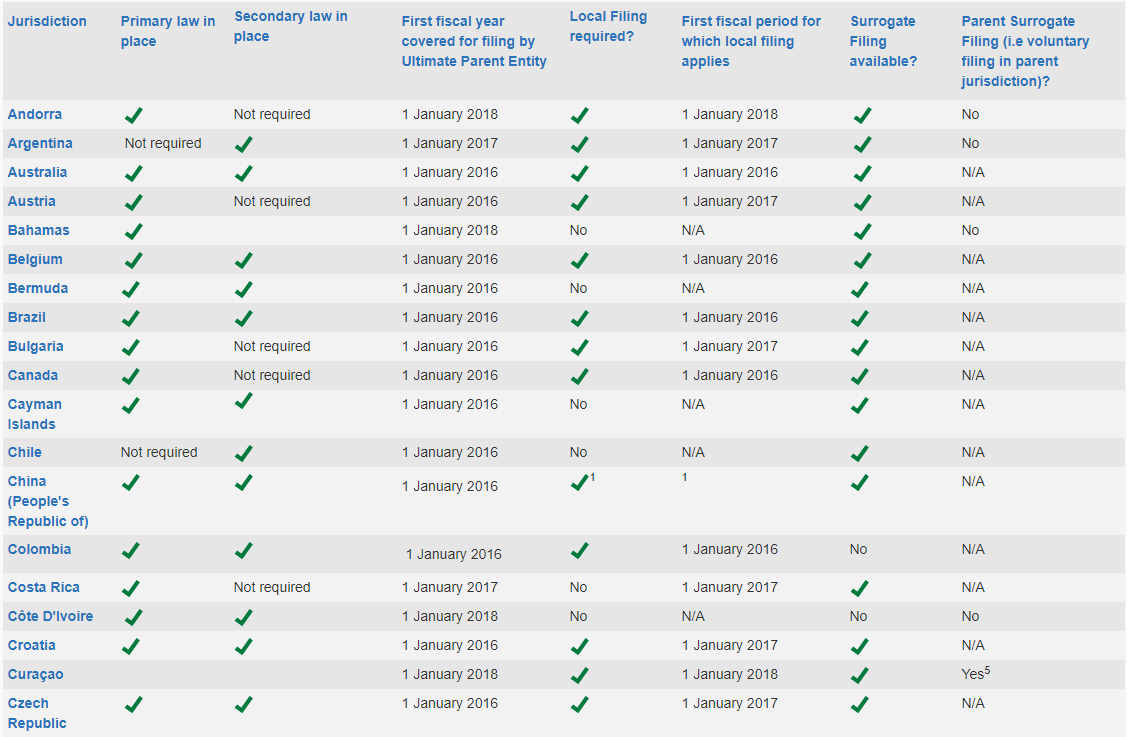
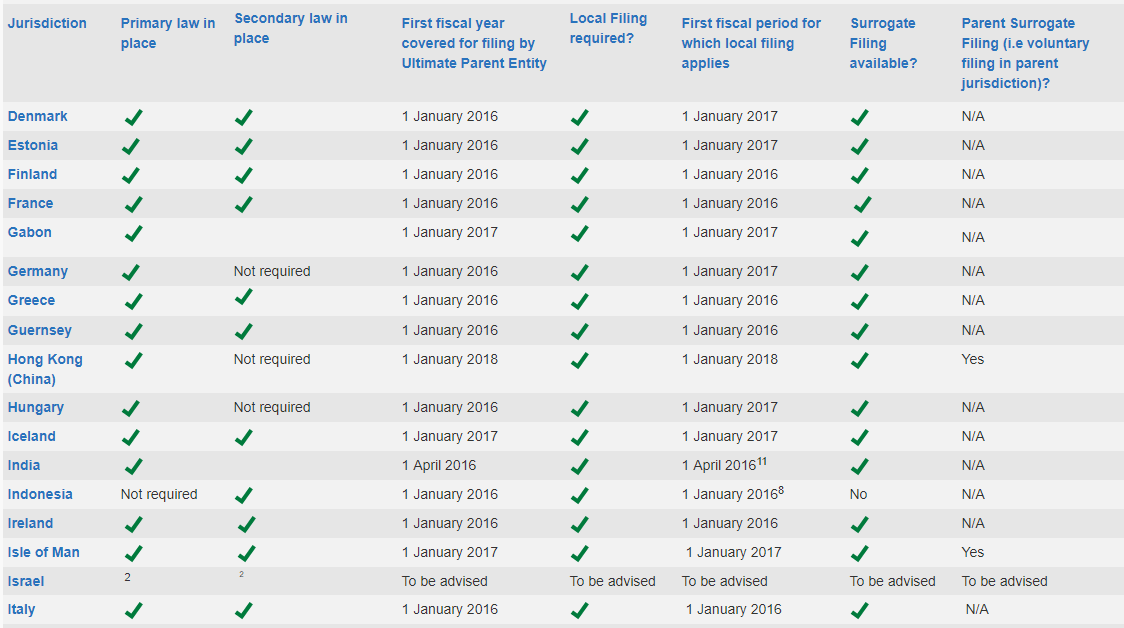
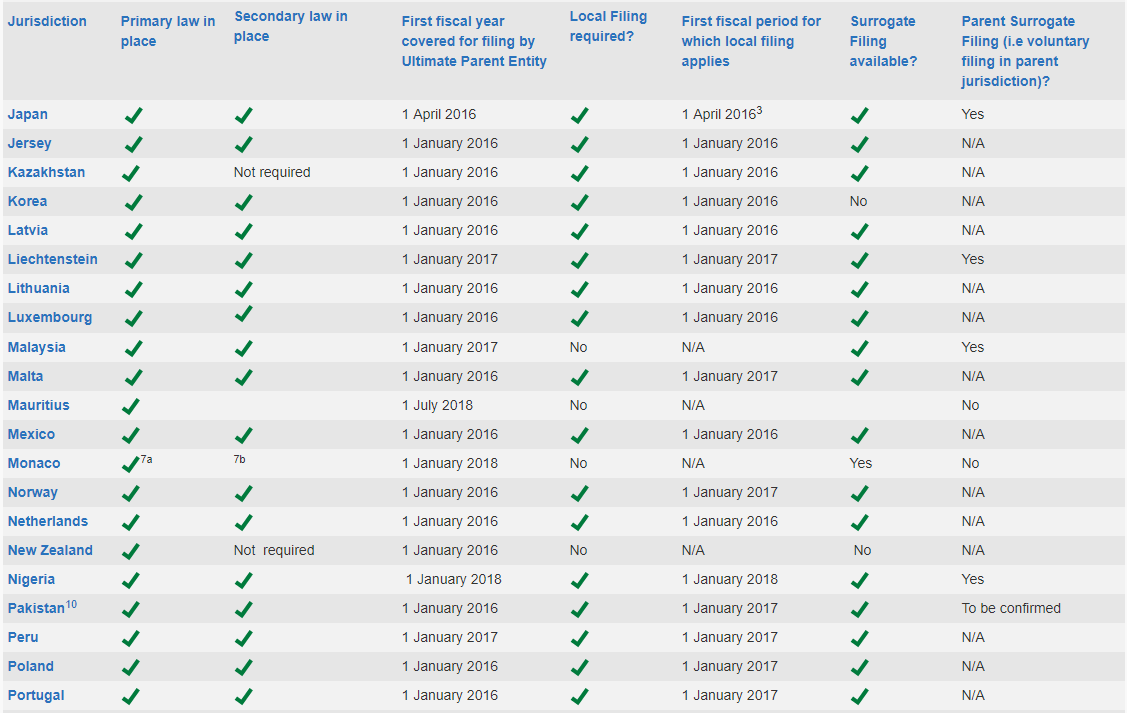
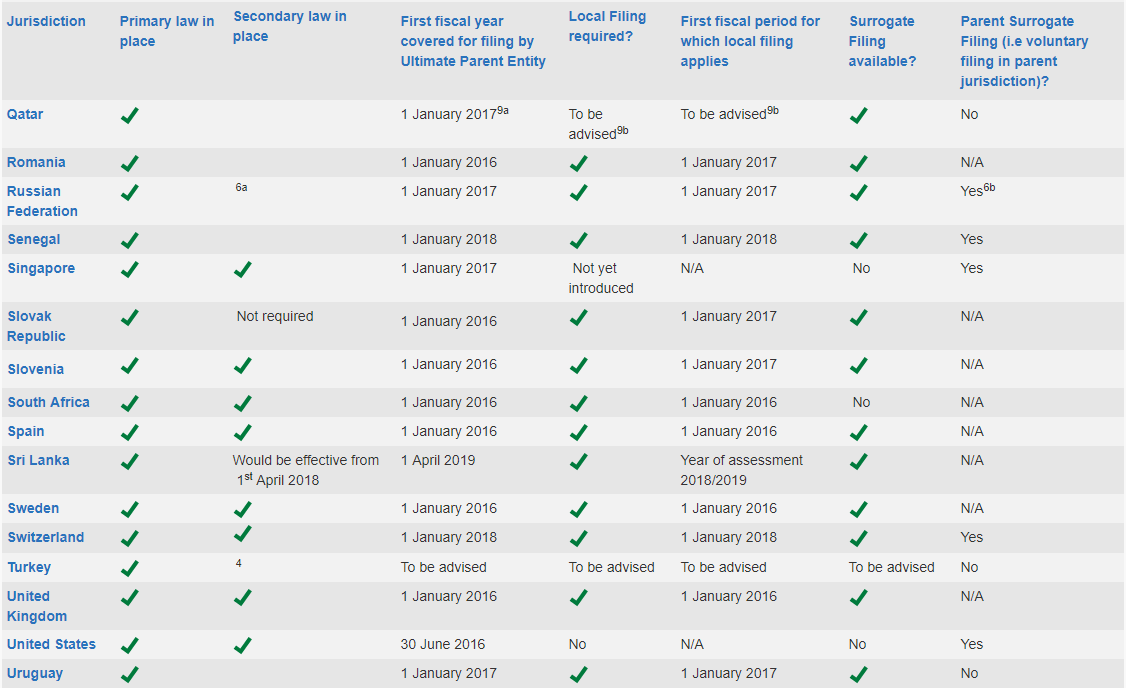 Anyone who had the experience of managing the CbCR filing for a reportable MNE Group for years 2016 and 2017 would know how much headache it is to ensure compliance.
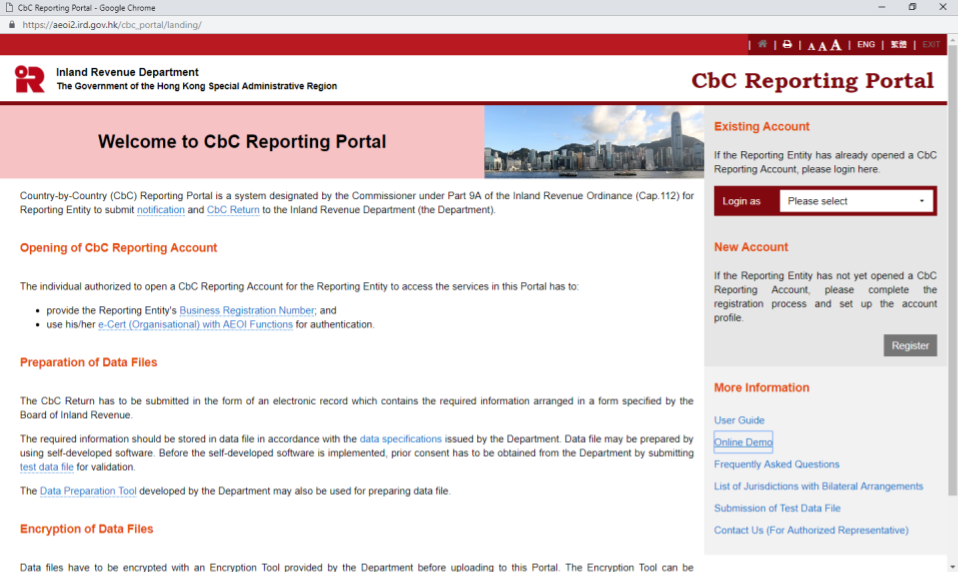
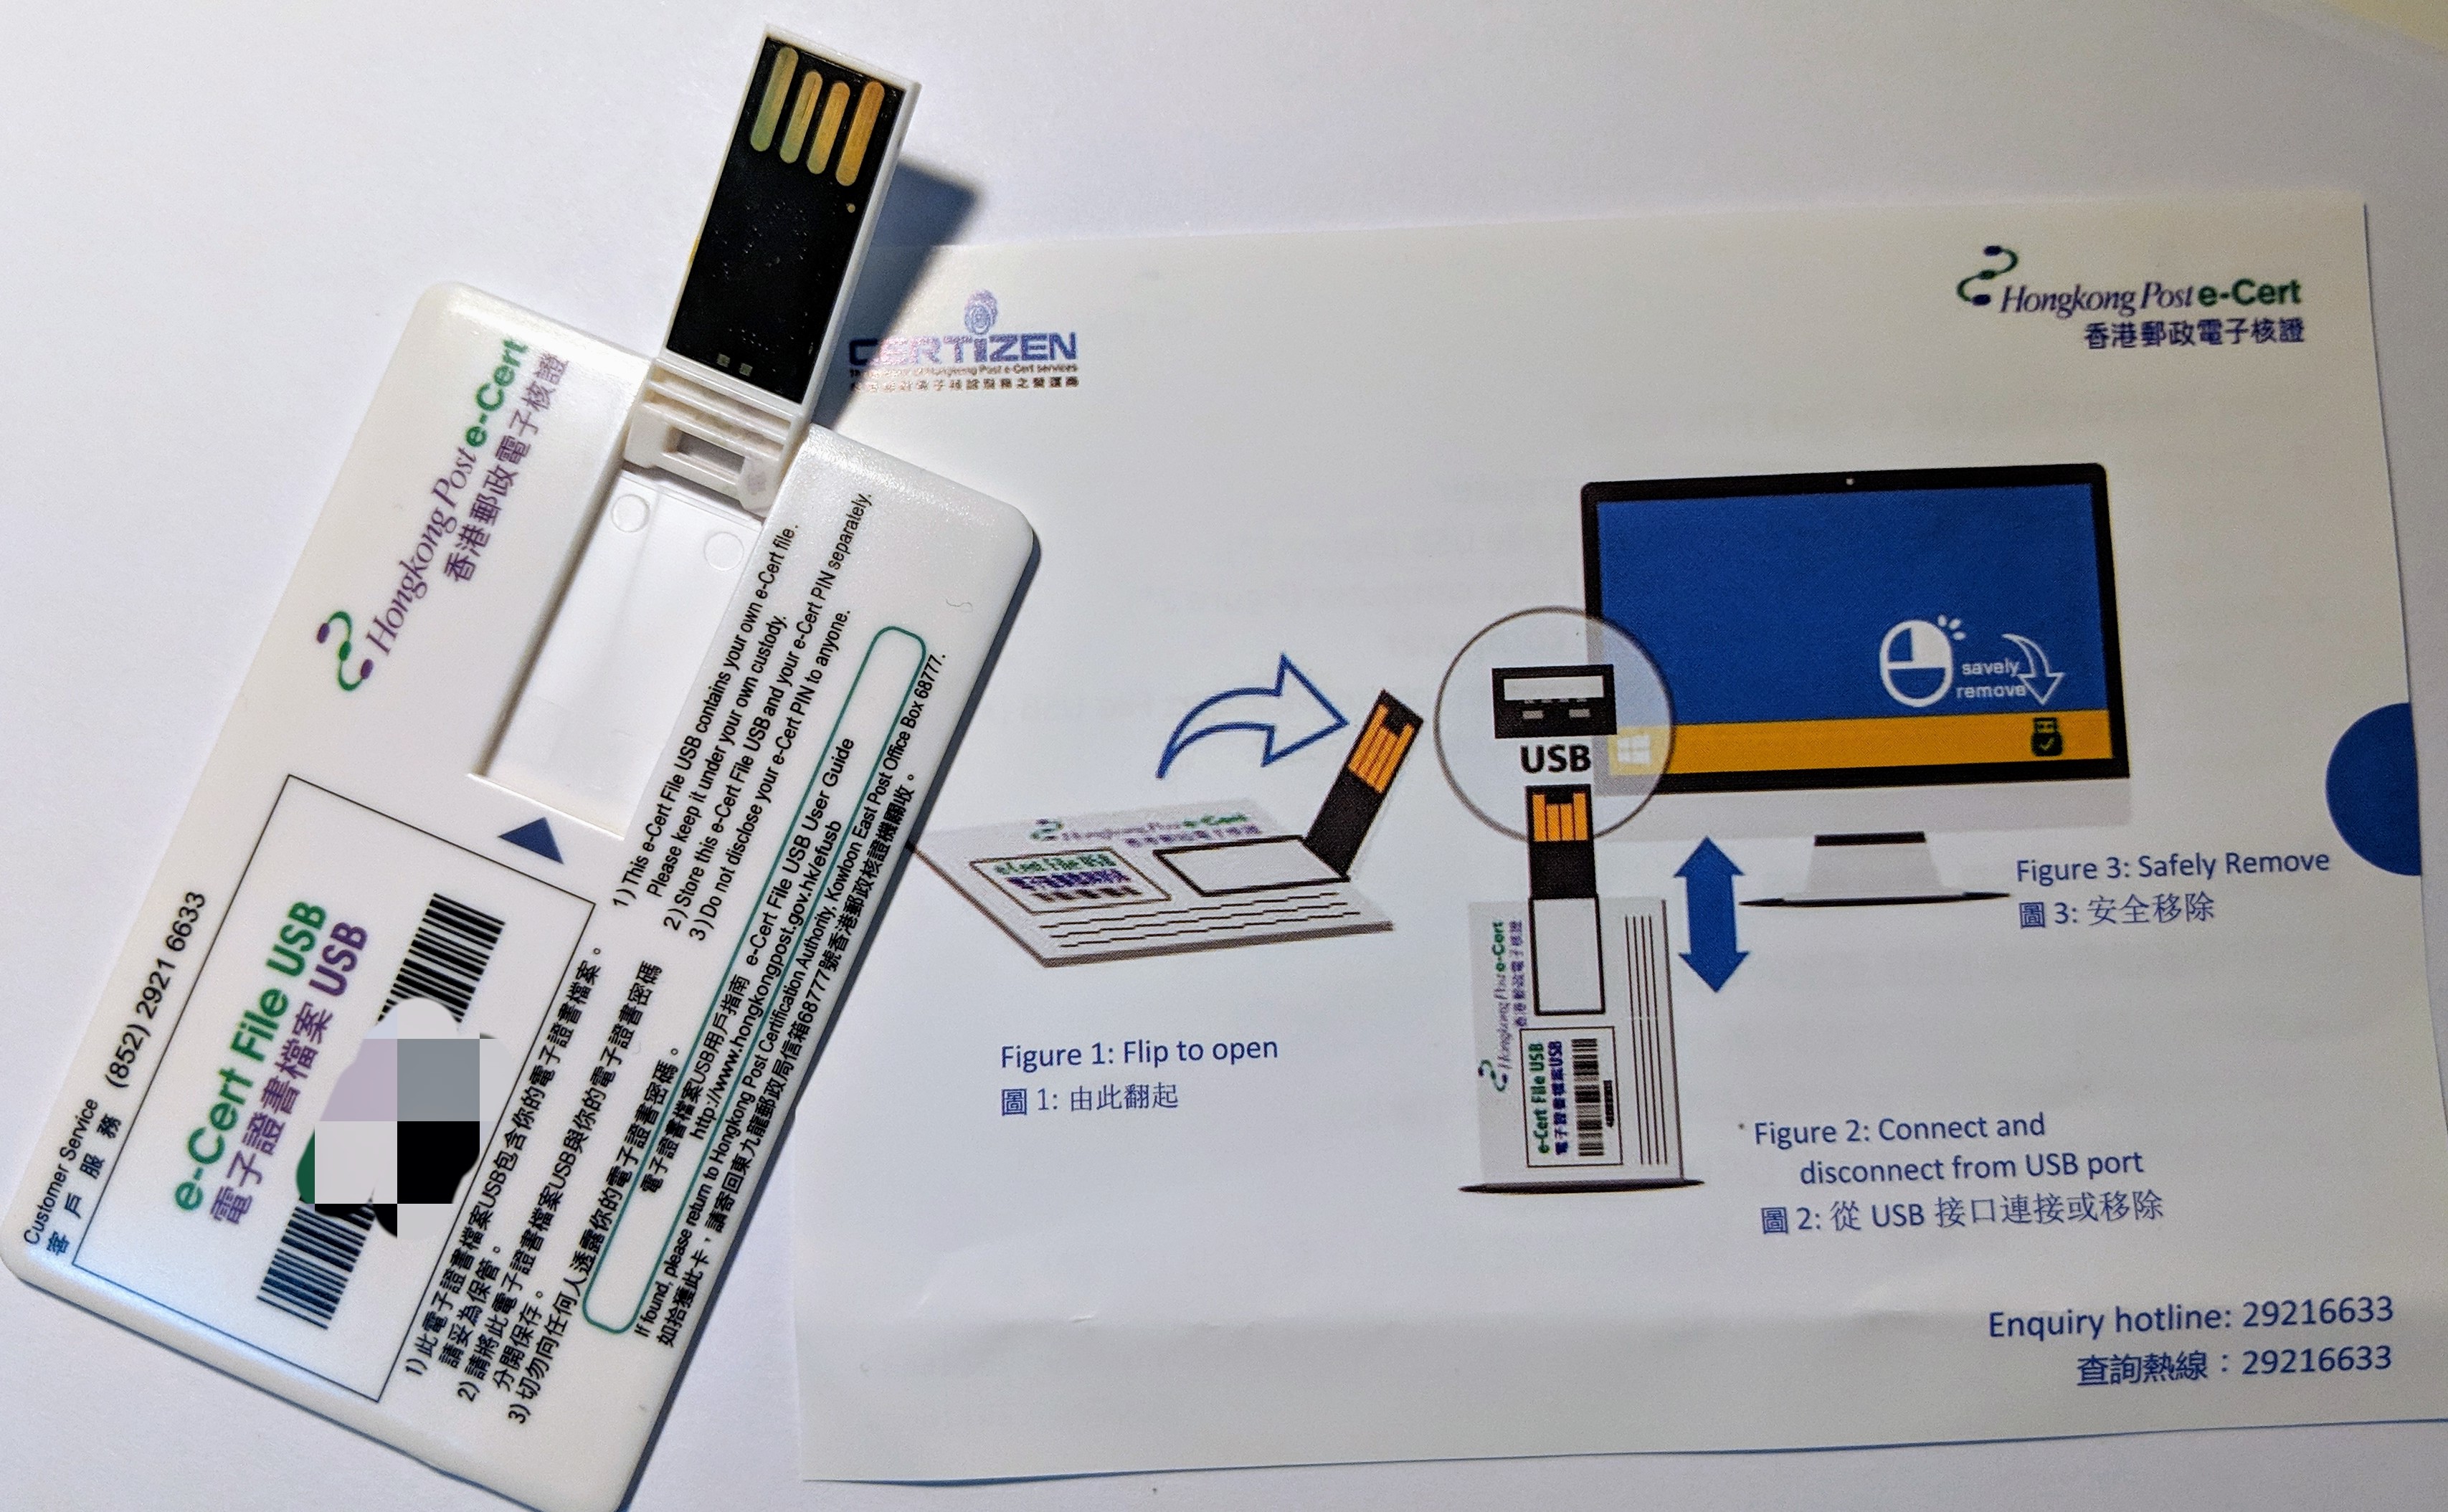
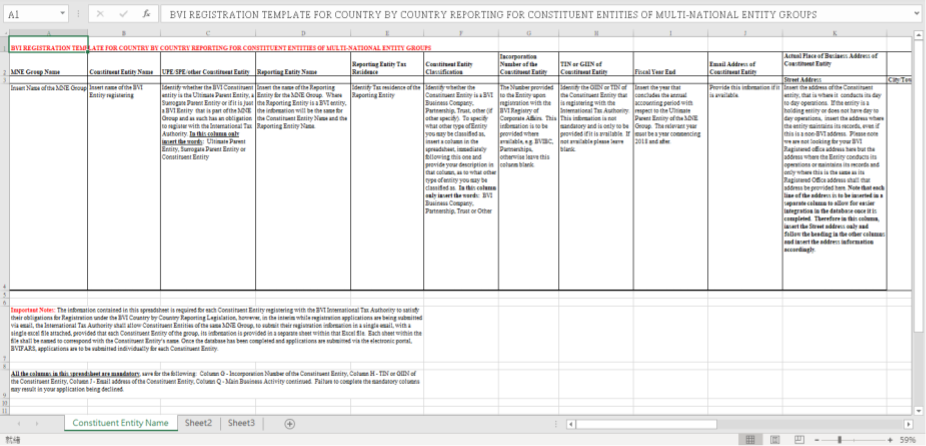
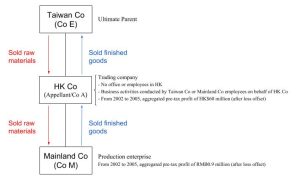
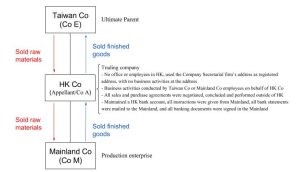
 A small sidetrack before we continue. The example of interest-bearing loans in the last issue of Tax Tips [see attached diagram] is, in fact, Case 1.1 of the BEPS Action 2, “Neutralising the Effects of Hybrid Mismatch Arrangements”. In Action 2, OECD proposed that country B should not allow interest deduction. If Country B allows the interest expense deduction, Country A should regard the income as taxable income in order to “ensure coherence of domestic laws and regulations on cross-border transactions”. In short, OECD is asking jurisdictions to amend the tax code. Logically, Country A and Country B themselves must determine their own tax treatment according to their laws and may be tax cases (where applicable). The laws, regulations and tax cases must have been formulated by history, circumstances and people’s empowerment of the respective countries. Large and small enterprises are only acting according to the laws and regulations. Going forward, would all jurisdictions determine their tax treatments based on how the other countries rule?