manageyourtax.com

Category: Economic Substance

  • Tax Tips (22) – Dealing with International Tax Cooperation

    Tax Tips (22) – Dealing with International Tax Cooperation

    A multilateral tax cooperation mechanism under the Belt and Road Initiative (BRI), the Belt and Road Initiative Tax Administration Mechanism (BRITACOM) which includes tax authorities from 34 countries and regions, was established on 18 April 2019. The reported aim of BRITACOM is to facilitate cross-border trade and investment along BRI routes by expanding tax dispute resolution activities, increasing transparency, streamlining compliance and digitizing filing.  An office will be opened in Beijing to help facilitate these goals.

    Since the BRI consists primarily of Chinese outbound investment in infrastructure projects in the participating countries, BRITACOM will likely function more in facilitating outbound Mainland Chinese entities’ local tax compliance and dispute resolution when engaged in such projects. BRITACOM will be different from the various anti-tax avoidance initiatives of the OECD and other international organisations.

    International Effort in Anti-Tax Avoidance

    The most well-known international effort against tax avoidance is the Base Erosion and Profit Shifting (BEPS) project. The 15 BEPS Actions issued in October 2015 challenge tax avoidance practices by large Multinational Enterprises (“L-MNEs”) by amending the global tax treaties, increasing disclosure and transparency, introducing new documentation in transfer pricing, countering harmful tax practices, lowering threshold of permanent establishment recognition, investigating into new form of taxation for digital services and toughening interest deduction rules. The primary aim of BEPS is to ensure that the international tax rules do not facilitate the shifting of corporate profits away from the real economic activity and value creation are taking place. Many of these Actions have been implemented already, the latest being the Economic Substance Law (with the BVI just issued the Draft Economic Substance Code).

    In addition, the OECD has stepped up efforts in international cooperation on tax matters in recent years. Heads of tax administrations meet regularly at the Forum of Tax Administration (FTA). Cross-border tax avoidance intelligence is shared among tax offices under the Joint International Taskforce on Shared Intelligence and Collaboration (JITSIC). The International Compliance Assurance Programme (ICAP) invites large MNEs to engage voluntarily with tax administrations from 17 jurisdictions (expanded from 8 when the pilot began in January 2018). Tax Inspectors Without Borders sends experience tax officials to train those in developing countries to perform tax audits on MNEs.

    The United Nation, the World Bank, the International Monetary Fund, and the European Unions are also very active in introducing new initiatives in combating tax avoidance.

    Large MNEs have Acted

    Many L-MNEs have already started restructuring back in around 2013/14 in view of the disclosure requirements especially the Country-by-Country Reporting (CbCR). In the past, many L-MNEs housed the intellectual properties (“IP”) in tax haven jurisdictions earning untaxed royalties or have captive insurance companies there to provide insurance coverage to group companies in order to receive untaxed income while the group companies could take a tax deduction. Smart L-MNEs would have restructured early so that no tax office would have the opportunity to ask the sensitive questions. Their most immediate challenge to the L-MNEs would likely be dealing with the economic substance law in the tax haven countries, especially those that have been acting as funding vehicles.

    Smaller MNEs – Act Now

    L-MNEs have internal tax resources to help them manage tax risks in this rapidly changing tax environment. What about the Small and Medium Size MNEs (S-MNEs) that do not have in-house tax people? They obviously have to rely on external tax consultants. The key is to identify the right consultants to do the following two things:

    1. Review the existing structure, operations and arrangements

    The objective of such review is to identify tax risks and opportunities currently embedded in the group structure and operations. The author had seen a group missing out the 50/50 offshore claim in the Hong Kong profits tax filing on a contract manufacturing arrangement. In another case, a Hong Kong-based listed group devoted resources in Hong Kong to help the overseas affiliates in high tax countries to become highly profitable but they do not realise that they should recoup the costs incurred in Hong Kong via transfer pricing in order to align with the commercial reality and reduce the group’s effective tax rate. These can be dug out and properly addressed in order to create legitimate tax saving.

    Some groups have not paid attention to documentation of decision making and thereby creating risks of being regarded as tax resident in jurisdictions unexpectedly. The old model of cost-plus remuneration of agents may now be exposed to permanent establishment risks. Some have ignored the documentation of substance. The impact of the Economic Substance Law introduced by the tax havens such as the British Virgin Islands (BVI) must be properly analysed with a set of action determined to address the issue.

    To be a good manager, issues should be addressed and resolved upfront so that the expectation of shareholders and directors of the group/company is well-managed. The review should be conducted by professionals with solid technical and business experience. There are well-qualified tax advisors in the market to do the work at competitive rates and high efficiency to deliver substantial value to the groups.

    Often the finance managers of the groups/companies prefer to stick their heads into the sand instead of dealing with the problems because they don’t want to take the blame for issues uncovered by the seasoned tax advisors. It is thus important for the directors or even the shareholders to realise what the current tax environment is like and take initiative in carrying out the review. At the end of the day, if the hidden tax exposures are not cleared before they crystalise, the group/company, the directors and shareholders would be badly hurt.

    2. Seek on-going tax support especially on documentation

    Having identified and dealt with past issues, it is important that no such issue will arise again in the future. This can be achieved by retaining the tax advisor to review transactions or documentation as and when required, just a family doctor caring for the health of the family. For example, sometimes the auditors, being unaware of the tax exposure created, may make disclosures in the audited financial statements that are unnecessary and sometimes even harmful to the tax arrangement of the company. For listed companies, they should be very careful in the disclosures in the annual reports.

    Board papers are crucial. It is direct evidence of management and control which is one of the key factors in determining substance and tax residency. Tax advisors play an important role in advising who should be on the board of each company, location of board meetings and review the board papers.

    Also, management should be made aware of tax law changes and new cases that affect their business. Questions they should ask, or proactively addressed by the tax advisor, include:

    • What are the benefits of the new tax incentives introduced in Hong Kong such as the two-tier tax system to the group?
    • Should something be done about intellectual property in view of the new Section 15F of the Inland Revenue Ordinance?
    • What should the group do in view of the Beneficial Ownership rules in Mainland China to ensure that the benefits can be obtained?
    • Is CbCR going to affect the group?
    • The boss travels to Mainland China often, is he exposed to the Chinese Individual Income Tax on worldwide income?
    • Is the loan financing of a foreign subsidiary compliant with transfer pricing or will it be challenged by the tax authorities?
    • In view of the tax cases, can the Hong Kong company still lodge an offshore claim on its trading profits? How to ensure a successful claim?
    • How to structure a new acquisition? Is the Multilateral Convention to Implement Tax Treaty Related Measures to Prevent BEPS (commonly referred to as the Multilateral Instrument) going to affect the group? Would all the new tax rules introduced bring higher tax exposures in a share deal and how to mitigate such risks?

    The list of questions can be much longer.

    Tax Tips

    It is time for the smaller groups to gear up the tax risk monitoring and compliance, and ensure that structures are sustainable in the medium term. The BEPS Project is at the implementation stage and it will not be long before OECD reviews the achievement and point to the next target: the S-MNE groups. The time to act is NOW.


    Contact Us


    Ref:

    BRITACOM: http://www.chinatax.gov.cn/eng/n2367751/c4273658/content.html
  • Tax Tips (19) – Ready to Hire Employees in the BVI?

    BVI employee

    The last issue of Tax Tips (The Final Days of Tax Havens – 10 December 2018) discussed the paper “Resumption of Application of Substantial Activities Factor to No or Only Nominal Tax Jurisdictions” (the “Paper”) issued by the OECD Inclusive Framework on BEPS Action 5, and forewarned the changes ahead: tax haven companies will be required by law to hire an adequate number of full-time qualified employees and incur an adequate amount of operating expenditure to carry out the activities that they claim to be engaged in.

    Tax Havens including the well-known Cayman Islands and the British Virgin Islands (BVI) have swiftly introduced economic substance legislation.  Cayman Islands passed The International Tax Co-operation (Economic Substance) Law, 2018 on 17 December and the BVI’s Economic Substance (Companies and Limited Partnerships) Act, 2018 was passed into law on 19 December 2018.  These laws have become effective on 1 January 2019.

    The rush to pass these laws before the end of 2018 was due to the commitment made to the European Union (EU).  The Cayman Islands and BVI, together with countries such as Bermuda, Guernsey, Jersey and Isle of Man were included in a list of countries whose tax policies and economic substance caused concern for the EU Code of Conduct Group (Business Taxation).  These countries were given the deadline of 31 December 2018 to introduce laws (the “Economic Substance Law” hereinafter) to avoid blacklisting by the EU.

    Economic Substance Law

    The economic substance required by the EU is basically identical to those set out in the Paper.  Although the Economic Substance Laws have been passed, the Tax Havens still need to wait for the EU to confirm that the EU requirements have been met.  However, from the reports on the visit by the OECD representatives (including the Director of the Centre for Tax Policy and Administration Mr. Pascal Saint-Aman) to the Cayman Islands in early January 2019, it seems that things are on the right track.  Although the legislation introduced by different countries are broadly similar, details are different and Readers using Tax Haven vehicles should study the specific legislation to analyse the impact.

    Impact Assessment

    Not all Tax Haven entities will be affected.   Here are the general steps one could take to assess if a company shall comply.

    Step 1: Is the company a “Relevant Entity”

    The Economic Substance Laws generally apply only to entities that are not tax residents outside of the Tax Haven country (the Relevant Entities).  For example, if a BVI company is registered to carry on business in Hong Kong, it will likely be regarded a tax resident in Hong Kong and thus out of scope for the BVI Economic Substance Law.

    Step 2: Is the Relevant Entity conducting the “Relevant Activities”

    Corporates and individuals use Tax Haven entities for various activities but only the “Relevant Activities” are subject to the substance requirements.  Generally, the geographically mobile activities such as the provision of intangibles (i.e., intellectual property (“IP”) related activities) and the below Non-IP activities would be considered the Relevant Activities:

    • Headquarters
    • Distribution centres
    • Service centres
    • Financing
    • Leasing
    • Fund management
    • Banking
    • Insurance
    • Shipping
    • Equity holding

    Relevant Entities will likely be required to file notices to inform the authorities whether they are conducting Relevant Activities or not.  Those conducting Relevant Activities will then need to provide information covering items such as income, expenses, assets, premises, management, employees and physical presence.  If the economic substance of the Relevant Entity falls short of the requirements, it will be asked to make an improvement. Persistent failure to fulfil the substance requirement may be subject to fines and even result in being struck-off.

    Step 3: Meeting the Economic Substance Requirement

    In general, a Relevant Entity conducting any of the above Relevant Activities complies with the economic substance requirements if:

    (a) the Relevant Activity is directed and managed locally (i.e. in the Tax Haven);

    (b) having regard to the nature and scale of the relevant activity:

    1. there are an adequate number of suitably qualified employees in relation to that activity who are physically present locally;
    2. there is adequate expenditure incurred locally;
    3. there are physical offices or premises as may be appropriate for the core income-generating activities; and
    4. where the Relevant Activity is IP business and requires the use of specific equipment, that equipment is located locally; and

    (c) the Relevant Entity conducts core income-generating activity.

    A pure equity holding entity, which carries on no Relevant Activity other than holding equity participations in other entities and earning dividends and capital gains, are subject to the reduced requirement and would be considered to have adequate substance if it:

    (a) complies with its statutory obligations under the relevant company laws; and
    (b) has adequate employees and premises for holding equitable interests or shares and, where it manages those equitable interests or shares, has adequate employees and premises for carrying out that management.

    On the other hand, more stringent rules apply to high-risk intellectual property holding companies.

    As to what is “adequate”, one has to wait for the details to be announced by each country.  The Mauritius example mentioned in Tax Tips (18) would give some indications of what is to come.

    Outsourcing of Core Income Generating Activities

    The economic substance requirements generally allow for outsourcing of the core income generating activities to third-party within the jurisdiction. The Relevant Entity must, however, be able to prove that it is able to monitor and control the core income generating activities being carried out are conducted locally.

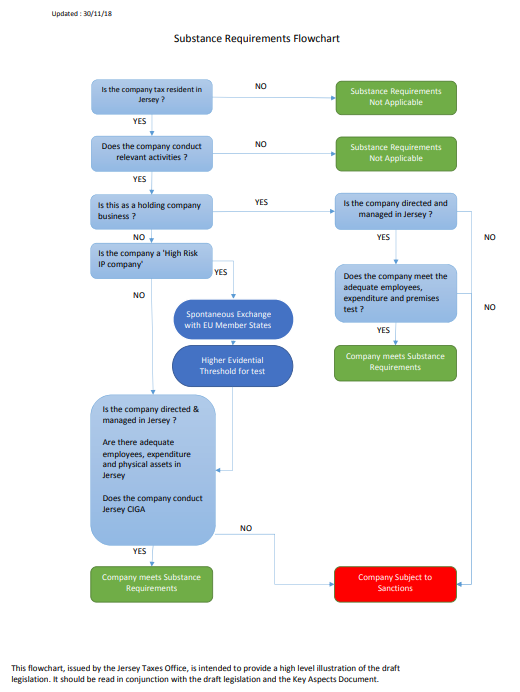
    The below flowchart downloaded from the Jersey Government website is a good reference on how the laws work in general.

    No-where Income  

    The Common Reporting Standard (CRS) and Economic Substance Laws are bringing tax residencies of companies and individuals into the limelight.  Hong Kong businesses are faced with questions from their bankers that ask them to identify the tax residency of their Tax Haven companies which have bank accounts in Hong Kong.  Thanks to creative tax planning advice Hong Kong businesses acted on in the past, many of them use the bank accounts in the following situations:

    • There is a group company in Mainland China manufacturing goods for domestic sales.  Orders of overseas customers are accepted in China and are shipped out without export declaration.  The overseas customers pay to the Hong Kong bank account of the group BVI company, and some of the cash received would be used to pay Hong Kong suppliers who provide the raw materials in China.  These sales and purchases would not be booked by the manufacturer in China.
    • Services are provided in Hong Kong or China to overseas clients and they are asked to pay to the Hong Kong bank account of a BVI company.  Income is booked in the BVI company while the costs of services are incurred in Hong Kong or China with tax deduction allowed unchallenged.
    • IPs such as brands, trademarks, designs, rights etc are owned by BVI companies and earning hefty royalty income from group companies or unrelated parties, while the work related to the development, exploitation, maintenance, protection and enhancement of the IPs are carried out in Hong Kong, and the costs of such activities have been fully tax-deducted.

    In the above examples, there would be under-reporting of income as profits have been shifted to entities that do not carry out value-creation activities.  Once the tax offices in Hong Kong or China have become aware of the situations (which has become more likely these days with all the reporting and information exchange arrangements), they may, for example, treat the BVI companies as carrying on business in Hong Kong or managed and controlled in China, as the case may be, and assess tax on the under-reported amount and impose heavy penalties.  On the other hand, from now on the groups in question also need to maintain substance of these BVI companies in the BVI or they risk the companies being struck-off. Things will become more complicated if the shareholders of the companies become Chinese tax residents by spending 183 days or more in China in a calendar year.

    Tax Tips

    As mentioned in Tax Tips (1), “Base Erosion and Profit Shifting” (BEPS) refers to the tax planning strategy of multinational groups (big or small) making use of differences and mismatches of tax rules across different countries and artificially transferring profits to low or no-tax jurisdictions with little or no economic activity.  The pressure now felt by taxpayers is indeed the intended effect of OECD’s project against BEPS. At the same time, the compliance costs of Tax Haven entities are rising. Taxpayers should take action to restructure their operations and shift profits back to where the activities are. There will be an increase in tax burden, but a managed transition would help minimise the tax costs and avoid heavy penalties: tax offices like to punish aggressive taxpayers with the highest penalties.


    Contact Us


    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 24 January 2019: https://manageyourtax.com/HKEJ Forum 19)

    Ref:

    The Paper: http://www.oecd.org/tax/beps/resumption-of-application-of-substantial-activities-factor.pdf

    Members of the Inclusive Framework on BEPS: http://www.oecd.org/tax/beps/inclusive-framework-on-beps-composition.pdf   

    BVI Economic Substance Law:

    https://eservices.gov.vg/gazette/sites/eservices.gov.vg.gazette/files/newattachments/Act%20No%2012%20–%20Economic%20Substance%20%28Companies%20and%20Limited%20Partnerships%29%20Act%202018-%20Revised%2017%2012%202018%20%28clean%29%20%281%29_0.pdf

    EU Listing:

    http://data.consilium.europa.eu/doc/document/ST-9637-2018-INIT/en/pdf

    OECD visit to the Cayman Islands:

    http://www.caymanfinance.gov.ky/portal/page/portal/pruhome/pressroom/2019/oecd-tax-policy-representatives-visit-cayman?fbclid=IwAR1QkTcf0gRS4dbBLEbba2lg0K8k9_AQhGUhI-n1xObKUeOGrl8P6P_GVH4

    Bermuda Economic Substance Act:

    http://www.royalgazette.com/assets/pdf/RG3964221217.pdf


  • Tax Tips (18) – The Final Days of Tax Haven

    What would you do if every tax haven (e.g. BVI) company under your control is required by law to hire full-time qualified employees there and incur an adequate amount of operating expenditure to carry out the activities that they claim to be engaged in?


    Harmful tax practice
    BEPS Action in action

    In Tax Tips (13), the issue of tax residency of tax haven companies was discussed.  Smart corporates will be able to ensure that the tax residencies of their tax haven entities are properly managed and thus would not create tax exposures.  That does not necessarily mean that these companies can continue to book un-taxed profits with no substance. The BEPS machine is not stopping.

    Substance

    Last month, the OECD Inclusive Framework on BEPS: Action 5 issued a paper called “Resumption of Application of Substantial Activities Factor to No or Only Nominal Tax Jurisdictions” (the “Paper”), which sets out the substance requirements for tax havens.  To the tax havens around the world, this Paper could be the last straw on the camel’s back (incidentally, tax havens such as the BVI, Cayman Islands etc are members of the Inclusive Framework).

    Background

    The OECD issued the report “Harmful Tax Competition: An Emerging Global Issue” in 1998 (“the 1998 Report”) setting out a framework for approaching the perceived problem that certain no or only nominal tax jurisdictions (i.e., tax havens) and harmful preferential tax regimes “affect the location of financial and other service activities, erode the tax bases of other countries, distort trade and investment patterns and undermine the fairness, neutrality and broad social acceptance of tax systems”.  The 1998 Report called this “harmful tax practices,” and built a framework to assess these practices.  The aim was to deliver a level playing field between jurisdictions in a context where taxpayers can easily relocate their mobile activities in response to tax considerations.

    The framework for assessing whether a jurisdiction is a tax haven is based on four criteria:

    (a) whether a jurisdiction imposes no or only nominal taxes;

    (b) lack of effective exchange of information;

    (c) lack of transparency and

    (d) the absence of a requirement that the activity be substantial.

    Notwithstanding, in 2001 the Forum on Harmful Tax Practice decided to only determine whether or not a jurisdiction was considered uncooperative on the basis of the first three criteria, and focused on making them cooperative and transparent.

    With the implementation of BEPS Action 5 and the peer review process to ensure tax breaks are only offered to substantive activities and only if they do not pose risks of harmful competition to others, the focus is now shifted to ensure that business activity does not simply relocate to tax haven in order to avoid the substance requirements.  Against this background, the Inclusive Framework has decided to apply the Substantial Activities Requirements for tax havens.

    The Scope of the Substantial Activities Requirements

    The types of activities that are within the scope of the Substantial Activities Requirements are geographically mobile activities such as the provision of intangibles (i.e., intellectual property (“IP”) related activities) and Non-IP activities which includes headquarters, distribution centres, service centres, financing, leasing, fund management, banking, insurance, shipping and holding companies.

    What are the Substantial Activities Requirements

    Non-IP-Related

    For income from income not related to IP (“Non-IP Income), tax havens would be required to introduce laws to:

    (i) define the core income generating activities for each relevant business sector;

    (ii) ensure that the activities are undertaken by the entity (or are undertaken in the jurisdiction);

    (iii) require the entity to have an adequate number of full-time employees with necessary qualifications and incurring an adequate amount of operating expenditures to undertake such activities; and

    (iv) have a transparent mechanism to ensure compliance and provide an effective enforcement mechanism of the laws.

    IP-Related

    For income related to IP (“IP Income) derived from patents or similar assets, the core income generating activities would be the conducting of research and development activities with an adequate number of qualified full-time employees and adequate amount of operating expenditures.  A similar requirement would apply where an entity is exploiting marketing IP assets such as trademarks, where the core income generating activities are branding, marketing, and distribution.

    In other cases of IP Income, the entity would need to demonstrate that it is conducting strategic decision making, managing and bearing the principal risks relating to the development and subsequent exploitation of the IP asset, or carrying on the underlying trading activities through which the asset is exploited, with the adequate number of qualified full-time employees and an adequate amount of operating expenditures.  

    IP Income – Higher risk scenarios

    Higher risk scenarios would be cases that involve related parties outside of the tax haven where (i) the entity has acquired the IP asset from related parties or through the entity funding research and development activities which took place outside the tax haven; and (ii) the IP asset is licensed or sold to related parties, or the exploitation is conducted by related parties outside the tax haven (e.g. foreign related parties are paid to develop and sell a product in which the intangible asset is embedded).

    An entity in a higher risk scenario could meet the substantial activities requirements by providing evidence that there was, and historically has been, a high degree of control over the development, exploitation, maintenance, enhancement and protection (the DEMPE functions) of the intangible asset, exercised by an adequate number of full-time employees with the necessary qualifications that permanently reside and perform their activities in the tax haven. This would need to be demonstrated by providing additional information including:

    • detailed business plans which demonstrate the commercial rationale for holding the IP assets in the jurisdiction;
    • employee information, including the level of experience, type of contracts, qualifications,
      and duration of employment; and
    • evidence that decision making is taking place within the jurisdiction, rather than
      periodic decisions of non-resident board members.

    Ensuring Compliance

    To ensure compliance, tax havens would need to:

    1. Set up a mechanism to collect various information from entities including details of the core income generating activities, the amount and type of gross income and expenses, the assets and premises held in the course of carrying out the business, and the number of full-time, qualified employees.
    2. Set up a sanction mechanism that is rigorous, effective and dissuasive to take action in the event an entity failed to meet the substantial activities requirements. Sanction mechanism could include striking an entity off the register. The tax havens would also need to continue enforcement efforts and remedy any shortcomings in the enforcement process.
    3. For any entities that do not comply with the substantial activities requirements, tax havens would be required to spontaneously exchange all relevant information with the jurisdictions of residence of the immediate parent, ultimate parent, and ultimate beneficial owner.

    The effectiveness of the information collection and exchange mechanism is to be reviewed in 2022.  

    What about Holding Companies?

    As discussed in Tax Tips (13), tax haven company is the ideal type of vehicle for investment holding, i.e. holding equity participations and earn only dividends and capital gains.  Such companies are recognised in BEPS Action 5 that they may not require much substance in order to exercise their main activity of holding and managing equity participations, and therefore is less of a concern from BEPS’ perspective.  The Substantial Activities Requirements on investment holding companies are that they respect all applicable corporate law filing requirements and have the substance necessary to engage in holding and managing equity participation (for example, by showing that they have both people and the premises necessary for these activities).   

    The Mauritius Example

    Mauritius imposes nominal tax on companies with Category 1 Global Business Licence (“Cat 1 GBL”, commonly used as holding companies with access to the Mauritius tax treaty network).  In the recent months, the Mauritius authorities issued new rules to bring about changes with effect from 1 January 2019. Under the new rules, Cat 1 GBL will be replaced by a new licence called Global Business Corporation (“GBC”) and the licensing conditions for GBC include, inter alia, carrying out of its core income generating activities at all times in, or from, Mauritius by:

    • Employing, either directly or indirectly, a reasonable number of suitably qualified persons to carry out the core activities; and
    • Having a minimum level of expenditure, which is proportionate to its level of activities.

    In addition, the regulations provided the indicative core income generating activities and the minimum annual expenditure and employees (direct or indirect).  For an investment holding GBC, the indicative minimum annual expenditure is USD12,000 and there is no minimum employee specified.

    The Mauritius rules could be an example of what is forthcoming in other tax havens.

    Tax Tips

    Subject to the actual regulations to be introduced by the tax havens, the requirement that the entities in tax havens should maintain “an adequate number of qualified full-time employees and adequate amount of operating expenditures” and the threat of information exchange is likely sufficient to kill most tax haven entities earning IP or Non-IP Income (except for investment holding companies).  Corporates that have not already restructured the activities to “normal tax jurisdictions” should speed up their review process and take action.

    As to investment holding, which probably is a major business activity of most tax havens, corporates should follow the development closely and react to that accordingly.  It is foreseeable that the OECD may accept more lenient substance requirements in order not to hurt the economies of the tax havens too significantly. The introduction of requirements on annual minimum expenditure even full-time employees will reduce the attractiveness of tax haven.  As these are real additional costs of setting up investment holding companies, corporates should consider consolidating the group holding structures to eliminate duplicated costs, if not pulling out completely. The days of letterbox and brass plate companies appear to be limited.


    Contact Us


    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on 10 December 2018: https://manageyourtax.com/HKEJ-Forum-18)

    REF:

    The Paper: http://www.oecd.org/tax/beps/resumption-of-application-of-substantial-activities-factor.pdf

    Members of the Inclusive Framework on BEPS: http://www.oecd.org/tax/beps/inclusive-framework-on-beps-composition.pdf   

    Mauritius Circular CL1-121018: https://www.fscmauritius.org/media/67458/cl-on-substance-gb.pdf