manageyourtax.com

Tag: #TerritorialConceptOfTaxation

  • Tax Tips (6) – Territorial Concept x Transfer Pricing

    The Inland Revenue (Amendment) (No. 6) Bill 2017 (the “Bill”) that was discussed in Tax Tips (2) and (3) proposed to introduce Part 8AA – Transfer Pricing Rules to the Inland Revenue Ordinance.  Transfer Pricing rules require transactions with associated enterprises be conducted under the Arm’s Length Principle.  Section 50AAD(1) of Part 8AA reads: “This Part applies in determining a person’s liability for property tax, salaries tax and profits tax”.  Putting aside Property Tax and Salaries Tax (the Author does not think that it is appropriate to extend transfer pricing regulations to Salaries Tax), the Author’s interpretation of this Section is that “when a person is liable to Profits Tax, Part 8AA operates to determine the extent of the liability”.  Whether a person is liable to Profits Tax, one shall mainly refer to Section 14(1) of the Inland Revenue Ordinance, which says:

    Subject to the provisions of this Ordinance, profits tax shall be charged for each year of assessment at the standard rate on every person carrying on a trade, profession or business in Hong Kong in respect of his assessable profits arising in or derived from Hong Kong for that year from such trade, profession or business (excluding profits arising from the sale of capital assets) as ascertained in accordance with this Part.

    If the profits of a connected transaction are derived from outside Hong Kong and not subject to Profits Tax under Section 14(1), the Hong Kong taxpayer should be regarded as “not liable to profits tax” and thus Section 50AAD(1) of Part 8AA would not be applicable.  Even if the Hong Kong taxpayer has substantive business and operating activities in Hong Kong, as long as the profits of the connected transactions are derived from outside Hong Kong, the Inland Revenue Department (“IRD”) should not impose Profits Tax on the profits attributable to the risks assumed and functions carried out in Hong Kong. This is the correct treatment because if the substantive business activities carried out by non-associated enterprises would not be subject to Profits Tax, the same activities carried out by associated enterprises should not be treated differently.  This principle has been mentioned in Paragraph 71 of the Departmental Interpretation and Practice Notes No. 46 – Transfer Pricing Guidelines – Methodologies and Related Issues (December 2009) (“DIPN 46”).  In theory, the principle of territorial-based taxation is maintained.

    Connected Transactions in D25/14

    In the last issue of Tax Tips, the Inland Revenue Board of Review (“BOR”) Decision for Case D25/14 (published in February 2016 Volume 30 First Supplement) was discussed.  Although the matter in dispute was not related to transfer pricing, as the case involved both the source of profits and transfer pricing, it can be used to discuss this topic: if Part 8AA Section 50AAD(1) was already the law, how would it apply to the case? [Please refer to Tax Tips (5) for the background of the case]

    Case Appellant Company A (“Co A, a Hong Kong company) had no employee and asset in Hong Kong, all contracts were entered into and performed outside Hong Kong, but the BOR determined that regardless of the whereabouts of the controlling staff and the places where the contract was entered into and performed, the trading between Taiwan Co and Mainland Co would have been impossible in the absence of the Appellant as the “middleman”.  The activity of playing such role was obviously in Hong Kong.  The BOR rejected the Appellant’s argument that “the profits were not arising in or derived from Hong Kong”, and confirmed that the profits of Co A were fully subject to Profits Tax.  Assuming Part 8AA has been implemented, given that Co A’s transaction was definitely a connected transaction and has been ruled by the BOR to be liable to Profits Tax, how would the IRD “determine the extent of such liability?”

    Under normal circumstances, “to determine the extent of such liability”, one basically assumes Co A was not an associated company of Taiwan Co and Mainland Co, and based on Co A’s functions, risks, government policies etc., search for comparable companies in the market, select the appropriate transfer pricing method to determine whether Co A’s profit is lower than those earned by comparable companies under the Arm’s Length Principle.  If it is determined to be lower than the arm’s length profits, the IRD may adjust the assessable profits upward and assess Profits Tax.  Although Co A’s case did not disclose the functions performed and risks assumed by each of the affiliated companies, it can be reasonably assumed that most of the risks were borne by Taiwan Co, such as bad debts, cargo insurance, foreign exchange risks etc.  The three companies each had their own functions, but Co A did not have employee and asset so it could only have performed limited functions.  In addition, as Co A only served as an intermediary for the entire transaction, if the Taiwan Co did not own Co A, but rather traded with the mainland manufacturer through an independent, non-affiliated Hong Kong company (call it “Co X”), it would be likely that a lot of genuine Hong Kong trading companies would be happy to take up the middleman role for a relatively lower return for the limited risks it would bear.  This “middleman” role, which was regarded as extremely important by the IRD and the BOR, would not seem to be very valuable from transfer pricing perspective.
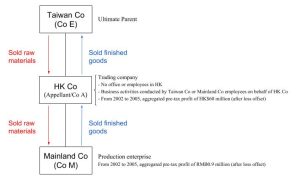
    The Author suspects that the entire planning behind Co A was that Co A was expected to be successful in Hong Kong Profits Tax exemption on the basis that the profits were sourced from outside Hong Kong, thus it is likely that Co A made excessive profits during the years.  According to publicly available information, from 2002 to 2005, Co A’s total sales revenue was HK$237,121,169, with an aggregated pre-tax profit of HK$60,053,849 (after loss offset), resulting in a high net profit margin of 25%!  Would this “very important intermediary role” be entitled to earn such a high profit?  Would the Taiwan Co give more than HK$60 million of profits to the independent, non-affiliated Co X?  As for the Mainland Co, the total profits from 2002 to 2005 was only RMB918,234 (after loss offset)!  It seems that Co A was carefully operated to lower the group’s overall tax burden by making the offshore claim.

    Anti-Avoidance is the Highest Principle?

    The Author also suspects that the IRD was aware of the possible tax avoidance via offshore claim.  As it would be inappropriate to invoke the General Anti-Avoidance provisions under Section 61A of the Inland Revenue Ordinance to tackle this case, the IRD countered such avoidance act by seeking to disallow the Offshore Claim.  As the contracts of sale and purchase of Co A were effected and performed outside Hong Kong, under DIPN 21 as referred to in the last issue of the “Tax Tips” the profits would not be subject to tax in Hong Kong.  In order to win the case, the IRD linked the “extremely important” middleman’s role and functions (which is a concept of transfer pricing) with the source of profits, and succeeded in winning at the cost of overturning DIPN 21.  In the past, the IRD would respect the territorial concept of taxation and would not inquire whether the relevant profits were taxed elsewhere.  However, under the bandwagon of BEPS(1), it seems that anti-avoidance has become the highest principle.  As for the BEPS concept of “allowing companies to pay tax at the location of their real business activities and value creation”, the real idea seems to be that “if no one is claiming tax on profits, I will come forward”.  Therefore, it will become more and more difficult to be granted the offshore treatment in the future (many people would have felt it already in the past few years).  This is particularly worrying as the law and DIPN 21 have remained unamended.

    Finally, would the IRD adjust-down Co A’s assessable profits (assuming the transfer pricing report determines that Co A’s profit is too high) in accordance with the arm’s length principle?  The answer is “No”, not only because the subject matter in question is the source of profit, as a matter of policy, the IRD would simply not proactively adjust-down excessive profits.  Furthermore, unless the tax authorities in the Mainland decided that Co A has constituted a permanent establishment in the Mainland and imposed a 25% corporate income tax on the profits of Co A, there is no double taxation and the IRD can safely pocket the tax revenue. This principle is also illustrated in paragraphs 71 and 72 of DIPN 46.

    (1) See “Tax Tips” (1) and (2)

    Tax Tips: Taxpayers must recognise the general direction and current climate of transfer pricing.  Before making any arrangement, it is important to anticipate that every tax office involved in a transaction wants a share of your profits — tax authorities are increasingly interested in using “Profits Split” to divide the profits of the entire supply chain.  It is conceivable that there will also be disagreements between tax authorities, and taxpayers in Hong Kong may eventually have to ask the IRD to invoke the Mutual Agreement Procedure and Arbitration under the double taxation arrangements to negotiate with the other side (or multiple sides) on who gets to tax which part of your profits.  After lengthy discussions, taxpayers would also have to pay IRD the relevant fees (Section 50AAB introduced in the Bill refers).  It is recommended that taxpayers should immediately review all connected transactions, collect evidence and supporting arguments, determine the most suitable transfer pricing methodologies, and prepare appropriate transfer pricing documentation to meet possible challenges in the future.

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on February 26, 2018: https://manageyourtax.com/HKEJ Forum 6)

    Contact Us

    Author: Edwin Bin

    Ref:

    The Bill: http://www.gld.gov.hk/egazette/pdf/20172152/es32017215229.pdf

    D25/14: http://www.info.gov.hk/bor/tc/docs/D2514.pdf
    DIPN 21: https://www.ird.gov.hk/chi/pdf/c_dipn21.pdf

    DIPN 46: https://www.ird.gov.hk/eng/pdf/e_dipn46.pdf

  • Tax Tips (5) – Does the Territorial Concept of Taxation Still Exist?

    (This is an English translation of the Chinese article published in the Hong Kong Economic Journal Forum on February 9, 2018: https://manageyourtax.com/HKEJ Forum 5).

    Foreword: Bad answers to IRD enquiries can be catastrophic to other taxpayers…

    As mentioned in the previous issue, one of the criteria for a good tax system is fairness, while others include simple and easy to understand, low compliance costs, high transparency and high certainty.  The author started working on Hong Kong tax more than 20 years ago.  At that time, the Hong Kong tax system did meet the requirements of a good tax system.  But is the tax system in Hong Kong still good today?  The speech by the Financial Secretary, Mr Paul Chan, at the “Summit on New Directions for Taxation” in October last year referred to the government’s tax policy direction in recent years and the future prospects.  In the Tax Tips to follow the author will comment based on the Financial Secretary’s speech.

    The Financial Secretary said: “Hong Kong has always followed the simple low-tax system and the territorial concept of taxation. Today it has one of the lowest tax rates in the world in terms of corporations and individuals, making it the world’s premier business location … However, today we are in the 21st century, great changes are happening in the global political and economic arena.  Tax measures have gradually become a means of competition among various economies, attracting investors and supporting industries through this competitive approach.  We are seeing the shortcomings of Hong Kong’s simple and low tax system… “.  This issue discusses the territorial concept of taxation.

    The Territorial Concept of Taxation

    In theory, as long as Section 14(1) of the Inland Revenue Ordinance (“IRO”) is not changed, the Government can still claim that Hong Kong is maintaining the territorial concept of taxation, the problem is whether in practice this concept is still being respected.  One criticism of the Inland Revenue Department (“IRD”) is that the Department no longer respects the territorial concept of taxation.  Taxpayers today are finding out that the same profits with the same offshore source would no longer be considered offshore source by the IRD.  Let us first revisits what Section 14(1) says:

    Subject to the provisions of this Ordinance, profits tax shall be charged for each year of assessment at the standard rate on every person carrying on a trade, profession or business in Hong Kong in respect of his assessable profits arising in or derived from Hong Kong for that year from such trade, profession or business (excluding profits arising from the sale of capital assets) as ascertained in accordance with this Part. (NB: fonts in bold added by the author)

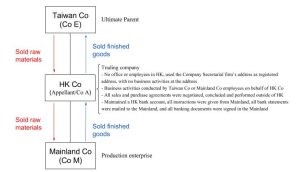
    The Inland Revenue Board of Review (“BOR”) Decision for Case D25/14 (published in February 2016 Volume 30 First Supplement) is an interesting case worth looking at.  The Appellant was a Hong Kong incorporated company (“A Co”/”HK Co”) that acted as the middleman in the trading between Taiwan and the Mainland to circumvent the direct trading restriction (the “Three Direct Links” – Direct Posts, Direct Vessels, Direct Flights) between Taiwan and the Mainland at that time.  The diagram below sets out the relationships and operations of the companies involved.

    Except for the transshipment of raw materials and finished goods through Hong Kong, the following operations are carried out by either the Taiwan Co or employees of the Mainland Co in these two locations: receiving orders from Taiwan Co for purchasing products / contacting Mainland Co for manufacturing / negotiating with Taiwan Co for raw materials purchases / arrange the delivery of raw materials / test the quality of raw materials / test the quality of finished products / issuance of invoices, billing and settlement.  The Appellant’s directors were only involved in the raw materials purchases for the Mainland Co and the activities were carried out in the Mainland.  On the profits tax return, the Appellant claimed that it operated entirely outside Hong Kong and therefore did not have any profit taxable profits or losses that can be set off against profit tax.  The IRD dismissed the claim issued an assessment of profits tax of HK$12.36 million in total for the years of assessment 2002/03 to 2005/06.  After rounds of correspondences, the Appellant failed to convince the IRD and subsequently appealed to the BOR.

    The core issue of this case is the answer to the following three questions:

    (1) Did the Appellant carry on a trade, profession or business in Hong Kong?

    (2) Did the Appellant’s profits that should be assessed come from the trade, profession or business of the Appellant?

    (3) Was the profit arisen in or derived from Hong Kong?

    These three issues are precisely the conditions under Section 14 (1) of the IRD.  All three conditions must be met for profits to be chargeable to Profits Tax.

    What the Appellant said

    The Appellant did not consider it appropriate to determine that a trade, profession or business has been established in Hong Kong solely because it was a limited company incorporated in Hong Kong.  Instead, one should focus on the nature of the activities carried out in Hong Kong and exclude any ancillary activities.  Since the Appellant considered its activities in Hong Kong to be ancillary in nature, the Appellant contended that no business was conducted in Hong Kong, and thus the above first condition was not met.

    With regard to the second condition, the Appellant did not deny that it made profits out of its business, which was conducted outside of Hong Kong. Therefore, the Appellant considered the second condition to be met, for the offshore business activities.

    As for the above conditions for “profits arising in or derived from Hong Kong”, the Appellant did not think Hong Kong should be the source of profits simply because the taxpayer was operating in Hong Kong. In summary, the Appellant argued that the “actual cause” of the trading profits came from the contracts which were entered into and performed outside Hong Kong.  Therefore, the Appellant considered that its profits were not arising in or derived from Hong Kong, and thus the third condition was not met.

    Views of the IRD Representative and Judgement by the BOR

    With regard to Condition 1: whether the Appellant carried on a trade, profession or business in Hong Kong, the Board considered that the Appellant’s operations in Hong Kong was more than ancillary nature and dismissed the Appellant’s statement.  The Board arguments included: A Co acted as the “middleman” and was a true legal entity with specific functions within a Taiwanese corporate group.  It was not a paper company.  A Co prepared financial statements in Hong Kong and has bank accounts in Hong Kong.  The documents of A Co showed that the company’s business address was in Hong Kong. Another important factor is that the customs documents showed that the raw materials and finished goods landed in Hong Kong for transshipment, and the finished goods were consolidated onto a large vessel in Hong Kong for shipping to Taiwan.  A Co clearly intended to ensure that trading activities must be conducted through Hong Kong.  These activities are direct evidence that A Co had an actual and important business.  Without this “middleman”, it would have been virtually impossible for any trade to be conducted under the environment at that time.  Therefore, although A Co’s business activities were not as substantial as other trading companies, it had certain, and indeed very important, business and specific roles.  The IRD representative also pointed out during the hearing that there was no evidence to show that the central management and control of the taxpayer was outside Hong Kong (the information showed that one of the five directors of A Co was a director and supervisor of the Taiwan Co, one served as both the director of Taiwan Co and Mainland Co, the other three were also directors of Mainland Co, with one of them being also the general manager of Mainland Co.  It seems that none of them was managing the business of A Co in Hong Kong).

    In regard to the most crucial question: Whether the profits were arising in or derived from Hong Kong, the IRD representative said: “The business of a company must be carried out in a place where the important activities are carried out, and that place is not necessarily the same place of decision making.  Business can be conducted in Hong Kong with a limited scale of actual activities”.  The representative of the IRD also claimed that “the place where the documents are produced [the author: the negotiation and conclusion of the contracts?] is not important for determining the source of the Appellant’s profits.  The sources of profits shall be determined based on facts, which is a commercial issue rather than technical issue.  In this appeal case, the reality is that the Appellant earned profits by selling goods from a subsidiary in the Mainland to the parent company in Taiwan.  These sales must be routed through Hong Kong.  In fact, the goods were transshipped through Hong Kong.  The antecedent and ancillary activities were carried out in various locations.  The actual reason for the generation of profits is the transshipment activities”.

    The Board opined that in deciding whether the source of profits came from Hong Kong, the place where a contract was entered into and performed was an important factor, but not a decisive one.  In investigating the activities from which the Appellant derived profits, attention must be given to the fact that the activities might not be the trading activities which one conventionally perceived (i.e. the entering into and performance of the contract, etc.).  As Lord Janucey mentioned in the IRC v HK-TVB International Ltd case, “one looks to see what the taxpayer has done to earn the profit in question and where he has done it”.

    The Board pointed out that the Appellant was inserted as a “middleman” to circumvent the trade restrictions in force between the Mainland and Taiwan.  Although the number of activities was not large, it had a necessary role. In other words, regardless of the whereabouts of the controlling staff and the places where the contract was entered into and performed, the trading between Taiwan Co and Mainland Co would become impossible in the absence of the Appellant.  The activity of playing such role was obviously in Hong Kong.  There was no evidence to show that the profits were derived from outside of Hong Kong.

    Lastly, the Board mentioned that according to authorities, the place where a contract was entered into was an important factor in deciding the source of profits, and the mode of trade and destination of the goods shipped might be a factor of less importance; but in light of the trade restriction which was in force at the material period, the former became peripheral and less important, while the latter was an important factor when considering the source of profits.

    The appeal was dismissed.  The author understands that A Co has not lodged a further appeal.

    What the IRD said before

    Readers would likely be familiar with the “Departmental Interpretation and Practice Notes No. 21 – Locality of Profits” (Revised in July 2012).  The IRD’s views which are reflected in its assessing practice on the locality of profits derived from trading in commodities or goods by a business carried on in Hong Kong are contained in Para 23, as follows:

    (a) Where both the contract of purchase and contract of sale are effected in Hong Kong, the profits are fully taxable.
    (b) Where both the contract of purchase and contract of sale are effected outside Hong Kong, no part of the profits are taxable.
    (c) Where either the contract of purchase or contract of sale is effected in Hong Kong, the initial presumption will be that the profits are fully taxable.
    (d) Where the sale is made to a Hong Kong customer (including the Hong Kong buying office of an overseas customer), the sale contract will usually be taken as having been effected in Hong Kong.
    (e) Where the commodities or goods are purchased from either a Hong Kong supplier or manufacturer, the purchase contract will usually be taken as having been effected in Hong Kong.
    (f) Where the effecting of the purchase and sale contracts does not require travel outside Hong Kong but is carried out in Hong Kong by telephone, fax, etc., the contracts will be considered as having been effected in Hong Kong.
    (g) The purchase and sale contracts are important factors but all the relevant operations that produce the trading profits must be looked at to determine the locality of the profits.

    DIPN 21 Para 24 reads: “Having regard to the points expressed above [author: (a) to (g) above], it will be apparent that, in the Department’s view, the question of apportionment does not arise in relation to trading profits. Trading profits will be either wholly taxable or wholly non-taxable. There is no room to substitute a mixed source for a Hong Kong source even though there might be some overseas activities”.

    After revisiting DIPN 21 and look back to the case, would readers agree to the statements made by the IRD representative and the decision of the BOR?  They both placed high importance on the role of the Hong Kong company but did not say anything about the contracts were entered into and performed outside Hong Kong.  They focused on the essential role that the Hong Kong company played and determined the source of profits based entirely on this factor; yet the source of profits has always been determined based on the conclusion of the sales and purchase contract, but not the level of importance of the Hong Kong company (is there any middleman that has no role and not needed?).  Further, without the sales and purchase contracts, there would not be any profits.  If there is another identical case but without the “Three Direct Links” background (for example, replace Taiwan Co with a UK company), would the IRD and the BOR maintain the same judgment?  If the conclusion would be different (offshore profits), then I would recommend the IRD to revise DIPN 21 so that taxpayers would know under what situations would profit be treated as onshore even when the contracts are effected and performed outside of Hong Kong.  If the conclusion is the same (source of profits is determined based on the taxpayer’s role and degree of importance), the territorial concept of taxation is effectively abolished, and the Government should commence tax reform and amend the IRO as soon as possible.   

    An alternative route is profit apportionment.  DIPN 21 Para 46 mentioned “The Department accepts that, notwithstanding the absence of a specific provision for apportionment of profits in the IRO, there are certain situations in which an apportionment of the chargeable profits is appropriate. The example of manufacturing profits has already been explained above. A further example is service fee income where the services are performed partly in Hong Kong and partly outside. On the other hand, as has been mentioned in paragraph 24 above, the Department does not find an apportionment of trading profits is required”.  If the IRD no longer follows principles set out in Para 23, what is the reason for sticking to the principle of no apportionment of trading profits?

    This case reflects the IRD’s approach to the territorial concept of taxation has changed.   Numerous taxpayers may currently be in dispute with the IRD over the source of profit.  When facing unreasonable assessments, many taxpayers may prefer to settle the case in view of the long appeal time and high costs.  It is likely that this case of Co A will be cited by the IRD in future disputes with taxpayers.  The Financial Secretary, Mr. Paul Chan, said at the end of his speech that “Our tax system is simple and clear, and its implementation is fair and consistent…we absolutely do not want to gradually make our tax system more complex, which would lead to disproportionate increase in tax administrative costs and corporate compliance costs”.  In the face of today’s environment, is Hong Kong’s tax system still territorial based, easy and straightforward, apply equally to all, consistent in implementation, and low in compliance costs?  Can Hong Kong continue to be, in the eyes of the Financial Secretary, the world’s premier business location?  In the environment of BEPS, it seems that it is time to consult the Hong Kong people for a tax reform.

    Tax Tips :

    1. The case of A Co could have been resolved satisfactorily during the enquiry stage, and maintain that the profits were arising in or derived from outside Hong Kong.  There are certain techniques in answering queries from the IRD; other than pointing out the relevant legal provisions and cases, if the IRD’s views are unreasonable, one had to point out directly the issue, such as asking the above question “If there is another identical case but without the “Three Direct Links” background (for example, replace Taiwan Co with a UK company), would the IRD argue the same?”.  Besides the source of profit, the IRD’s approach in determining revenue and capital expenditures can sometimes be unreasonable too.  As taxpayer or tax representative one has to know how to close the issue at an early stage.  
    2. The case also has Mainland tax implications.  Co A would likely have created a permanent establishment in the Mainland (or even in Taiwan), and the Mainland tax authorities could impose corporate income tax at 25% on the profits of Co A (and Co A should claim the profits tax suffered in this appeal case from the IRD under the Hong Kong-Mainland Double Tax Arrangement?).  Further, as Co A has no substance in Hong Kong, the IRD may not issue the Certificate of Residence to Co A, and the Mainland authorities would unlikely consider Co A as the beneficial owner of dividend from Mainland Co, so that Co A would not be able to enjoy the 5% dividend withholding tax rate under the Double Tax Arrangement but would need to pay 10% instead.  Hong Kong taxpayers conducting similar business should learn from the case in how to improve the overall arrangement.  

    Author: Edwin Bin

    Ref:

    FS’ Speech at Tax Summit (Chinese only): http://www.info.gov.hk/gia/general/201710/23/P2017102300746.htm

    D25/14: http://www.info.gov.hk/bor/tc/docs/D2514.pdf

    DIPN 21: https://www.ird.gov.hk/eng/pdf/e_dipn21.pdf